
Market Overview
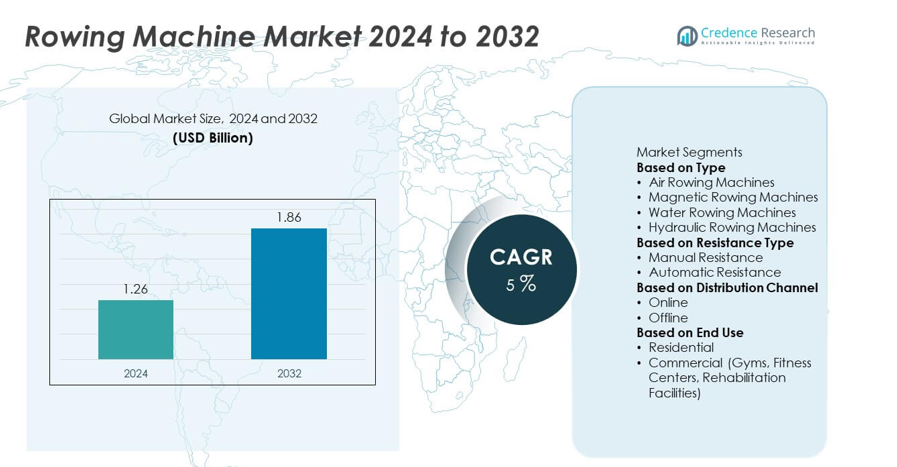
The rowing machine market was valued at USD 1.26 billion in 2024 and is projected to reach USD 1.86 billion by 2032, growing at a CAGR of 5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Rowing machine market Size 2024 | USD 1.26 billion |
| Rowing machine market, CAGR | 5% |
| Rowing machine market Size 2032 | USD 1.86 billion |
The rowing machine market is led by major players including Concept2 Inc., WaterRower Inc., Technogym S.p.A., Life Fitness, NordicTrack (ICON Health & Fitness Inc.), Stamina Products Inc., Bodycraft, JTX Fitness, XTERRA Fitness Inc., and Sunny Health & Fitness. These companies emphasize advanced resistance technologies, connected fitness integration, and ergonomic designs to enhance performance and user engagement. Product innovation and sustainability are key competitive strategies. Regionally, Asia-Pacific dominated the global market in 2024 with a 33.8% share, driven by rapid urbanization and growing home fitness adoption, followed by North America with 31.6% and Europe with 27.4%, supported by expanding gym infrastructure and increasing digital fitness penetration.
Market Insights
- The rowing machine market was valued at USD 1.26 billion in 2024 and is projected to reach USD 1.86 billion by 2032, growing at a CAGR of 5%.
- Increasing health awareness and rising participation in home-based workouts drive market demand, with the air rowing machine segment holding a 39.6% share in 2024.
- Integration of smart connectivity, digital tracking, and virtual training programs continues to shape market trends and attract tech-savvy users.
- Leading players such as Concept2 Inc., WaterRower Inc., Technogym S.p.A., Life Fitness, and NordicTrack focus on innovation, ergonomic designs, and sustainable materials to strengthen their market position.
- Regionally, Asia-Pacific led the market with a 33.8% share in 2024, followed by North America at 31.6% and Europe at 27.4%, supported by expanding gym infrastructure, digital fitness growth, and rising adoption of compact home workout equipment.
Market Segmentation Analysis:
By Type
The air rowing machine segment dominated the rowing machine market in 2024 with a 39.6% share. Its popularity stems from its smooth, variable resistance and ability to simulate real rowing dynamics, making it preferred among athletes and fitness enthusiasts. The segment’s demand is supported by widespread use in gyms and professional training facilities. Water and magnetic rowing machines are also gaining traction for their quiet operation and aesthetic appeal, while hydraulic models remain popular in home-use categories due to affordability and compact design, especially in emerging markets.
- For instance, Concept2’s Model D Indoor Rowing Machine, renowned for durability and an advanced performance monitor, remains the preferred choice among athletes and gyms worldwide.
By Resistance Type
The automatic resistance segment held the largest market share of 56.4% in 2024, driven by the increasing integration of digital controls and connected fitness technologies. These systems allow users to automatically adjust resistance levels for personalized and adaptive workouts. Growing adoption of smart fitness equipment with Bluetooth and app connectivity supports this dominance. Manual resistance machines continue to serve budget-conscious consumers and home fitness setups, though demand is gradually shifting toward programmable and interactive workout systems across both residential and commercial environments.
- For instance, the Speediance Gym Monster offers up to 220 pounds of digital resistance and various attachments, enabling users to seamlessly switch resistance modes for a tailored workout experience.
By Distribution Channel
The offline segment accounted for a dominant 62.7% share of the rowing machine market in 2024, supported by strong presence in fitness equipment stores, specialty retailers, and gym suppliers. Consumers prefer physical outlets for product trials, demonstrations, and after-sales services. However, the online segment is expanding rapidly, driven by e-commerce growth and rising consumer preference for convenience and price transparency. Manufacturers are enhancing digital sales strategies through direct-to-consumer platforms and partnerships with online retailers, contributing to increased market penetration across domestic and international markets.
Key Growth Drivers
Rising Health and Fitness Awareness
Increasing global awareness of fitness and preventive healthcare is a major driver for the rowing machine market. Consumers are adopting rowing workouts for their full-body benefits, improving cardiovascular endurance and muscle strength. The trend toward home-based fitness, fueled by hybrid work lifestyles, further supports demand. Fitness influencers and digital platforms are promoting rowing as an efficient low-impact exercise, boosting adoption across age groups. This growing focus on personal health and holistic wellness continues to drive consistent market expansion.
- For instance, Technogym S.p.A, a leading fitness equipment company, reported strong adoption of its state-of-the-art rowing machines integrated with wellness technology, particularly in high-end gyms and health clubs, reflecting growing consumer interest in holistic fitness solutions.
Expansion of Commercial Fitness Facilities
The rapid expansion of gyms, health clubs, and rehabilitation centers is fueling market growth for rowing machines. Commercial fitness chains prioritize durable, versatile equipment offering high-intensity and endurance training benefits. Rowing machines provide multi-muscle engagement and compact design, making them ideal for professional setups. Rising investments in corporate wellness programs and boutique fitness studios also drive installations. Manufacturers cater to this segment by developing advanced models with digital tracking and interactive training options to enhance user engagement and retention.
- For instance, companies like Afton Fitness supply heavy-duty rowing machines from trusted brands such as Spirit and Impulse, designed for smooth, low-impact, full-body workouts favored in professional gym setups.
Technological Advancements and Smart Integration
Technological innovation is transforming rowing machine design and performance. Integration of smart connectivity features such as Bluetooth synchronization, live performance tracking, and app-based coaching enhances user experience. Connected rowing platforms allow users to join virtual classes and monitor progress in real time. Manufacturers are introducing AI-enabled resistance adjustment and performance analytics to personalize workouts. This technological shift is attracting tech-savvy consumers and fitness enthusiasts, aligning with the growing global trend toward connected fitness ecosystems.
Key Trends & Opportunities
Growth of Home Fitness and E-Commerce Channels
The rise of home fitness trends and online retail channels presents major opportunities for rowing machine manufacturers. Consumers increasingly purchase fitness equipment online for convenience, affordability, and access to a wide product range. Compact, foldable, and easy-to-install models are gaining popularity among urban users. Brands are enhancing digital marketing and direct-to-consumer sales strategies to tap into this expanding segment. Subscription-based online training programs and interactive virtual classes further boost the appeal of home-based rowing workouts.
- For instance, Concept2 dominates online sales with its RowErg indoor rowing machine consistently leading Amazon's top seller lists, reflecting strong customer trust in its durability and performance.
Increasing Demand for Eco-Friendly and Ergonomic Designs
Manufacturers are focusing on sustainable materials and ergonomic designs to meet evolving consumer preferences. Wooden rowing machines made from renewable sources and low-noise mechanisms are attracting environmentally conscious buyers. Ergonomic designs improve posture and comfort, appealing to both beginners and rehabilitation users. The shift toward eco-friendly manufacturing also aligns with broader sustainability goals across fitness equipment production. This growing focus on design innovation and environmental responsibility is creating long-term opportunities in the premium product category.
- For instance, WaterRower and its sister company NOHrD produce high-end wooden rowing machines crafted from sustainably sourced woods, emphasizing environmental protection and premium design.
Key Challenges
High Equipment Costs and Maintenance Needs
High upfront investment and ongoing maintenance requirements remain major barriers to market growth. Advanced rowing machines equipped with digital consoles, sensors, and connectivity features are expensive for home users. Regular maintenance of moving parts and resistance systems increases long-term ownership costs. Price sensitivity in developing regions limits adoption, particularly in residential applications. Manufacturers are addressing this challenge by introducing mid-range models that balance performance, durability, and affordability to reach a wider consumer base.
Limited Awareness in Emerging Economies
In developing regions, lack of awareness about rowing’s fitness benefits and the availability of advanced equipment hinders market penetration. Consumers often prefer treadmills or stationary bikes due to familiarity and accessibility. Limited distribution networks and higher import costs further restrict product reach. To overcome these barriers, global brands are partnering with local retailers and fitness influencers to promote awareness and affordability. Expanding marketing efforts and offering localized product variations can help unlock significant untapped demand in these markets.
Regional Analysis
North America
North America held a 31.6% share of the rowing machine market in 2024, driven by the strong culture of fitness and wellness across the U.S. and Canada. The region benefits from widespread gym memberships, growing home fitness adoption, and high awareness of digital workout technologies. Consumers favor connected and interactive rowing machines offering real-time tracking and virtual training experiences. The presence of leading brands and e-commerce expansion further supports growth. Increasing corporate wellness programs and health-conscious lifestyles continue to strengthen regional demand for advanced rowing equipment.
Europe
Europe accounted for a 27.4% share of the rowing machine market in 2024, supported by the rising popularity of indoor rowing as a low-impact, full-body exercise. The UK, Germany, and France are leading contributors due to strong gym infrastructure and increasing investment in home fitness solutions. The region’s focus on sustainable product design and digital connectivity drives product innovation. Manufacturers are introducing eco-friendly materials and ergonomic models to meet European sustainability standards. Growing participation in rowing-based training and rehabilitation programs further enhances regional market expansion.
Asia-Pacific
Asia-Pacific dominated the global rowing machine market in 2024 with a 33.8% share and is expected to record the fastest growth through 2032. Rising disposable incomes, urbanization, and the expansion of fitness centers in China, India, and Japan drive market development. The growing preference for home fitness equipment, supported by compact and affordable product options, fuels adoption. Increasing awareness of physical wellness and rising e-commerce penetration enhance accessibility. Regional manufacturers are also introducing smart and connected models tailored for younger, tech-oriented consumers seeking digital workout solutions.
Latin America
Latin America represented a 4.2% share of the rowing machine market in 2024, led by Brazil and Mexico. The region’s growing fitness culture and the establishment of mid-tier gyms are supporting equipment demand. Awareness of the health benefits of rowing as a full-body exercise is expanding, particularly among urban consumers. However, economic instability and high import costs limit premium equipment penetration. Manufacturers are partnering with regional distributors to offer cost-effective models and flexible payment options, driving gradual market expansion in both residential and commercial fitness sectors.
Middle East & Africa
The Middle East & Africa accounted for a 3.0% share of the rowing machine market in 2024, supported by growing investment in sports and wellness infrastructure. Countries such as the UAE, Saudi Arabia, and South Africa are adopting rowing machines across premium gyms, hotels, and rehabilitation centers. Rising tourism and government initiatives promoting healthy lifestyles contribute to market growth. However, limited consumer awareness and high equipment prices restrict adoption in low-income areas. Increasing retail presence and expanding fitness chains are expected to gradually strengthen regional market penetration.
Market Segmentations:
By Type
- Air Rowing Machines
- Magnetic Rowing Machines
- Water Rowing Machines
- Hydraulic Rowing Machines
By Resistance Type
- Manual Resistance
- Automatic Resistance
By Distribution Channel
- Online
- Offline
By End Use
- Residential
- Commercial (Gyms, Fitness Centers, Rehabilitation Facilities)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The rowing machine market is characterized by strong competition among key players such as Concept2 Inc., WaterRower Inc., Technogym S.p.A., Life Fitness, NordicTrack (ICON Health & Fitness Inc.), Stamina Products Inc., Bodycraft, JTX Fitness, XTERRA Fitness Inc., and Sunny Health & Fitness. These companies focus on product innovation, digital connectivity, and ergonomic design to enhance user experience and maintain brand leadership. Leading manufacturers are integrating smart technologies such as Bluetooth connectivity, performance tracking, and app-based training programs. Strategic collaborations with fitness studios, online training platforms, and retail distributors are strengthening market reach. Sustainability and the development of eco-friendly materials are also gaining importance in premium product lines. As competition intensifies, companies are expanding global distribution networks, improving affordability, and investing in R&D to meet the growing demand for home fitness and commercial gym applications.
Key Player Analysis
- Concept2 Inc.
- WaterRower Inc.
- Technogym S.p.A.
- Life Fitness
- NordicTrack (ICON Health & Fitness Inc.)
- Stamina Products Inc.
- Bodycraft
- JTX Fitness
- XTERRA Fitness Inc.
- Sunny Health & Fitness
Recent Developments
- In September 2025, Hydrow introduced its most advanced Hydrow Arc Rower, equipped with a 24-inch HD display, premium sound system, and an upgraded “HydroMetrics” performance tracking feature.
- In March 2025, Hydrow partnered with Soho House to integrate its connected rowing machines across select luxury club fitness centers worldwide.
- In July 2024, Ergatta collaborated with CityRow to incorporate instructor-led studio sessions into its game-based rowing platform, enhancing user engagement and workout diversity.
Report Coverage
The research report offers an in-depth analysis based on Type, Resistance Type, Distribution Channel, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for rowing machines will continue to rise with growing fitness awareness.
- Smart and connected rowing machines will dominate future product development.
- Home fitness adoption will expand due to compact and foldable equipment designs.
- Integration of virtual training and subscription-based workout platforms will increase.
- Manufacturers will focus on eco-friendly and durable materials to meet sustainability goals.
- The commercial gym segment will continue to invest in high-performance rowing systems.
- Asia-Pacific will remain the fastest-growing region due to urbanization and rising incomes.
- AI-enabled resistance and performance tracking will enhance personalized training experiences.
- Collaborations between fitness equipment makers and digital wellness platforms will grow.
- Increasing corporate wellness programs will create new opportunities for rowing machine adoption.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Rowing Machine Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Rowing Machine Market projected to grow between 2025 and 2032?
Which Rowing Machine Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Rowing Machine Market?
Who are the leading companies in the Rowing Machine Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1.26 billion → 2032: USD 1.86 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Rowing Machine Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Rowing Machine Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Rowing Machine Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Rowing Machine Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Rowing Machine Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Rowing Machine Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Rowing Machine Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Rowing Machine Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1.26 billion → 2032: USD 1.86 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Rowing Machine Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Rowing Machine Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Rowing Machine Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Rowing Machine Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

