
Savory Snacks Market Overview:
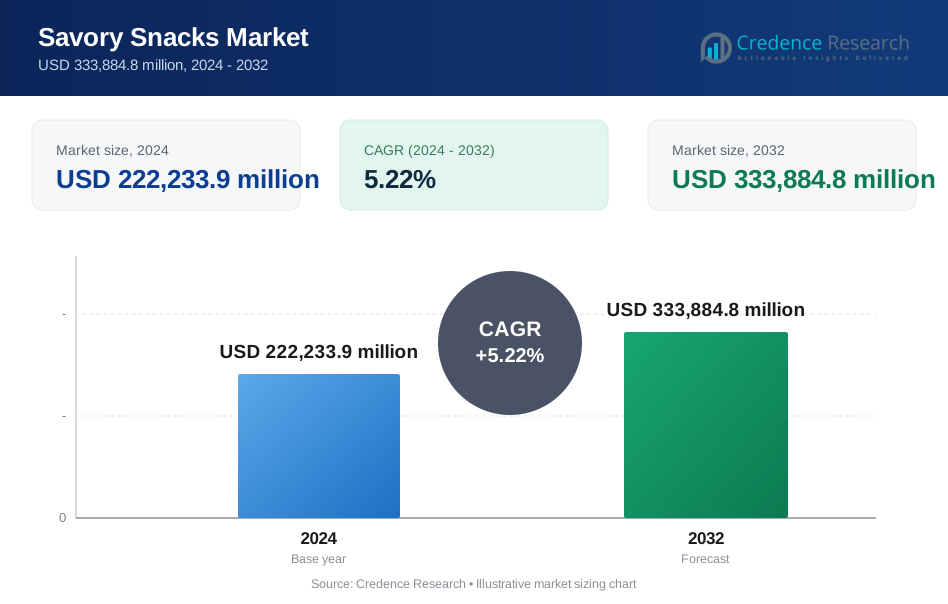
The savory snacks market was valued at USD 222,233.9 million in 2024 and is expected to reach USD 333,884.8 million by 2032, growing at a CAGR of 5.22% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Savory Snacks Market Size 2024 | USD 222,233.9 million |
| Savory Snacks Market, CAGR | 5.22% |
| Savory Snacks Market Size 2032 | USD 333,884.8 million |
Savory Snacks Market Insights
- Convenience-driven consumption acts as a key market driver, with potato chips leading the product segment at a 41% share due to wide acceptance and frequent purchase behavior.
- Major market trends include rising demand for mass-priced snacks, which hold a 63% share, driven by affordability, smaller pack sizes, and high penetration in emerging markets.
- Competitive analysis shows intense rivalry among global and regional brands focusing on flavor innovation, healthier formulations, and wide retail distribution to maintain shelf presence.
- Regional analysis indicates North America leads with a 32% market share, followed by Asia Pacific at 29%, Europe at 24%, Latin America at 9%, and the Middle East and Africa at 6%.

Savory Snacks Market Segmentation Analysis:
By Product
By product, potato chips dominate the savory snacks market with a 41% market share, driven by widespread consumer acceptance and frequent consumption across age groups. Strong flavor innovation, affordable pricing, and wide availability support consistent demand. Manufacturers continuously introduce new seasonings and healthier variants to retain interest. Corn and tortilla chips follow, supported by rising demand for ethnic and tex-mex snacks. Nuts and seeds hold a growing share due to increasing preference for protein-rich and perceived healthier snack options. The others category, including popcorn and mixed snacks, supports variety-driven consumption and impulse purchases.
- For instance, PepsiCo expanded its oven-baked Lay’s line and significantly reduced the sodium content in several of its most popular flavors.
By Distribution Channel
By distribution channel, hypermarkets and supermarkets lead with a 48% market share, supported by high footfall, broad product assortments, and promotional pricing. Consumers prefer these stores for bulk purchases and brand variety. Strong shelf visibility supports impulse buying. Convenience stores follow, driven by on-the-go consumption and urban lifestyles. Online channels hold a smaller but expanding share, supported by home delivery, subscription models, and wider product access. Other channels, including vending and specialty stores, support localized and impulse-driven demand.
- For instance, Walmart expanded its snack and grocery assortments as part of its multi-year store remodeling initiative. Convenience stores follow this trend, driven by on-the-go consumption and dense urban coverage.
Key Growth Drivers
Expansion of On-the-Go and Convenience Snacking
Busy lifestyles strongly drive demand in the savory snacks market. Consumers increasingly replace full meals with quick snack options. Urbanization and longer working hours support frequent snacking occasions. Savory snacks offer portability, long shelf life, and easy consumption. Single-serve and resealable packaging improve convenience and portion control. Retailers expand snack assortments near checkout counters to boost impulse purchases. This driver remains strong across working professionals, students, and travelers. Consistent demand from daily consumption patterns supports stable volume growth across mass and premium snack categories.
- For instance, Mondelēz International reported that a majority of global consumers now prefer eating small snacks throughout the day rather than traditional meals.
Continuous Product Innovation and Flavor Diversification
Product innovation plays a critical role in market growth. Manufacturers regularly launch new flavors, textures, and formats to maintain consumer interest. Regional and ethnic flavors gain popularity across global markets. Limited-edition offerings and seasonal launches create short-term demand spikes. Innovation also extends to cooking methods such as baked and air-popped snacks. These developments support brand differentiation and shelf visibility. Strong marketing and rapid product rotation help companies capture evolving taste preferences and maintain competitive advantage.
- For instance, Calbee released 18 new region-specific flavors in Japan’s snack portfolio in one year. Limited-edition and seasonal launches drive short-term spikes.
Rising Penetration in Emerging Markets
Emerging economies contribute significantly to savory snacks market expansion. Rising disposable income increases spending on packaged foods. Urban population growth supports modern retail development and product availability. Younger consumers show high preference for branded snack products. Local manufacturers expand distribution networks to rural and semi-urban areas. Affordable pricing and smaller pack sizes improve accessibility. This driver supports volume-led growth across Asia Pacific, Latin America, and parts of Africa.
Key Trends and Opportunities
Growing Demand for Better-for-You Snack Options
Health awareness shapes product development strategies. Consumers seek snacks with lower fat, reduced sodium, and clean-label ingredients. Nuts, seeds, and baked snacks gain traction as healthier alternatives. Manufacturers reformulate products to balance taste and nutrition. Functional ingredients and protein-rich snacks attract health-conscious buyers. This trend creates opportunities for premium positioning and portfolio diversification while retaining core snack appeal.
- For instance, PepsiCo reduced sodium in select savory snacks by 100 milligrams per serving through ingredient changes.
Rapid Growth of Online and Direct-to-Consumer Channels
Digital channels create new growth opportunities for snack brands. Online platforms offer wider product access and convenience. Subscription models support repeat purchases and brand loyalty. Data-driven marketing improves consumer targeting. Brands use direct-to-consumer platforms to test new products quickly. This trend supports faster market penetration and stronger customer engagement, especially among younger consumers.
- For instance, Hershey used online analytics across 50 million digital shopper interactions to guide savory snack launches.
Key Challenges
Health Concerns and Regulatory Pressure
Rising concerns over obesity and lifestyle diseases challenge the savory snacks market. High salt, fat, and calorie content attract regulatory scrutiny. Governments introduce labeling requirements and marketing restrictions. These factors pressure manufacturers to reformulate products. Balancing taste with nutritional improvement remains complex. Compliance costs increase operational burden, especially for smaller players.
Intense Competition and Price Sensitivity
The market faces intense competition from global and local brands. Private labels increase pricing pressure. Consumers often switch brands based on promotions and discounts. Raw material price fluctuations impact margins. Maintaining profitability while offering competitive pricing remains challenging. Strong brand equity and efficient supply chains become essential for sustained performance.
Regional Analysis
North America
North America holds 32% market share in the savory snacks market, driven by strong snacking culture and high consumption of packaged foods. Consumers frequently purchase potato chips, tortilla chips, and nuts for on-the-go consumption. Product innovation, including new flavors and healthier variants, supports steady demand. Well-developed retail infrastructure and strong presence of leading brands enhance product availability. Online sales channels also contribute to growth through convenience and subscription models. High disposable income and frequent impulse buying continue to support consistent volume demand across both mass and premium snack categories.
Europe
Europe accounts for 24% market share, supported by diverse consumer preferences and strong demand for traditional and baked snack products. Health awareness influences purchasing decisions, increasing demand for nuts, seeds, and reduced-salt snacks. Regulatory focus on food labeling encourages product reformulation. Supermarkets and hypermarkets dominate distribution due to wide assortments and private-label offerings. Regional flavors and premium positioning attract consumers seeking quality and variety. Stable consumption patterns and strong brand loyalty sustain market growth across Western and Central European countries.
Asia Pacific
Asia Pacific commands 29% market share, driven by rapid urbanization, population growth, and rising disposable income. Increasing adoption of western-style snacking habits fuels demand for chips and extruded snacks. Young consumers and expanding middle-class populations drive volume growth. Affordable pricing and small pack sizes support penetration in price-sensitive markets. Modern retail expansion and strong online channel growth improve accessibility. Local flavor innovation and aggressive marketing campaigns further strengthen regional demand across major economies.
Latin America
Latin America holds 9% market share, supported by growing urban populations and increasing consumption of packaged snacks. Corn-based snacks and flavored chips remain popular across the region. Economic recovery and expanding retail networks support demand growth. Price sensitivity drives preference for mass-market products and local brands. Promotional activities and smaller pack formats improve affordability. While premium snack adoption remains limited, rising youth consumption and modern trade expansion support gradual market development.
Middle East and Africa
The Middle East and Africa represent 6% market share, driven by expanding retail infrastructure and rising consumption of packaged foods. Urbanization and changing lifestyles increase demand for convenient snack options. Savory snacks gain traction in convenience stores and supermarkets. Demand remains concentrated in urban centers and high-income countries. Import dependence influences product pricing and availability. Growing youth population and increasing exposure to global snack brands support long-term growth potential across the region.
Savory Snacks Market Segmentations:
By Product
- Potato Chips
- Corn & Tortilla Chips
- Nuts & Seeds
- Others
By Distribution Channel
- Hypermarkets & Supermarkets
- Convenience Stores
- Online
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis highlights a highly competitive savory snacks market led by key players including PepsiCo, The Kraft Heinz Company, The Kellogg Company, Calbee, Hain Celestial, Conagra Brands, General Mills, Blue Diamond Growers, ITC Limited, and Grupo Bimbo. These companies compete through strong brand portfolios, wide distribution networks, and continuous product innovation. Leading players focus on flavor expansion, healthier formulations, and portion-controlled packaging to meet changing consumer preferences. Investments in manufacturing efficiency and supply chain optimization support large-scale production. Private-label competition and regional brands increase pricing pressure, encouraging aggressive promotional strategies. Companies also expand digital and direct-to-consumer channels to improve reach. Strategic acquisitions and regional expansions strengthen market presence. Sustainability initiatives, including responsible sourcing and recyclable packaging, further influence competitive positioning across global markets.
Key Player Analysis
- Grupo Bimbo
- Blue Diamond Growers
- Conagra Brands, Inc.
- Calbee
- ITC Limited
- General Mills, Inc.
- The Kraft Heinz Company
- Hain Celestial
- PepsiCo
- The Kellogg Company
Recent Developments
- In September 2025, PepsiCo expanded its Kurkure brand into the millet-based snack category with Kurkure Jowar Puffs to tap into traditional grains and mindful snacking.
- In September 2025, ITC joined PepsiCo and investors in talks to acquire a stake in Balaji Wafers, showing strategic interest in savory snack market growth.
- In July 2025, Grupo Bimbo pledged to remove all artificial colorants from its products by end-2026 to improve nutrition and meet health trends.
Report Coverage
The research report offers an in-depth analysis based on Product, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Snacking frequency will increase as consumers adopt flexible eating habits.
- Demand for convenient and portable snack formats will remain strong.
- Flavor innovation and regional taste customization will accelerate product launches.
- Health-focused reformulation will gain priority across major brands.
- Nuts and seeds will see higher adoption due to protein-rich positioning.
- Mass-priced products will continue to drive volume growth.
- Online and direct-to-consumer channels will expand distribution reach.
- Emerging markets will contribute a larger share of global demand.
- Sustainable packaging initiatives will influence purchasing decisions.
- Brand differentiation and marketing will remain critical for competitive success.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of On-the-Go and Convenience Snacking
Busy lifestyles and urbanization are increasing the frequency of snacking occasions, with consumers seeking portable, easy-to-consume savory snacks. Single-serve and resealable packaging formats further drive demand by offering convenience and portion control.
Continuous Product Innovation and Flavor Diversification
Manufacturers are regularly launching new flavors, textures, and formats, including regional and ethnic varieties, to maintain consumer interest and differentiate brands. Limited-edition and healthier variants attract new customers and encourage repeat purchases.
Rising Penetration in Emerging Markets
Growth in disposable incomes, urban population, and modern retail infrastructure in emerging economies is expanding the consumer base for savory snacks. Affordable pricing and smaller pack sizes make these products accessible to a wider demographic, supporting volume-led growth.
Growing Demand for Better-for-You Snack Options
Health-conscious consumers are increasingly seeking snacks with lower fat, reduced sodium, and clean-label ingredients. This trend is driving manufacturers to reformulate products and introduce protein-rich and functional snack options, expanding the market to new consumer segments.
Rapid Growth of Online and Direct-to-Consumer Channels
Digital platforms are making savory snacks more accessible, supporting home delivery, subscription models, and targeted marketing. Brands leverage these channels to reach younger consumers and test new products quickly, accelerating market penetration.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Savory Snacks market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Savory Snacks market projected to grow between 2024 and 2032?
Which Savory Snacks market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Savory Snacks market?
Who are the leading companies in the Savory Snacks market?
Which region commanded the largest share of the Savory Snacks market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Potato Chips
- 1.2.2 Corn & Tortilla Chips
- 1.2.3 Nuts & Seeds
- 1.2.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 222,233.9 million → 2032: USD 333,884.8 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Savory Snacks Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Savory Snacks Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Savory Snacks Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Savory Snacks Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Savory Snacks Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Savory Snacks Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Savory Snacks Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Savory Snacks Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 222,233.9 million → 2032: USD 333,884.8 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Savory Snacks Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Potato Chips
- 12.3.7.2 Corn & Tortilla Chips
- 12.3.7.3 Nuts & Seeds
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 Segment Growth Comparison
- 12.5 Segment Attractiveness and Priority Matrix
Chapter 13 Global Savory Snacks Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Savory Snacks Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Savory Snacks Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 PepsiCo
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 The Kraft Heinz Company
- 17.4 The Kellogg Company
- 17.5 Calbee
- 17.6 Hain Celestial
- 17.7 Conagra Brands
- 17.8 General Mills
- 17.9 Blue Diamond Growers
- 17.10 ITC Limited
- 17.11 Grupo Bimbo
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

