
Market Overview
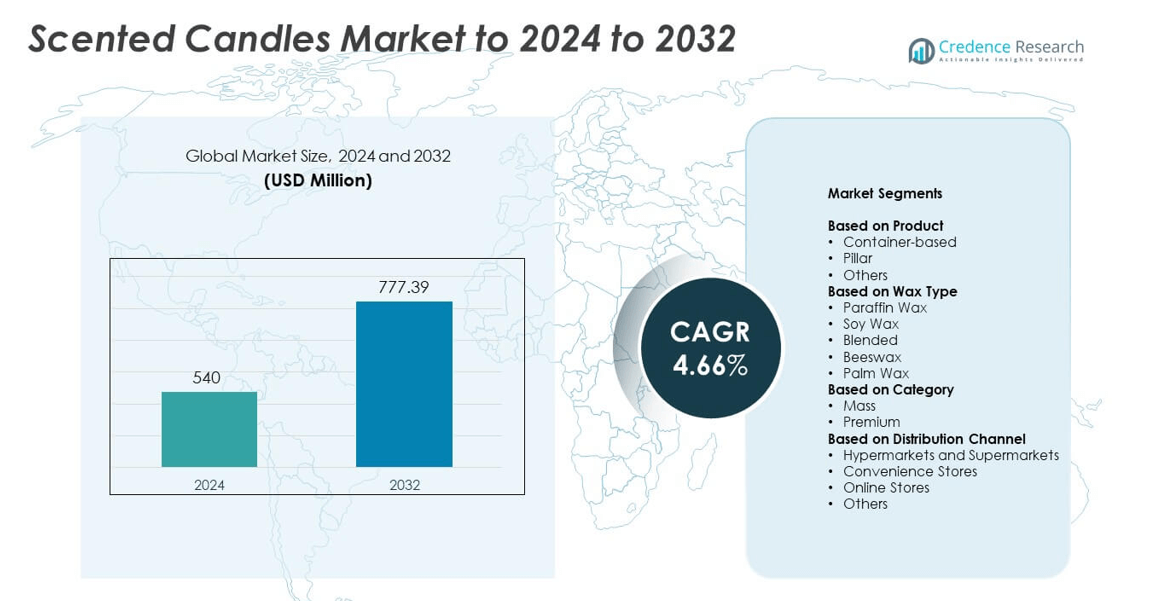
Scented Candles Market size was valued at USD 540 Million in 2024 and is anticipated to reach USD 777.39 Million by 2032, at a CAGR of 4.66% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Scented Candles Market Size 2024 | USD 540 Million |
| Scented Candles Market, CAGR | 4.66% |
| Scented Candles Market Size 2032 | USD 777.39 Million |
The scented candles market includes major players such as NEST New York, Hotel Lobby Candle, L Brands, Diptyque Paris, Lalique Group SA, MVP Group International, Village Candle, Newell Brands, Portmeirion Group PLC, and Thymes. These companies grow through premium fragrances, clean-label wax blends, and strong retail and online distribution. North America leads the global market with about 37% share in 2024, driven by high home fragrance adoption and strong gifting demand. Europe follows with around 29% share, supported by premium product preference and established décor culture, while Asia Pacific expands rapidly due to rising urban incomes and wellness-focused spending.
Market Insights
- The scented candles market reached USD 540 Million in 2024 and is projected to hit USD 777.39 Million by 2032, advancing at a CAGR of 4.66%. • Growing use of candles for home ambience and aromatherapy drives demand, with container-based products holding about 62% share due to safer burning and stronger fragrance performance. • Trends shift toward natural waxes and clean-label blends, supporting the dominance of soy wax at nearly 48% share and boosting premium, wellness-inspired collections. • Competition intensifies as brands expand seasonal launches, invest in sustainable packaging, and strengthen online visibility, while value-focused players maintain reach through mass retail; however, rising raw material prices limit margins. • North America leads with about 37% share, followed by Europe at 29% and Asia Pacific at 22%, while Latin America (7%) and the Middle East & Africa (5%) show steady growth supported by rising lifestyle spending and broader retail access.
Market Segmentation Analysis:
By Product
Container-based candles lead this segment with about 62% share in 2024. Buyers prefer container formats because the enclosed design offers safer burning, longer fragrance diffusion, and stronger aesthetic appeal for homes and offices. Brands widen adoption by launching glass jars, ceramic holders, and reusable vessels that match interior décor trends. Pillar and other formats grow at a steady pace as consumers purchase decorative shapes for events and seasonal themes, but container-based products remain dominant due to strong retail visibility and frequent gifting demand.
- For instance, Newell Brands' primary home fragrance manufacturing facility in Whately, Massachusetts, maintains a production volume of more than 85 million candles and 15 million flameless products per year.
By Wax Type
Soy wax dominates this segment with nearly 48% share in 2024. Demand rises because soy delivers cleaner burning, longer lifespan, and better scent throw than paraffin, which helps eco-conscious buyers shift toward natural wax products. Brands promote soy-based blends to meet sustainability expectations and reduce soot formation. Paraffin maintains usage in low-cost candles, while beeswax and palm wax gain niche traction among premium buyers. However, soy wax continues to lead due to strong availability, renewable sourcing, and broad acceptance across mass and premium price points.
- For instance, Aveda sells its Rosemary Mint Vegan Soy Candle in sizes including 7.8 oz (230ml) and 3.5 oz options. These products explicitly specify a 100% naturally derived soy wax formulation, demonstrating how Aveda emphasizes plant-based ingredients in its home-fragrance candles.
By Category
The mass category holds the leading position with around 67% share in 2024. High-volume retail sales, competitive pricing, and wide fragrance variety support stronger penetration across supermarkets, discount stores, and online platforms. Consumers purchase mass candles for everyday ambiance, seasonal gifting, and home décor needs, keeping demand steady throughout the year. The premium segment grows as buyers seek artisanal scents, natural wax blends, and visually distinctive jars, but mass products remain dominant due to affordability, repeat purchases, and strong private-label expansion.
Key Growth Drivers
Rising Home Fragrance Adoption
Growing interest in home fragrance boosts scented candle demand as consumers seek relaxed indoor environments. Households use candles for mood setting, décor enhancement, and aromatherapy, which strengthens repeat purchases. Retailers expand fragrance choices such as floral, woody, and wellness-focused blends that appeal to diverse preferences. This wider availability supports strong market momentum across both mass and premium categories.
- For instance, the National Candle Association notes that U.S. consumers can choose from more than 10,000 different candle scents, underlining how broad fragrance variety now supports frequent home-fragrance purchasing and usage.
Growth of Premium and Decorative Candles
Premium candle lines gain traction due to the rising preference for elegant jars, natural waxes, and sophisticated fragrances. Consumers view premium candles as décor items and lifestyle products, leading to higher spending in urban markets. Brands introduce artisanal scents and limited-edition designs that increase perceived value and encourage gifting. This shift toward premiumization strengthens brand differentiation and accelerates revenue growth.
- For instance, Diptyque runs 140 standalone boutiques worldwide and has a presence across roughly 1,000 points of sale spanning over 30 countries, offering approximately 300 SKUs that include premium scented candles in distinctive glass and decorative vessels.
Expanding E-commerce Penetration
Online platforms play a major role in driving sales through broad fragrance assortments, competitive pricing, and subscription-based models. Digital promotions help brands reach new customer groups, especially young buyers who rely on product reviews and curated collections. Faster delivery and attractive bundle packs further improve adoption. E-commerce also boosts visibility for small and craft producers, raising overall market expansion.
Key Trends and Opportunities
Shift Toward Natural and Clean-Label Formulations
Demand rises for candles made with soy, beeswax, essential oils, and non-toxic ingredients as consumers focus on healthier living. Brands highlight clean-burning properties, cruelty-free sourcing, and sustainability benefits to attract eco-conscious shoppers. This shift encourages broader innovation across wax blends, wicks, and fragrances. Natural candle lines create a strong opportunity for premium positioning, helping manufacturers compete in a crowded market.
- For instance, NEOM Organics markets its Feel Refreshed 1-wick candle with a wax weight of 185 g and an advertised burn time of up to 35 hours, using natural wax and essential oils to address demand for cleaner-burning, naturally formulated scented candles.
Strong Growth in Wellness-Oriented Fragrance Collections
Aromatherapy-inspired candles gain popularity as consumers seek stress relief and emotional balance. Products featuring lavender, eucalyptus, chamomile, and sandalwood attract buyers wanting wellness-linked benefits at home. Retailers promote wellness collections through curated sets and themed launches. This trend opens opportunities for brands to align with spa-inspired experiences and expand into lifestyle gifting, supporting steady segment growth.
- For instance, Jo Malone London states that its fragrance and home-scent range is available in 82 countries and territories, reflecting global distribution of mood-linked candles and room scents positioned around relaxation, comfort, and other wellness-related experiences.
Key Challenges
Rising Raw Material Costs
Price volatility in waxes, fragrance oils, and packaging materials creates pressure on manufacturers, especially smaller brands. Natural waxes such as soy and beeswax experience supply fluctuations, increasing production expenses. These cost swings reduce profit margins and limit premium product affordability for some buyers. Manufacturers adjust strategies by using blended waxes or optimizing sourcing, but cost instability remains a key market hurdle.
Safety and Indoor Air Quality Concerns
Concerns about soot, synthetic fragrances, and emissions challenge consumer trust in conventional scented candles. Awareness of potential indoor air impacts encourages buyers to seek verified clean alternatives, pushing brands to reformulate products. Compliance with safety standards and transparent labeling also becomes more important. These concerns slow growth in lower-quality candles and increase pressure on manufacturers to upgrade formulations.
Regional Analysis
North America
North America leads the scented candles market with about 37% share in 2024. Demand stays strong as consumers buy candles for home décor, wellness routines, and gifting. Retail chains expand fragrance selections, while premium brands gain traction through clean-label and soy-based products. Seasonal launches and high gifting volumes during holidays further support market strength. The U.S. drives most sales due to higher discretionary spending and strong e-commerce penetration. Canada shows steady growth as natural and artisanal candles gain visibility across specialty stores and online platforms.
Europe
Europe holds around 29% share in 2024, supported by strong demand for decorative and premium candles across major markets. Consumers value higher-quality waxes, unique fragrances, and elegant packaging, which boosts uptake of premium and artisanal lines. Sustainability also drives purchasing as buyers shift toward natural wax blends and reusable containers. Germany, France, and the U.K. lead market activity, helped by strong home décor culture and mature retail networks. Seasonal and festive themes remain major sales contributors, strengthening long-term regional growth.
Asia Pacific
Asia Pacific accounts for nearly 22% share in 2024 and shows the fastest growth rate. Rising urban incomes and growing interest in home fragrance boost adoption across China, India, Japan, and South Korea. Consumers increasingly use candles for relaxation, aromatherapy, and home ambiance, expanding demand beyond traditional gifting seasons. Regional manufacturers introduce affordable soy and blended wax options to attract mass buyers. E-commerce expansion helps international brands enter new markets, supporting wider product availability and sustained regional momentum.
Latin America
Latin America captures about 7% share in 2024, driven by rising interest in home décor and wellness-themed products. Brazil and Mexico lead demand as consumers seek affordable scented candles for routine use and festive occasions. Local producers focus on cost-effective paraffin and blended wax candles, while premium imports gain niche traction in urban areas. Growth is supported by expanding retail channels and online marketplaces. Although price sensitivity limits premium expansion, increasing lifestyle spending strengthens long-term market potential.
Middle East and Africa
The Middle East and Africa hold around 5% share in 2024. Demand grows as households and hospitality spaces use scented candles for ambience, luxury appeal, and aromatherapy. Gulf countries, especially the UAE and Saudi Arabia, dominate sales due to higher spending on premium home fragrance items. Local preferences for strong oriental and floral scents also influence product offerings. Africa shows gradual growth as affordable mass-category candles become more accessible. Expanding specialty stores and international brand entry support regional development despite limited penetration in rural areas.
Market Segmentations:
By Product
- Container-based
- Pillar
- Others
By Wax Type
- Paraffin Wax
- Soy Wax
- Blended
- Beeswax
- Palm Wax
By Category
- Mass
- Premium
By Distribution Channel
- Hypermarkets and Supermarkets
- Convenience Stores
- Online Stores
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The scented candles market features leading companies such as NEST New York, Hotel Lobby Candle, L Brands, Diptyque Paris, Lalique Group SA, MVP Group International, Village Candle, Newell Brands, Portmeirion Group PLC, and Thymes. Competition grows as brands focus on cleaner wax blends, safer wicks, and stronger scent performance. Makers invest in new fragrance lines and seasonal themes to increase repeat sales across retail and online channels. Premium labels gain visibility through elegant jars and wellness-driven aromas that appeal to higher-income buyers. Mass producers strengthen reach through wide distribution and value-focused collections. Many firms expand digital marketing programs to raise customer loyalty and speed product trials. Sustainability also shapes competition, with more companies using natural wax, recycled glass, and eco-friendly packaging. Growth depends on how well brands balance cost control, clean ingredients, and new scent ideas while meeting rising global demand.
Key Player Analysis
- NEST New York
- Hotel Lobby Candle
- L Brands
- Diptyque Paris
- Lalique Group SA
- MVP Group International, Inc.
- Village Candle
- Newell Brands
- Portmeirion Group PLC
- Thymes, LLC
Recent Developments
- In 2025, Newell Brands introduced the "YC Collection" under Yankee Candle, emphasizing quiet luxury and modern elegance.
- In 2024, Hotel Lobby Candle announced a strategic partnership with Solage to launch the "Napa Valley Candle," a new product that captures the essence of the region with a unique fragrance profile of black currant and aged oak.
- In 2023, Diptyque introduced a limited-edition refillable candle vessel, a development that emphasized circular economy principles and appealed to environmentally conscious luxury consumers.
Report Coverage
The research report offers an in-depth analysis based on Product, Wax Type, Category, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow as home fragrance use becomes a daily routine.
- Premium candle demand will rise due to interest in natural wax and cleaner scents.
- Brands will expand aromatherapy lines to meet wellness-focused consumer needs.
- Eco-friendly packaging and reusable jars will gain wider adoption.
- E-commerce sales will increase as digital discovery and reviews shape buying habits.
- Personalized and customized fragrance options will attract younger buyers.
- Sustainable wax sourcing will become a priority for major manufacturers.
- Innovative fragrance blends and seasonal themes will support recurring purchases.
- Clean-label and toxin-free candles will gain stronger regulatory and consumer focus.
- Growth in emerging markets will accelerate as lifestyle spending rises.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Home Fragrance Adoption
Consumers increasingly use scented candles to create relaxing home environments, enhance décor, and support aromatherapy routines, leading to higher repeat purchases and broader market penetration.
Growth of Premium and Decorative Candles
Demand for premium candles is rising as buyers seek elegant jars, natural waxes, and sophisticated fragrances, viewing these products as both décor and lifestyle items, which drives higher spending and brand differentiation.
Expanding E-commerce Penetration
Online platforms offer broad fragrance assortments, competitive pricing, and convenient delivery, making it easier for consumers to discover and purchase scented candles, especially among younger and digitally savvy buyers.
Shift Toward Natural and Clean-Label Formulations
Eco-conscious consumers are driving demand for candles made with soy, beeswax, and essential oils, prompting brands to innovate with cleaner, sustainable ingredients and attract premium market segments.
Strong Growth in Wellness-Oriented Fragrance Collections
Aromatherapy-inspired candles featuring scents like lavender and eucalyptus are gaining popularity as consumers seek stress relief and emotional balance, supporting the expansion of wellness-focused product lines.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Scented Candles Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Scented Candles Market projected to grow between 2025 and 2032?
What are the key drivers for the growth of the scented candles market?
What are the primary factors fueling the growth of the Scented Candles Market?
Who are the leading companies in the Scented Candles Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Container-based
- 1.2.2 Pillar
- 1.2.3 Others
- 1.3 By Category
- 1.3.1 Mass
- 1.3.2 Premium
- 1.4 By Wax Type
- 1.4.1 Paraffin Wax
- 1.4.2 Soy Wax
- 1.4.3 Blended
- 1.4.4 Beeswax
- 1.4.5 Palm Wax
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 540 Million → 2032: USD 777.39 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Scented Candles Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Scented Candles Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Scented Candles Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Scented Candles Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Scented Candles Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Scented Candles Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Scented Candles Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Scented Candles Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 540 Million → 2032: USD 777.39 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Scented Candles Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Container-based
- 12.3.7.2 Pillar
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Category - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Mass
- 12.4.7.2 Premium
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Wax Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Paraffin Wax
- 12.5.7.2 Soy Wax
- 12.5.7.3 Blended
- 12.5.7.4 Beeswax
- 12.5.7.5 Palm Wax
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Scented Candles Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Scented Candles Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Scented Candles Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 NEST New York
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Hotel Lobby Candle
- 17.4 L Brands
- 17.5 Diptyque Paris
- 17.6 Lalique Group SA
- 17.7 MVP Group International
- 17.8 Village Candle
- 17.9 Newell Brands
- 17.10 Portmeirion Group PLC
- 17.11 Thymes
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

