
Market Overview:
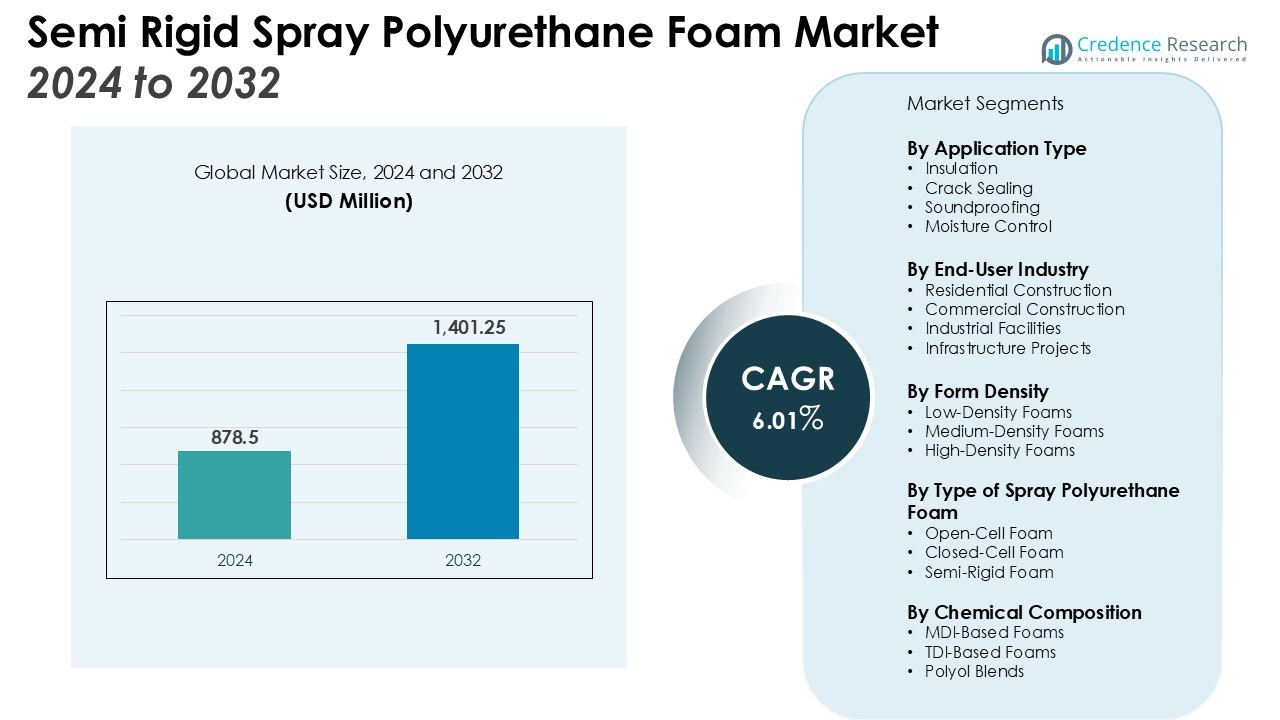
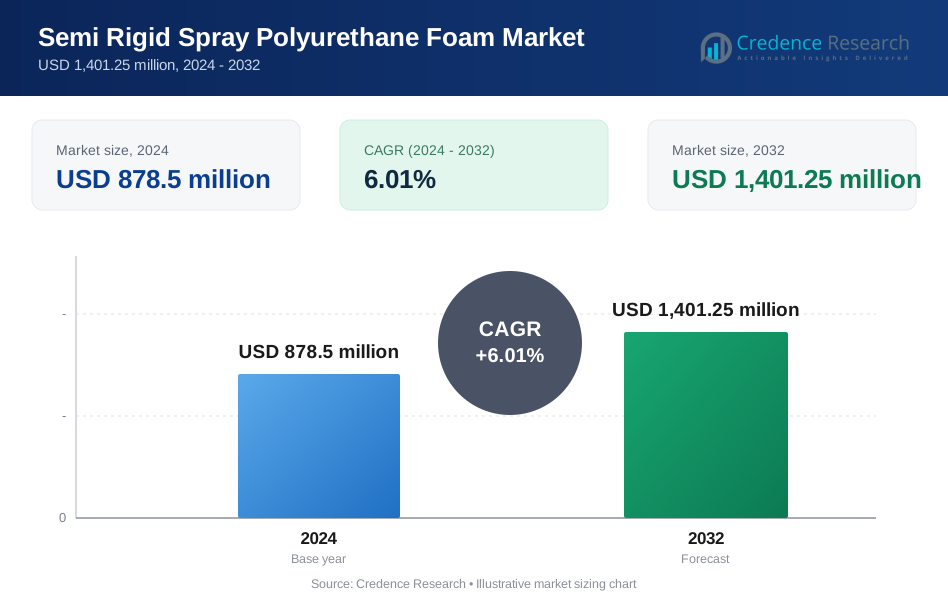
The Semi Rigid Spray Polyurethane Foam Market size was valued at USD 878.5 million in 2024 and is anticipated to reach USD 1,401.25 million by 2032, at a CAGR of 6.01% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Semi Rigid Spray Polyurethane Foam Market Size 2024 | USD 878.5 Million |
| Semi Rigid Spray Polyurethane Foam Market, CAGR | 6.01% |
| Semi Rigid Spray Polyurethane Foam Market Size 2032 | USD 1,401.25 Million |
Rising construction spending and strong demand for insulation and crack sealing are driving the semi-rigid spray polyurethane foam market. The material enhances energy efficiency by sealing air gaps and reducing heat transfer, which helps lower heating and cooling costs. Government initiatives and policies promoting energy-efficient infrastructure, especially across Europe, are further supporting the adoption of this material. Growing awareness of sustainable construction practices is also accelerating product demand in both developed and emerging economies.
Europe commands a significant share of the market, supported by strict energy-efficiency regulations and steady growth in the construction sector. Improved building standards and incentive programs in both commercial and residential segments continue to reinforce the region’s dominance. These factors position Europe as a leading hub for semi-rigid spray polyurethane foam demand and establish a benchmark for market development globally.
Market Insights:
- The Semi Rigid Spray Polyurethane Foam Market was valued at USD 878.5 million in 2024 and is projected to reach USD 1,401.25 million by 2032, at a CAGR of 6.01%.
- Rising construction spending and demand for insulation materials are driving adoption, with foam reducing energy loss and lowering heating and cooling costs.
- Government policies and energy-efficiency programs are accelerating the use of automated foam systems, supported by subsidies and tax incentives.
- Automation enhances application accuracy, reduces waste, and integrates with robotics and IoT, boosting efficiency for large-scale projects.
- North America holds 38% share, benefiting from advanced construction practices, strong regulations, and consumer focus on energy savings.
- Europe commands 30% share, supported by strict energy codes, green building certifications, and incentive programs for sustainable construction.
- Asia Pacific accounts for 22% share, with rapid urbanization, infrastructure investment, and cost-effective manufacturing creating strong growth potential.
Market Drivers:
Rising Demand for Energy-Efficient Insulation in Construction
The Semi Rigid Spray Polyurethane Foam Automation Market is expanding due to strong demand for energy-efficient insulation solutions in residential and commercial buildings. Its ability to reduce energy loss and improve thermal performance makes it a preferred choice among builders and contractors. Stricter government building codes and sustainability regulations further support adoption. Developers are increasingly investing in energy-saving technologies to meet regulatory requirements and reduce operating costs.
- For instance, Johns Manville's Climate Pro® blow-in fiberglass insulation provides a tangible measure of efficiency, with a single bag offering 77.1 square feet of R-30 coverage.
Increasing Government Support and Policy Incentives
Government initiatives promoting sustainable construction are driving adoption of semi-rigid spray polyurethane foam automation systems. Incentives such as subsidies, tax credits, and regulatory frameworks encourage builders to integrate advanced insulation technologies. It helps reduce greenhouse gas emissions and aligns with global climate targets. National and regional energy efficiency programs are influencing market participants to expand their offerings and adopt automated systems.
Technological Advancements and Integration of Automation Solutions
Automation plays a key role in improving the efficiency and consistency of foam application. Automated spray systems ensure uniform coverage, minimize waste, and deliver higher accuracy compared to manual methods. The Semi Rigid Spray Polyurethane Foam Automation Market benefits from the integration of robotics, IoT, and smart monitoring tools. These technologies increase productivity and support large-scale construction projects with minimal errors.
Growing Awareness of Sustainable Construction Practices
The rising focus on sustainable building practices is creating new growth opportunities for the market. Architects and developers are prioritizing insulation solutions that meet environmental standards and reduce long-term energy consumption. Semi-rigid spray polyurethane foam addresses these requirements effectively, making it a core component in modern construction strategies. It continues to gain traction as stakeholders recognize the importance of sustainable materials in achieving long-term performance and compliance goals.
- For instance, Honeywell's Solstice® Liquid Blowing Agent, used for insulation in 3D-printed homes, features a global warming potential (GWP) of 1, demonstrating a significant advancement in sustainable building materials.
Market Trends:
Growing Adoption of Energy-Efficient Building Materials and Sustainable Practices
The Semi Rigid Spray Polyurethane Foam Automation Market is witnessing strong growth due to rising emphasis on energy-efficient construction. The material’s ability to reduce air leakage and improve thermal insulation is gaining preference in both residential and commercial projects. Governments across multiple regions are enforcing stricter building energy codes, which increases the demand for sustainable insulation products. The trend toward green building certifications, such as LEED and BREEAM, also supports adoption. Manufacturers are investing in automated application systems to enhance precision, reduce material waste, and improve consistency in insulation projects. These advancements align with growing awareness of sustainable building practices among developers and consumers.
- For instance, Huntsman Building Solutions' Demilec Heatlok HFO High Lift insulation allows applicators to spray a single pass up to 6.5 inches thick.
Increasing Integration of Automation Technologies to Enhance Efficiency and Productivity
Automation is becoming central to the market, as it reduces reliance on manual application and ensures higher performance standards. Automated spray systems improve the uniformity of foam application, minimizing thermal bridging and enhancing energy savings. It also enables faster project completion, addressing the rising demand for large-scale construction projects worldwide. The integration of IoT-enabled monitoring and smart controls is further advancing the industry, ensuring accurate application thickness and quality control. Manufacturers are prioritizing R&D in robotic spraying solutions to improve operational efficiency and safety at construction sites. This growing focus on automation positions the Semi Rigid Spray Polyurethane Foam Automation Market as a critical enabler of next-generation insulation technologies and sustainable infrastructure growth.
- For instance, Graco’s automated Reactor systems feature advanced ratio assurance technology that constantly recalculates the mix ratio over a small volume of 1000 cubic centimeters.
Market Challenges Analysis:
High Initial Costs and Technical Barriers in Adoption
The Semi Rigid Spray Polyurethane Foam Automation Market faces challenges due to high initial investment and equipment costs. Automated spraying systems require significant capital, which limits adoption among small and medium-sized contractors. It also demands skilled operators to ensure proper calibration, coverage, and quality control. Lack of technical expertise in certain regions delays widespread use of automation solutions. Training requirements for operators further add to overall project expenses. These factors restrain market penetration, particularly in cost-sensitive construction environments.
Environmental Concerns and Regulatory Compliance Issues
Strict environmental regulations related to raw materials and chemical emissions present another challenge for market participants. The Semi Rigid Spray Polyurethane Foam Automation Market must comply with evolving standards that govern volatile organic compound emissions and worker safety. It creates additional costs for manufacturers who must redesign products to meet compliance norms. Uncertainty around regulatory frameworks in different regions complicates long-term planning. Environmental concerns about disposal and recyclability of polyurethane foams also impact perception and acceptance. These hurdles create operational and strategic challenges for stakeholders aiming to scale adoption globally.
Market Opportunities:
Expansion of Green Building Projects and Energy-Efficient Infrastructure
The Semi Rigid Spray Polyurethane Foam Automation Market is positioned to benefit from the rapid expansion of green building initiatives and sustainable infrastructure projects. Governments and developers are prioritizing energy-efficient materials to meet stringent environmental standards. It offers strong potential as the material reduces energy costs while supporting climate-focused goals. Demand for eco-friendly construction solutions in residential, commercial, and industrial sectors continues to accelerate. Rising consumer awareness of sustainable living further boosts opportunities for automated spray systems in insulation applications. These factors create long-term growth prospects across both developed and emerging economies.
Integration of Smart Technologies and Advancements in Automation
Automation trends in the construction industry create significant opportunities for market expansion. The Semi Rigid Spray Polyurethane Foam Automation Market can capitalize on robotics, IoT-enabled monitoring, and precision spraying systems to improve efficiency and consistency. It enhances project timelines while reducing waste and operational costs. Increasing investment in digital construction technologies and smart building systems further amplifies market potential. Collaborations between manufacturers and technology providers will accelerate the development of advanced application tools. These innovations open pathways for stronger adoption across large-scale construction and retrofitting projects worldwide.
Market Segmentation Analysis:
By Application Type
The Semi Rigid Spray Polyurethane Foam Automation Market is segmented by application type, with insulation and crack sealing leading demand. These applications dominate due to rising requirements for energy-efficient solutions in residential and commercial projects. It is also used in soundproofing and moisture control, addressing the needs of advanced building systems. Retrofitting projects focusing on energy performance further drive adoption across this segment.
- For instance, BASF's WALLTITE Max is a closed-cell spray foam that delivers high performance with an R-value of 7.4 per inch, improving the thermal resistance of building envelopes.
By End-User Industry
Construction represents the largest end-user segment, supported by regulatory frameworks mandating energy-efficient buildings. It is applied extensively in residential housing and commercial facilities to reduce energy costs and improve comfort. Industrial users are adopting semi-rigid spray polyurethane foam for facility insulation, reflecting the push toward sustainability in manufacturing operations. Broader application across infrastructure projects further strengthens this segment’s growth.
By Form Density
By form density, medium-density foams are gaining traction due to their balance of insulation performance, durability, and automated application efficiency. Low-density foams continue to see use in residential projects that require flexibility and cost-effectiveness. High-density foams hold importance in commercial and industrial projects where strict performance standards are necessary. This segmentation underlines the versatility of the Semi Rigid Spray Polyurethane Foam Automation Market across varied use cases.
- For instance, Icynene's MD-R-200™ is a medium-density polyurethane spray foam with a nominal density of 2 pounds per cubic foot, offering a tough, high-performance insulation solution.
Segmentations:
By Application Type
- Insulation
- Crack Sealing
- Soundproofing
- Moisture Control
By End-User Industry
- Residential Construction
- Commercial Construction
- Industrial Facilities
- Infrastructure Projects
By Form Density
- Low-Density Foams
- Medium-Density Foams
- High-Density Foams
By Type of Spray Polyurethane Foam
- Open-Cell Foam
- Closed-Cell Foam
- Semi-Rigid Foam
By Chemical Composition
- MDI-Based Foams
- TDI-Based Foams
- Polyol Blends
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Driven by Advanced Construction Practices
North America accounts for 38% share of the Semi Rigid Spray Polyurethane Foam Automation Market, reflecting its strong adoption base. The region benefits from advanced construction practices, strict energy efficiency regulations, and rising demand for sustainable materials. It is further strengthened by high consumer awareness regarding energy savings and indoor comfort. Large-scale commercial and residential projects integrate automated spray systems to enhance performance and precision. Strong investments in technology development and availability of skilled labor reinforce North America’s leadership position in this market.
Europe Supported by Regulatory Frameworks and Sustainability Goals
Europe holds 30% share of the Semi Rigid Spray Polyurethane Foam Automation Market, supported by strict regulatory frameworks and sustainability-driven policies. Governments actively enforce energy codes, encouraging automated polyurethane foam applications across construction projects. It benefits from rising demand in both renovation and new-build sectors. Strong focus on green building certifications and incentive programs further drives product adoption. Consumer preference for eco-friendly solutions and advanced construction practices continues to sustain growth momentum in this region.
Asia Pacific Emerging as a High-Growth Regional Market
Asia Pacific holds 22% share of the Semi Rigid Spray Polyurethane Foam Automation Market, making it one of the fastest-growing regions. Expanding urbanization and infrastructure development in China, India, and Southeast Asia generate strong demand for insulation solutions. It is supported by government investments in energy-efficient housing and industrial projects. Low-cost manufacturing and improving adoption of automated spraying systems enhance regional competitiveness. Strong economic growth and evolving construction standards position Asia Pacific as a key hub for future expansion.
Key Player Analysis:
- Icynene
- BASF Corporation
- Lapolla Industries
- Gaco Western
- Demilec
- Premium Spray Products
- Rhino Linings Corporation
- JJD Urethane
- Honeywell
- NCFI Polyurethanes
Competitive Analysis:
The Semi Rigid Spray Polyurethane Foam Automation Market is characterized by strong competition among global and regional players focusing on innovation, product performance, and compliance with energy-efficiency regulations. Leading companies emphasize research and development to enhance automation technologies, improve spray accuracy, and reduce material waste. It is marked by strategic initiatives such as mergers, acquisitions, and partnerships aimed at expanding product portfolios and geographic reach. Market participants also prioritize sustainable formulations to address environmental concerns and meet regulatory standards. Investment in IoT-enabled spraying systems and robotic solutions further strengthens competitive positioning by offering higher efficiency and consistency. Companies that align their strategies with sustainability goals, cost-effectiveness, and automation efficiency are expected to maintain an edge in this evolving market landscape.
Recent Developments:
- In April 2025, BASF Corporation launched Sokalan® CP 301, a new biodegradable dispersant designed for agricultural products.
- In January 2025, BASF Personal Care business introduced VitaGuard® A, a new encapsulation technology for retinol in cosmetic applications.
- In March 2025, Rust-Oleum launched its Low Odor Premium Spray Paint, which is a water-based formula that reduces odor by 40% when compared to some of its solvent-based paints.
Report Coverage:
The research report offers an in-depth analysis based on Application Type, End-User Industry, Form Density, Type of Spray Polyurethane Foam, Chemical Composition and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for energy-efficient insulation will continue to drive adoption across residential and commercial projects.
- Automation technologies will gain momentum as contractors prioritize precision, reduced waste, and improved productivity.
- Integration of IoT-enabled monitoring systems will enhance quality control and consistency in application processes.
- Government policies supporting sustainable construction will expand opportunities for automated polyurethane foam solutions.
- Growing awareness of climate impact will accelerate the use of eco-friendly insulation materials.
- Emerging economies will experience higher adoption due to rapid urbanization and infrastructure development.
- Investment in R&D will focus on advanced robotic spraying systems to improve safety and efficiency.
- Manufacturers will increasingly collaborate with technology providers to integrate digital tools in automation equipment.
- Renovation and retrofitting projects will provide new growth avenues as aging infrastructure demands energy upgrades.
- Global competition will intensify, with companies focusing on sustainability, innovation, and regional expansion to strengthen market presence.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Semi Rigid Spray Polyurethane Foam Automation, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Semi Rigid Spray Polyurethane Foam Market projected to grow between 2024 and 2032?
Which Semi Rigid Spray Polyurethane Foam Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Semi Rigid Spray Polyurethane Foam Market?
Who are the leading companies in the Semi Rigid Spray Polyurethane Foam Market?
Which region commanded the largest share of the Semi Rigid Spray Polyurethane Foam Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Semi Rigid Spray Polyurethane Foam Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Semi Rigid Spray Polyurethane Foam Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 878.5 million → 2032: USD 1,401.25 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Semi Rigid Spray Polyurethane Foam Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Semi Rigid Spray Polyurethane Foam Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Semi Rigid Spray Polyurethane Foam Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Semi Rigid Spray Polyurethane Foam Market Drivers
- 3.3 Semi Rigid Spray Polyurethane Foam Market Restraints & Challenges
- 3.4 Semi Rigid Spray Polyurethane Foam Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Semi Rigid Spray Polyurethane Foam Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Semi Rigid Spray Polyurethane Foam Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Semi Rigid Spray Polyurethane Foam category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Semi Rigid Spray Polyurethane Foam Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Semi Rigid Spray Polyurethane Foam Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Semi Rigid Spray Polyurethane Foam market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Semi Rigid Spray Polyurethane Foam Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Semi Rigid Spray Polyurethane Foam Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Semi Rigid Spray Polyurethane Foam Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Semi Rigid Spray Polyurethane Foam (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Semi Rigid Spray Polyurethane Foam Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Semi Rigid Spray Polyurethane Foam Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Semi Rigid Spray Polyurethane Foam Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Semi Rigid Spray Polyurethane Foam Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Semi Rigid Spray Polyurethane Foam Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Semi Rigid Spray Polyurethane Foam Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Semi Rigid Spray Polyurethane Foam Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Semi Rigid Spray Polyurethane Foam Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Semi Rigid Spray Polyurethane Foam Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
