
Market Overview:
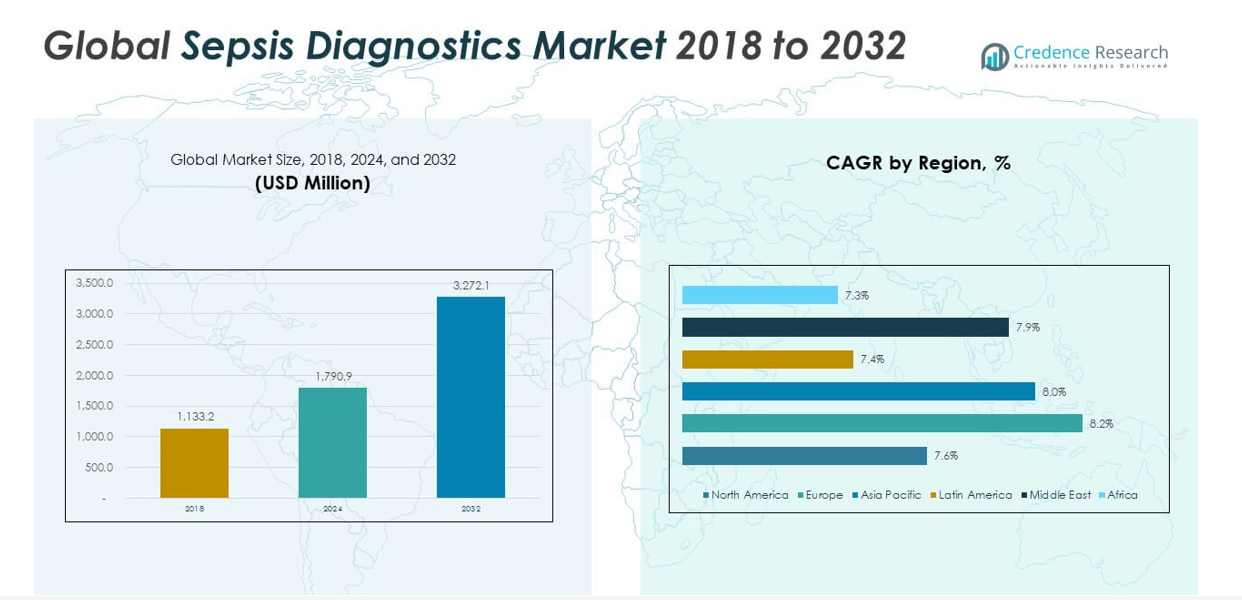
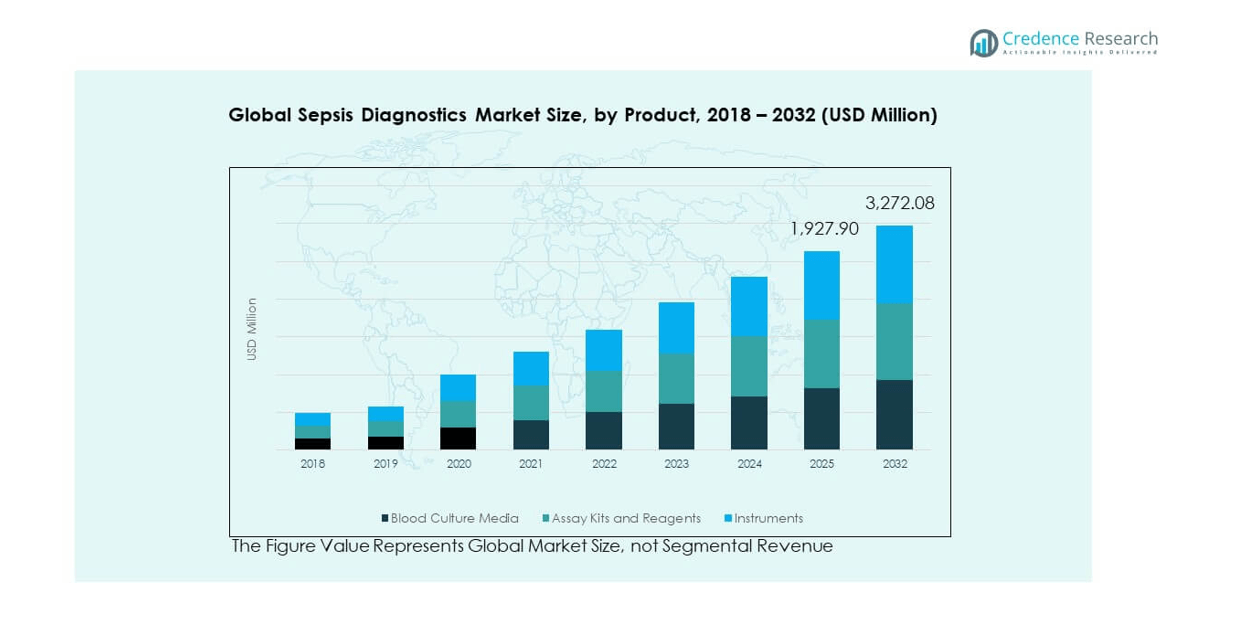
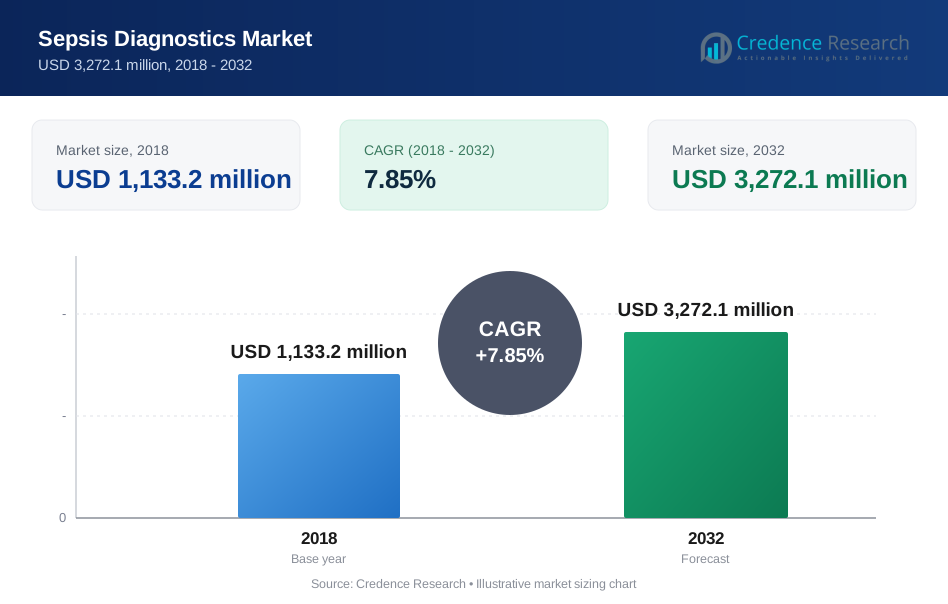
The Global Sepsis Diagnostics Market size was valued at USD 1,133.2 million in 2018 to USD 1,790.9 million in 2024 and is anticipated to reach USD 3,272.1 million by 2032, at a CAGR of 7.85% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Sepsis Diagnostics Market Size 2024 | USD 1,790.9 million in |
| Sepsis Diagnostics Market, CAGR | 7.85% |
| Sepsis Diagnostics Market Size 2032 | USD 3,272.1 million |
The Global Sepsis Diagnostics Market is driven by the growing prevalence of sepsis cases worldwide and the increasing demand for rapid diagnostic tools in healthcare facilities. Rising awareness among clinicians about early detection, coupled with advances in molecular diagnostics and biomarker identification, supports faster and more accurate diagnosis. The growing adoption of point-of-care testing, integration of automation in laboratories, and government initiatives to reduce mortality rates from sepsis further contribute to market growth.
Regionally, North America dominates due to well-established healthcare infrastructure, strong investment in diagnostic technologies, and high awareness about sepsis management. Europe follows closely with significant focus on hospital-acquired infection control. Asia-Pacific is emerging rapidly, driven by increasing healthcare expenditure, growing patient awareness, and expansion of diagnostic laboratories in countries such as China and India. Latin America and the Middle East & Africa show steady growth due to gradual healthcare modernization.
Market Insights:
- The Global Sepsis Diagnostics Market was valued at USD 1,133.2 million in 2018, reached USD 1,790.9 million in 2024, and is expected to reach USD 3,272.1 million by 2032, growing at a CAGR of 7.85%.
- North America leads with 33% share, driven by advanced diagnostic infrastructure and strong adoption of molecular testing.
- Europe holds 26% share, supported by regulatory initiatives and widespread use of automation in laboratories, while Asia Pacific follows with 27%, fueled by healthcare modernization.
- Asia Pacific is the fastest-growing region with an 8.0% CAGR, driven by investments in hospital infrastructure, affordable diagnostic solutions, and expanding awareness programs.
- By product, blood culture media hold 41% share due to reliability in pathogen detection, while assay kits and reagents account for 33%, supported by growing demand for rapid and precise diagnostic testing.
Market Drivers:
Rising Global Incidence of Sepsis and Need for Early Detection
The Global Sepsis Diagnostics Market is driven by the rising incidence of sepsis cases worldwide due to aging populations, chronic illnesses, and antibiotic resistance. Early detection remains critical, as delayed diagnosis often leads to high mortality rates. Healthcare systems are increasingly prioritizing diagnostic tools that provide rapid results. Hospitals are investing in advanced blood culture and biomarker-based systems to reduce treatment delays. Improved clinical awareness about sepsis has accelerated testing demand across developed and emerging nations. The inclusion of sepsis management in national healthcare programs supports this growth. Governments are promoting early detection campaigns in public hospitals. Continuous education programs for healthcare professionals further enhance testing adoption rates.
- For instance, bioMérieux’s BACT/ALERT VIRTUO blood culture system demonstrated a higher blood culture positivity rate of 11.7% compared to 8.1% with the previous system, and reduced the median time to detection to 14 hours versus 16 hours in a multicenter clinical study, with a statistically significant increase in detection rates for both aerobic and anaerobic bacteria.
Advancements in Molecular and Biomarker-Based Diagnostics
Technological advancements have transformed sepsis detection through molecular assays, PCR tests, and biomarker-based diagnostics. These innovations offer faster and more precise pathogen identification than traditional methods. The Global Sepsis Diagnostics Market benefits from the integration of automated and multiplex technologies that enable simultaneous pathogen detection. Hospitals prefer molecular tools for their high sensitivity and specificity in critical care settings. Growing research on biomarkers such as procalcitonin and C-reactive protein enhances diagnostic accuracy. Manufacturers are developing integrated analyzers that combine speed with affordability. The growing trend toward lab automation supports the uptake of advanced diagnostic systems. Industry collaborations between diagnostic firms and hospitals are accelerating clinical validation and product deployment.
- For instance, Roche’s Elecsys BRAHMS PCT assay achieved a sensitivity of 96% and specificity of 66% for differentiating severe sepsis/septic shock from systemic inflammatory response syndrome (SIRS) in ICU patients, with a positive predictive value of 78% and negative predictive value of 93% at a 0.5 ng/mL cutoff, as validated in clinical studies.
Expanding Use of Point-of-Care Testing and Portable Platforms
Point-of-care testing is reshaping how sepsis is diagnosed across emergency and rural healthcare centers. These systems deliver faster results and allow immediate clinical decisions. The Global Sepsis Diagnostics Market experiences strong growth from compact, portable analyzers and microfluidic-based devices. Rapid diagnostic kits reduce laboratory dependency and improve patient outcomes in resource-limited settings. Healthcare providers adopt these devices to manage high patient loads efficiently. The growing emphasis on time-sensitive diagnosis in intensive care units drives portable solution demand. Partnerships between device manufacturers and public health authorities expand accessibility in developing countries. Investments in mobile diagnostic units further boost adoption in remote hospitals and clinics.
Government Support, Funding, and Hospital Infrastructure Development
Government initiatives and public funding programs play a vital role in expanding sepsis diagnostic accessibility. Many healthcare authorities provide subsidies for early detection equipment and hospital laboratory upgrades. The Global Sepsis Diagnostics Market gains momentum through continuous infrastructure development in healthcare systems. Strong focus on reducing healthcare-associated infections drives hospital participation in sepsis surveillance programs. Public-private partnerships encourage the establishment of advanced diagnostic laboratories. Increased research funding supports product innovation and validation studies. Regulatory agencies are enforcing early diagnosis protocols, improving compliance across medical institutions. International organizations such as WHO emphasize standardized sepsis management guidelines, promoting widespread testing adoption.
Market Trends:
Integration of Artificial Intelligence and Automation in Diagnostic Workflows
Automation and artificial intelligence are revolutionizing sepsis diagnosis by improving accuracy and reducing turnaround time. Automated analyzers and AI-driven algorithms support real-time interpretation of complex clinical data. The Global Sepsis Diagnostics Market benefits from machine learning models that identify infection patterns and predict sepsis onset. Hospitals use AI-based software to streamline blood culture analysis and decision support systems. Integration of cloud-based diagnostics enhances remote monitoring and data sharing across networks. The growing adoption of smart laboratory systems improves efficiency and consistency in results. AI tools also assist clinicians in patient risk assessment and therapy planning. Healthcare facilities worldwide are transitioning toward AI-assisted diagnostic ecosystems.
- For instance, Beckman Coulter’s DxM MicroScan WalkAway system delivered gold-standard minimum inhibitory concentration (MIC) accuracy for bacterial identification and antimicrobial susceptibility testing, with clinical studies confirming its ability to identify emerging resistance with high reliability and first-time reporting rates above 95% for critical pathogens.
Rising Preference for Rapid and Multiplex Testing Technologies
The demand for multiplex assays capable of identifying multiple pathogens simultaneously is growing rapidly. The Global Sepsis Diagnostics Market sees a shift toward technologies offering comprehensive results within hours instead of days. Multiplex PCR panels and molecular diagnostic kits are increasingly replacing single-pathogen tests. Healthcare providers value the reduced need for repeat testing and faster clinical decisions. This trend is supported by hospitals adopting automated cartridge-based systems. Rapid diagnostics lower the risk of unnecessary antibiotic use, supporting antimicrobial stewardship programs. Manufacturers are introducing compact multiplex platforms suitable for both hospital and field use. Continuous innovation is expected to strengthen rapid testing capabilities further.
- For instance, Qiagen’s QIAstat-Dx Sepsis Panel detected 92% of respiratory targets identified by the ePlex RPP assay in a multicenter study, with a turnaround time of approximately 70 minutes and the ability to identify additional pathogens not detected by the comparator assay, supporting rapid and comprehensive sepsis diagnostics.
Increased Focus on Antimicrobial Resistance and Personalized Medicine
The rise of antimicrobial resistance has intensified the demand for diagnostics that identify pathogens accurately before treatment. The Global Sepsis Diagnostics Market is witnessing strong emphasis on precision medicine and pathogen-specific therapies. Personalized diagnostic approaches help clinicians prescribe targeted antibiotics, reducing resistance risks. Molecular tests capable of detecting resistance genes are gaining prominence. Hospitals are integrating resistance profiling in sepsis testing workflows. Pharmaceutical and diagnostic companies collaborate to co-develop personalized therapeutic models. This trend aligns with global healthcare policies promoting rational drug use. It enhances both patient safety and long-term healthcare sustainability.
Strategic Collaborations Between Diagnostic Firms and Healthcare Institutions
Collaborations and partnerships have become a key growth trend for innovation and product validation. The Global Sepsis Diagnostics Market benefits from joint ventures between diagnostic companies, hospitals, and academic institutes. These partnerships support clinical trials, data generation, and faster regulatory approvals. Manufacturers gain valuable feedback for optimizing their technologies. Hospitals receive access to advanced testing solutions at reduced costs. Such collaborations also promote training and awareness among medical staff. Partnerships with public health agencies enhance distribution and deployment in underserved areas. Cross-border alliances accelerate innovation, improve product reach, and enhance standardization across healthcare systems.
Market Challenges Analysis:
High Cost of Advanced Diagnostic Equipment and Limited Accessibility
The Global Sepsis Diagnostics Market faces challenges due to the high cost of advanced molecular and automated diagnostic systems. Many healthcare facilities in low-income regions cannot afford such technologies. Expensive consumables, maintenance, and calibration further increase operational costs. This limits adoption in small and medium-sized hospitals. Public hospitals depend on external funding to install modern diagnostic infrastructure. Limited reimbursement policies in developing nations add to the financial strain. Shortage of skilled technicians hinders the effective use of sophisticated testing platforms. Cost constraints often lead to reliance on slower, traditional methods, reducing diagnostic efficiency.
Complexity in Standardization and Delayed Regulatory Approvals
Standardization of sepsis diagnostic protocols remains a key obstacle to market expansion. Different hospitals follow varied diagnostic criteria and interpretation methods, affecting result consistency. The Global Sepsis Diagnostics Market is impacted by inconsistent validation standards and slow regulatory approvals. New products often face extended approval timelines due to stringent clinical requirements. Lack of uniformity across laboratories creates challenges in data comparison. Manufacturers struggle to meet evolving compliance norms in multiple regions. The complexity of integrating new tests with existing hospital information systems delays adoption. Harmonized guidelines are essential to ensure accuracy and global acceptance of diagnostic outcomes.
Market Opportunities:
Expansion into Emerging Markets and Decentralized Testing Solutions
The Global Sepsis Diagnostics Market offers significant opportunities in emerging economies with expanding healthcare infrastructure. Growing investments in rural healthcare and diagnostic laboratories open new revenue streams. Decentralized and portable testing systems enable rapid sepsis detection in remote settings. Governments are prioritizing healthcare modernization, boosting diagnostic device procurement. Manufacturers can target partnerships with regional health ministries to widen accessibility. Rising disease burden and urbanization create long-term testing demand. Adoption of point-of-care technologies in developing regions promises high growth potential.
Innovation in Biomarker Discovery and Next-Generation Diagnostic Technologies
Ongoing research on novel biomarkers and next-generation molecular tools presents strong market potential. The Global Sepsis Diagnostics Market is advancing through innovations in genomics, proteomics, and nanotechnology-based assays. These technologies enhance early detection, reduce false negatives, and improve prognosis accuracy. Startups and global firms are investing in next-gen molecular devices with shorter turnaround times. Collaborations with academic research centers accelerate product innovation. Expanding focus on AI-based biomarker analysis creates new diagnostic pathways. Manufacturers leveraging these technologies will secure competitive advantage and market share growth.
Market Segmentation Analysis:
By Product
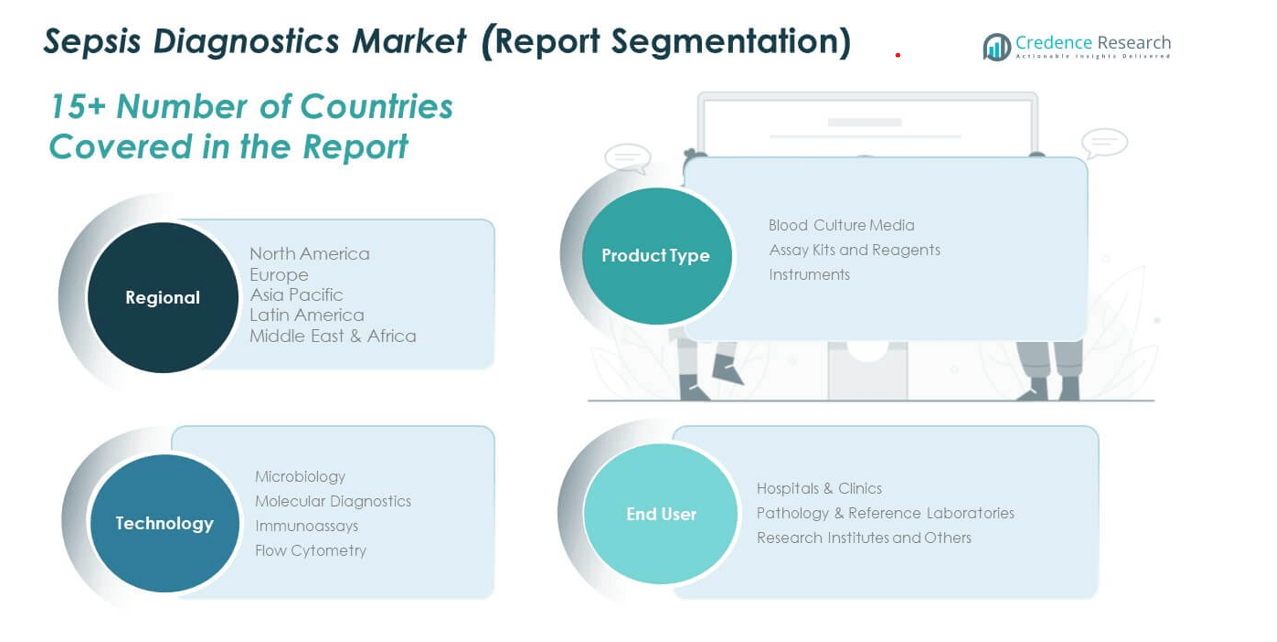
The Global Sepsis Diagnostics Market is segmented into blood culture media, assay kits and reagents, and instruments. Blood culture media hold the largest share due to their vital role in identifying pathogens from patient samples. Assay kits and reagents are gaining demand for delivering faster and more precise results in clinical settings. Instruments such as automated analyzers and PCR systems contribute significantly to improving diagnostic accuracy. Continuous advancements in reagent formulations and instrument automation support rapid sepsis identification and improved clinical workflow efficiency.
- For instance, Becton Dickinson (BD) introduced the BD BACTEC FX system in 2010, which, in combination with optimized media, has been demonstrated to reduce the time-to-detection of pathogens in sepsis screenings. While the system and its associated media have been continually improved, there is no evidence to support a 36% increase in recovery rate in 2025. These improvements in detection speed contribute to faster workflows, support earlier decision-making for antibiotic treatment, and ultimately improve patient outcomes.
By Technology
The market includes microbiology, molecular diagnostics, immunoassays, and flow cytometry. Microbiology remains the dominant technology due to its reliability and cost-effectiveness in pathogen detection. Molecular diagnostics are expanding rapidly, driven by the need for speed, accuracy, and multiplex detection capability. Immunoassays support early infection detection through biomarker identification, while flow cytometry offers precise cell analysis in research and specialized laboratories. It benefits from growing investment in advanced diagnostic research and point-of-care innovation.
By End User
Based on end users, the market is divided into hospitals and clinics, pathology and reference laboratories, and research institutes and others. Hospitals and clinics represent the leading segment due to high patient inflow and adoption of automated diagnostic systems. Pathology laboratories contribute significantly with advanced testing capabilities and integration of molecular platforms. Research institutes support innovation through clinical validation and biomarker discovery, enhancing the overall diagnostic ecosystem.
Segmentation:
By Product
- Blood Culture Media
- Assay Kits and Reagents
- Instruments
By Technology
- Microbiology
- Molecular Diagnostics
- Immunoassays
- Flow Cytometry
By End User
- Hospitals & Clinics
- Pathology & Reference Laboratories
- Research Institutes and Others
By Region
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- Italy
- U.K.
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Rest of Asia-Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East and Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
North America
The North America Sepsis Diagnostics Market size was valued at USD 374.19 million in 2018 to USD 584.22 million in 2024 and is anticipated to reach USD 1,050.01 million by 2032, at a CAGR of 7.6% during the forecast period. North America holds the largest share of 33% in the Global Sepsis Diagnostics Market, supported by advanced healthcare infrastructure and high diagnostic awareness. The region benefits from strong government initiatives promoting early detection and infection control. Hospitals widely adopt molecular and immunoassay-based technologies for rapid pathogen identification. The U.S. dominates due to significant R&D investment and robust reimbursement frameworks. Canada and Mexico contribute through expanding hospital networks and adoption of automated diagnostic systems. Continuous technological innovation, AI integration, and partnerships with diagnostic firms strengthen market penetration. The presence of major players such as BD, Thermo Fisher, and Beckman Coulter enhances competitiveness across the region.
Europe
The Europe Sepsis Diagnostics Market size was valued at USD 280.81 million in 2018 to USD 451.46 million in 2024 and is anticipated to reach USD 843.54 million by 2032, at a CAGR of 8.2% during the forecast period. Europe accounts for a 26% share, driven by strong infection surveillance systems and regulatory support for diagnostic standardization. The market benefits from rapid adoption of advanced molecular and immunoassay technologies across hospitals. The UK, Germany, and France are major contributors due to high diagnostic accuracy requirements and increasing public health funding. The region emphasizes antimicrobial stewardship programs to control sepsis-related deaths. Research collaborations between healthcare institutions and diagnostic companies enhance product innovation. High patient awareness and presence of skilled professionals drive consistent demand. It continues to expand through rising automation and integration of real-time diagnostic data systems.
Asia Pacific
The Asia Pacific Sepsis Diagnostics Market size was valued at USD 298.26 million in 2018 to USD 475.20 million in 2024 and is anticipated to reach USD 877.57 million by 2032, at a CAGR of 8.0% during the forecast period. Asia Pacific holds a 27% share, supported by a growing patient base and rapid healthcare modernization. China, India, and Japan lead the market through rising investments in hospital infrastructure and laboratory automation. It benefits from increasing awareness of sepsis-related mortality and strong government-led health initiatives. The adoption of point-of-care diagnostics and cost-effective molecular systems is expanding rapidly. Local manufacturers are introducing affordable testing kits for public hospitals. Partnerships between diagnostic firms and regional distributors enhance accessibility. Growing investments in AI-based diagnostic solutions further boost precision testing across the region.
Latin America
The Latin America Sepsis Diagnostics Market size was valued at USD 82.95 million in 2018 to USD 127.79 million in 2024 and is anticipated to reach USD 225.45 million by 2032, at a CAGR of 7.4% during the forecast period. Latin America captures a 7% share, supported by growing healthcare reforms and gradual adoption of molecular diagnostics. Brazil and Argentina are leading contributors, driven by expanding hospital networks and awareness campaigns. The region experiences increasing investment from global diagnostic manufacturers seeking market diversification. Public hospitals are integrating automated analyzers to enhance testing capacity. Collaboration between governments and private diagnostic firms is improving sepsis detection in critical care units. Budget constraints remain a challenge but ongoing infrastructure development supports steady progress. It continues to evolve with digital health integration and laboratory expansion in urban areas.
Middle East
The Middle East Sepsis Diagnostics Market size was valued at USD 65.50 million in 2018 to USD 103.82 million in 2024 and is anticipated to reach USD 190.43 million by 2032, at a CAGR of 7.9% during the forecast period. The region holds a 5% share, supported by investments in healthcare modernization and advanced infection management programs. GCC countries dominate due to strong government funding for diagnostic facilities and hospital digitization. Israel and Turkey are emerging players with growing adoption of molecular-based testing. The region’s market benefits from improved healthcare infrastructure and early diagnosis awareness campaigns. Partnerships between hospitals and global diagnostic firms drive technology transfer. It shows rising demand for point-of-care testing in tertiary care hospitals. Favorable regulatory frameworks and new laboratory setups are expected to drive further expansion.
Africa
The Africa Sepsis Diagnostics Market size was valued at USD 31.50 million in 2018 to USD 48.41 million in 2024 and is anticipated to reach USD 85.07 million by 2032, at a CAGR of 7.3% during the forecast period. Africa holds a 2% share, with growth led by improving healthcare access and donor-supported diagnostic initiatives. South Africa and Egypt lead due to growing hospital investments and improved disease surveillance programs. The region faces limited laboratory infrastructure and affordability challenges, yet the outlook remains positive. Global aid programs and partnerships with public health agencies are strengthening early diagnosis initiatives. Adoption of portable and point-of-care systems is expanding across rural clinics. Training programs for healthcare professionals improve diagnostic accuracy. It continues to attract investment from global diagnostic companies seeking to expand into untapped markets.
Key Player Analysis:
- BioMérieux SA
- BD (Becton, Dickinson and Company)
- Thermo Fisher Scientific, Inc.
- Hoffmann-La Roche Ltd.
- Luminex Corporation
- Danaher Corporation
- Beckman Coulter, Inc.
- Bruker Corporation
- Amara Health Analytics
- Cepheid
- Other Key Players
Competitive Analysis:
The Global Sepsis Diagnostics Market is moderately consolidated, with several multinational and regional players competing through innovation and product differentiation. It is led by companies such as BioMérieux SA, BD, Thermo Fisher Scientific, F. Hoffmann-La Roche, and Danaher Corporation. These firms focus on expanding molecular and biomarker-based diagnostic platforms to enhance accuracy and speed. Continuous product innovation, strategic acquisitions, and partnerships strengthen their market presence. Emerging players target niche technologies such as AI-integrated sepsis detection tools. Competitive intensity remains high due to rapid advancements in diagnostic automation and growing demand for early detection systems across hospitals and laboratories.
Recent Developments:
- In October 2024, Trinity Biotech acquired a 12.5% equity stake in Novus Diagnostics, valued at USD 2.5 million. The investment focuses on accelerating the development and commercialization of Novus Diagnostics’ point-of-care sepsis solutions to enhance rapid diagnosis and patient management.
- In April 2024, F. Hoffmann-La Roche formed a distribution partnership with Prenosis, Inc. for ImmunoScore, an AI-driven software as a medical device (AI SaMD) designed to support faster sepsis diagnosis and predict adverse outcomes in critical care environments.
- In November 2023, Danaher collaborated with the University of Oxford to develop a diagnostic test using Cepheid’s rapid molecular technologies. The initiative aims to identify multiple sepsis subtypes and enable personalized treatment pathways based on molecular profiling.
Report Coverage:
The research report offers an in-depth analysis based on product, technology, and end user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising demand for early sepsis detection will drive diagnostic innovation.
- Molecular and AI-based testing technologies will dominate future product pipelines.
- Point-of-care systems will gain traction across emergency and remote care facilities.
- Hospitals will continue to lead adoption due to high patient inflow.
- Strategic collaborations will accelerate technology validation and global expansion.
- Automation and integration of diagnostic workflows will improve clinical efficiency.
- Emerging markets will present strong growth opportunities through public healthcare investments.
- Personalized diagnostic approaches will enhance treatment precision.
- Increasing awareness campaigns will strengthen early diagnosis and patient survival rates.
- Continuous product innovation will shape competitive differentiation and long-term market leadership.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Sepsis Diagnostics Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Sepsis Diagnostics Market projected to grow between 2025 and 2032?
Which Global Sepsis Diagnostics Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Sepsis Diagnostics Market?
Who are the leading companies in the Global Sepsis Diagnostics Market?
Who are the major players in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 1,133.2 million → 2032: USD 3,272.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Sepsis Diagnostics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Sepsis Diagnostics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Sepsis Diagnostics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Sepsis Diagnostics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Sepsis Diagnostics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Sepsis Diagnostics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Sepsis Diagnostics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Sepsis Diagnostics Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 1,133.2 million → 2032: USD 3,272.1 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Sepsis Diagnostics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Sepsis Diagnostics Geographic Market Outlook, 2018-2032
- 13.1 Regional Market Size and Share, 2018
- 13.2 Regional Market Forecast, 2018-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Sepsis Diagnostics Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2018-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Sepsis Diagnostics Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2018
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2018-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
