
Market Overview:
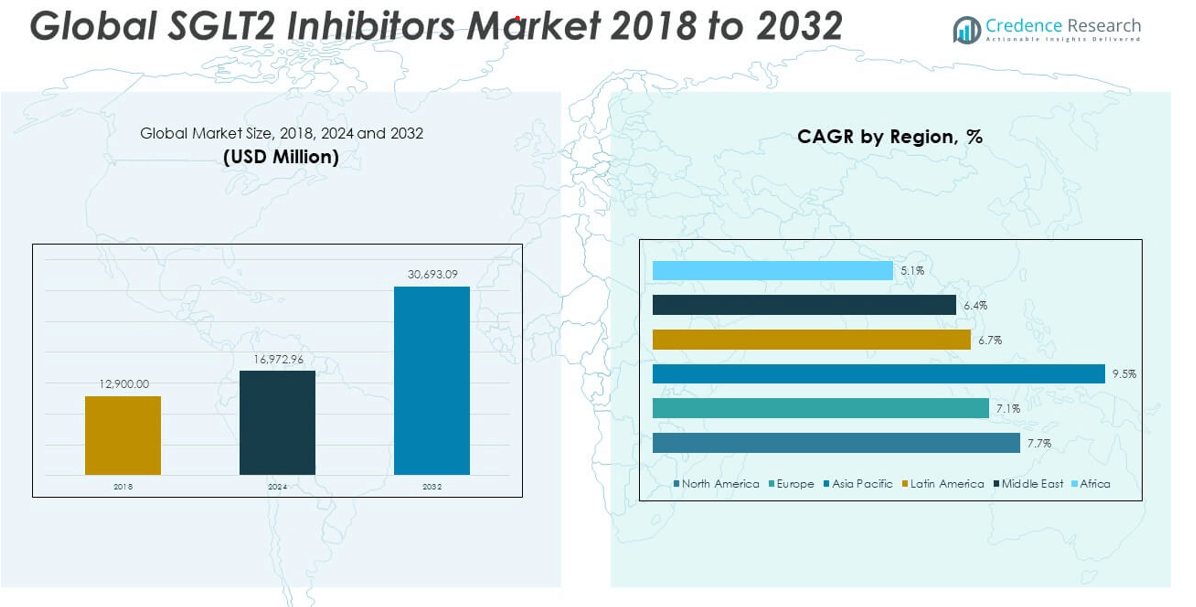
The Global SGLT2 Inhibitors Market size was valued at USD 12,900.00 million in 2018 to USD 16,972.96 million in 2024 and is anticipated to reach USD 30,693.09 million by 2032, at a CAGR of 7.72% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| SGLT2 Inhibitors Market Size 2024 | USD 16,972.96 million |
| SGLT2 Inhibitors Market, CAGR | 7.72% |
| SGLT2 Inhibitors Market Size 2032 | USD 30,693.09 million |
The market is growing due to the rising prevalence of type 2 diabetes and chronic kidney disease, which fuels demand for more effective treatment options. SGLT2 inhibitors offer cardioprotective and renoprotective benefits beyond glycemic control, increasing their clinical adoption. Pharmaceutical companies are expanding R&D efforts to develop next-generation inhibitors with enhanced efficacy and safety profiles. Favorable regulatory approvals and guideline endorsements further encourage early uptake, while improved patient awareness and therapeutic adherence contribute to sustained market expansion.
North America leads the SGLT2 inhibitors market due to a high diabetic population, advanced healthcare infrastructure, and strong presence of major pharmaceutical players. Europe follows, driven by rapid uptake of innovative treatments and supportive reimbursement systems. Asia Pacific is emerging as a high-growth region, owing to rising diabetes incidence, expanding healthcare access, and increased investments in clinical research. Latin America and the Middle East & Africa show gradual adoption due to improving diagnostic rates and growing awareness of disease management.
Market Insights:
- The Global SGLT2 Inhibitors Market was valued at USD 12,900.00 million in 2018, reached USD 16,972.96 million in 2024, and is projected to hit USD 30,693.09 million by 2032, growing at a CAGR of 7.72%.
- Rising incidence of type 2 diabetes and cardiovascular disorders is driving the adoption of SGLT2 inhibitors across global healthcare systems.
- Clinical guidelines and regulatory endorsements are accelerating early-stage prescriptions and cross-specialty usage.
- High treatment costs and limited reimbursement coverage in low-income regions restrict broader market access.
- Risk of adverse effects like genital infections and ketoacidosis deters adoption in vulnerable populations.
- North America dominates due to strong healthcare infrastructure and widespread payer support for innovative therapies.
- Asia Pacific is emerging rapidly, driven by expanding diabetic population, government health initiatives, and improved healthcare access.
Market Drivers:
Rising Global Burden of Diabetes and Cardiovascular Comorbidities Enhancing Adoption Rates:
The rising prevalence of type 2 diabetes and associated cardiovascular complications significantly drives the Global SGLT2 Inhibitors Market. It addresses an increasing patient population requiring effective glucose control and heart failure prevention. Growing rates of obesity and sedentary lifestyles are intensifying demand for novel antidiabetic agents. SGLT2 inhibitors demonstrate benefits beyond glycemic control, including weight loss and reduced cardiovascular risks. These features position them as first-line or add-on therapies. Physicians favor their multifunctional approach in high-risk patients. The shift toward preventive cardiometabolic care accelerates adoption across various healthcare systems. The Global SGLT2 Inhibitors Market gains traction from both endocrinologists and cardiologists.
- For instance, Eli Lilly’s Jardiance (empagliflozin) demonstrated a 14% reduction in major adverse cardiovascular events (3-point MACE) and a 38% reduction in cardiovascular death or hospitalization for heart failure in people with type 2 diabetes in the EMPA-REG OUTCOME trial, illustrating its widespread adoption for cardiometabolic care.
Favorable Regulatory Endorsements and Clinical Guidelines Driving Prescriber Confidence:
Regulatory agencies across the U.S., Europe, and Japan have approved SGLT2 inhibitors for expanded indications, boosting confidence among clinicians. Clinical guidelines by major medical associations endorse SGLT2 inhibitors for patients with heart failure or chronic kidney disease. These endorsements encourage early prescription in newly diagnosed patients. It supports cross-specialty usage beyond endocrinology, especially in nephrology and cardiology. Payer support and reimbursement frameworks evolve to accommodate the broadened clinical utility. Government programs in developed markets actively cover these treatments. These developments reduce barriers to access and increase market penetration. The Global SGLT2 Inhibitors Market benefits from this widespread institutional support.
- For instance, in September 2022, AstraZeneca’s Farxiga (dapagliflozin) received U.S. FDA approval to reduce the risk of cardiovascular death, hospitalization for heart failure, and urgent heart failure visits in adults regardless of diabetes status-supporting broad adoption and enabling its label expansion to cover approximately 6 million U.S. heart failure patients.
Increased R&D and Pipeline Expansion by Major Pharmaceutical Companies:
Pharmaceutical companies are heavily investing in the development of next-generation SGLT2 inhibitors and combination therapies. Innovation efforts target improved safety profiles and expanded use across patient populations. Leading firms explore fixed-dose combinations with DPP-4 inhibitors, GLP-1 agonists, or insulin to improve therapeutic efficacy. These combinations improve patient adherence by reducing pill burden. Companies conduct real-world evidence studies to support long-term safety claims. Such data helps expand their use into new clinical segments. It also enables product differentiation and regulatory approvals across geographies. The Global SGLT2 Inhibitors Market sees increased product launches from both originators and biosimilar developers.
Rising Awareness and Access in Emerging Economies Supporting Market Expansion:
Healthcare systems in emerging economies are expanding diabetes screening and treatment programs. Public-private collaborations enhance awareness of cardiometabolic disorders and promote timely interventions. Pharmaceutical companies partner with local stakeholders to expand their geographic footprint. It helps increase drug availability and affordability across middle-income nations. Governments are building infrastructure for chronic disease management in Asia Pacific, Latin America, and parts of Africa. Market penetration improves as rural and semi-urban populations gain access to branded and generic SGLT2 inhibitors. Digital health campaigns and mobile outreach improve prescription rates. The Global SGLT2 Inhibitors Market benefits from strong momentum in underpenetrated regions.
Market Trends:
Integration of Digital Health Tools Enhancing Therapeutic Monitoring and Outcomes:
The adoption of digital health technologies is transforming treatment monitoring for patients on SGLT2 inhibitors. Wearables, glucose monitors, and digital apps allow real-time tracking of glycemic response. These tools help clinicians adjust treatment plans based on patient-specific data. Pharmaceutical companies collaborate with health tech firms to offer bundled digital solutions. It strengthens adherence and allows early identification of adverse events. Payers show interest in digital integration due to its impact on reducing complications and hospitalizations. Patient-centric care models support technology-enabled drug delivery pathways. The Global SGLT2 Inhibitors Market is aligning with the digital health ecosystem to improve long-term outcomes.
- For instance, Roche launched the mySugr app-integrated with Accu-Chek and capable of syncing with insulin pumps and continuous glucose monitors (CGMs)-enabling over 4 million users to share real-time glycemic data directly with providers; the company’s 2023 Diabetes Care report states that users of the digital ecosystem showed a 1.0% reduction in HbA1c over 6 months. Additionally, Dexcom’s G7 CGM, which is FDA-cleared and used alongside oral therapies including SGLT2 inhibitors, transmits automatically updated glucose trends every 5 minutes to clinicians and patients via secured cloud integration.
Growing Research into Renal and Non-Diabetic Applications of SGLT2 Inhibitors:
Researchers are exploring SGLT2 inhibitors for non-diabetic populations with chronic kidney disease or heart failure. These studies open new use cases for patients without type 2 diabetes. Clinical trials demonstrate significant renal protection and reduced hospitalization rates. It broadens the therapeutic scope and patient eligibility. Regulators have approved SGLT2 inhibitors for heart failure with preserved ejection fraction (HFpEF). New label expansions for renal applications are under review globally. It drives product repositioning and physician outreach across nephrology. The Global SGLT2 Inhibitors Market experiences new growth vectors from non-traditional applications.
- For instance, in the 2022 EMPA-KIDNEY Phase III trial, Boehringer Ingelheim and Eli Lilly’s empagliflozin reduced the risk of kidney disease progression or cardiovascular death by 28% (HR 0.72; 95% CI, 0.64–0.82; p<0.001) in over 6,600 adults with chronic kidney disease, with or without diabetes, as reported in the New England Journal of Medicine and company press releases.
Personalized and Precision Medicine Approaches Shaping Prescribing Patterns:
Precision medicine is influencing treatment plans for type 2 diabetes and heart failure patients. Genetic testing and phenotypic profiling guide the selection of optimal therapies. Clinicians use SGLT2 inhibitors in patient segments with specific comorbid risk profiles. Biomarker-based decision tools identify individuals likely to benefit from SGLT2-based therapies. It reduces trial-and-error approaches and optimizes clinical outcomes. Pharmaceutical companies invest in companion diagnostics for stratified therapy. Academic institutions conduct population-specific trials to refine efficacy data. The Global SGLT2 Inhibitors Market is shifting toward precision-based treatment approaches in response to evolving healthcare models.
Sustainability and Environmental Considerations in Drug Manufacturing and Packaging:
Pharmaceutical companies are focusing on eco-friendly practices in the production of SGLT2 inhibitors. Manufacturers implement green chemistry techniques to reduce waste and emissions. Sustainable packaging and supply chain practices are gaining traction. It aligns with ESG commitments and enhances corporate reputation. Stakeholders increasingly evaluate suppliers based on environmental performance. Healthcare systems prefer drugs produced using compliant and sustainable processes. Companies are disclosing environmental metrics in regulatory filings and investor reports. The Global SGLT2 Inhibitors Market is seeing a parallel trend toward sustainability alongside clinical expansion.
Market Challenges Analysis:
Cost and Reimbursement Barriers Hindering Wider Adoption in Price-Sensitive Regions:
High treatment costs remain a major hurdle in price-sensitive and low-income regions. Many SGLT2 inhibitors are branded and command premium pricing, limiting affordability. Payers in developing markets hesitate to reimburse newer antidiabetic therapies unless strong local data exists. Limited health insurance penetration further compounds out-of-pocket burdens for patients. It restricts sustained usage, especially in chronic disease management. Biosimilar competition is minimal, and regulatory pathways for generic entries are complex. Public health budgets in several countries prioritize essential medicines over innovative agents. The Global SGLT2 Inhibitors Market faces resistance in underfunded healthcare systems despite clinical value.
Adverse Events and Contraindications Restricting Certain Patient Populations:
While SGLT2 inhibitors offer broad benefits, they pose risks in specific patient groups. Genital infections, dehydration, and rare cases of ketoacidosis concern clinicians in older or frail patients. Prescribers remain cautious in patients with fluctuating renal function. Regulatory agencies include boxed warnings and require risk mitigation measures. It affects physician prescribing behavior and patient acceptance. Real-world surveillance data is still emerging, prompting hesitancy in new markets. Safety in pediatric and pregnant populations remains under investigation. The Global SGLT2 Inhibitors Market encounters hurdles in expanding use beyond well-studied adult segments.
Market Opportunities:
Expanding Fixed-Dose Combinations and New Indications to Drive Product Differentiation:
Opportunities lie in developing fixed-dose combinations of SGLT2 inhibitors with other antidiabetic or cardioprotective drugs. These combinations improve adherence and offer superior clinical outcomes. Companies are filing for approvals in new indications such as chronic heart failure or non-diabetic kidney disease. The Global SGLT2 Inhibitors Market can capitalize on evolving clinical guidelines to expand treatment algorithms and drive differentiation.
Emerging Markets and Rural Healthcare Expansion Enabling Broader Market Reach:
Rising access to healthcare in emerging economies offers strong growth potential for manufacturers. Governments are scaling up diabetes management programs and essential drug lists. It allows entry of SGLT2 inhibitors through public procurement and subsidy channels. Manufacturers investing in local partnerships and distribution gain faster rural penetration. It supports the Global SGLT2 Inhibitors Market’s global expansion objectives.
Market Segmentation Analysis:
By Drugs
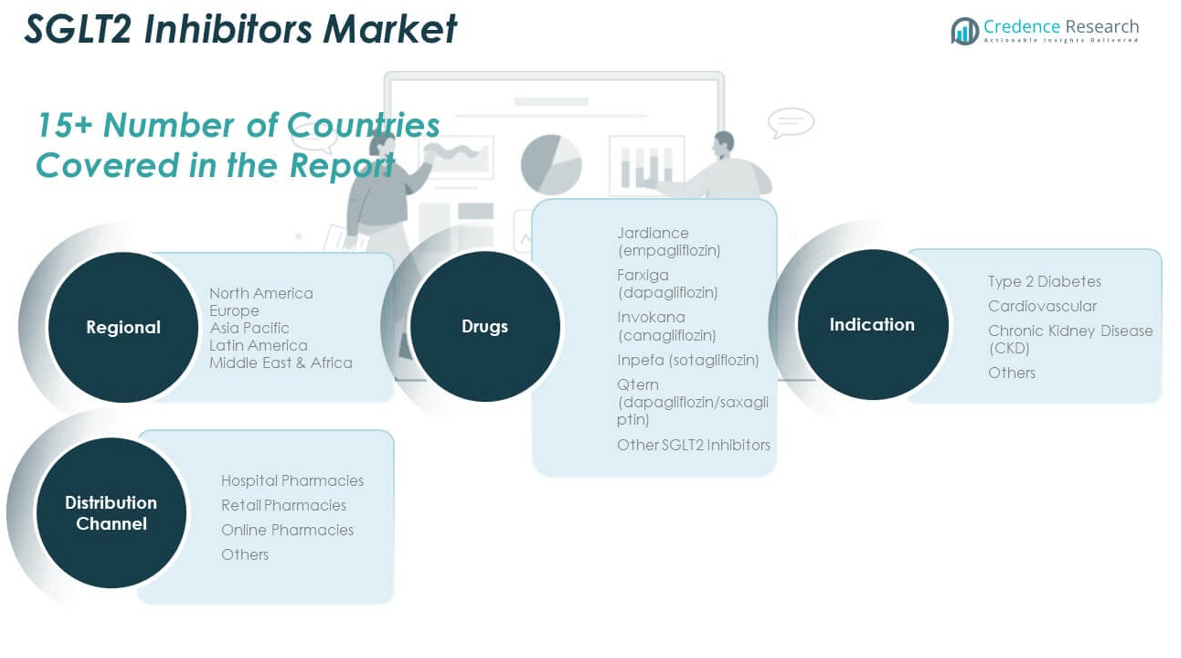
The Global SGLT2 Inhibitors Market, segmented by drug type, is led by Jardiance (empagliflozin), driven by its strong clinical profile and cardioprotective benefits. Farxiga (dapagliflozin) holds a significant share with expanding approvals for heart failure and kidney disease. Invokana (canagliflozin) remains relevant due to its early market entry and supportive outcome trials. Inpefa (sotagliflozin), a dual SGLT1/2 inhibitor, enters the market with potential across multiple indications. Qtern (dapagliflozin/saxagliptin) gains traction as a convenient fixed-dose combination. Other SGLT2 inhibitors contribute to market diversity and cater to regional preferences or niche indications.
- For instance, Jardiance demonstrated a 25% reduction in the risk of cardiovascular death or hospitalization for heart failure in the EMPEROR-Reduced trial (n=3,730), while Farxiga reduced the relative risk of worsening renal function or death from renal or cardiovascular causes by 39% in the DAPA-CKD trial with over 4,000 patients.
By Indication
Type 2 diabetes represents the leading indication, reflecting the global diabetes burden and first-line positioning of SGLT2 inhibitors. Cardiovascular applications are expanding rapidly with increasing physician confidence in using SGLT2 inhibitors for heart failure management. Chronic Kidney Disease (CKD) is gaining prominence, supported by trials confirming slowed renal progression. The "Others" segment includes emerging indications, such as pre-diabetes or metabolic syndrome, where research is ongoing and future expansion is anticipated.
- For instance, Invokana (canagliflozin) was shown in the CREDENCE trial to lower the risk of end-stage kidney disease or renal/cardiovascular death by 30% in patients with diabetic nephropathy, highlighting its robust role in diabetic and renal indications.
By Distribution Channel
Hospital pharmacies dominate the distribution landscape due to the complex nature of treatment and specialist-driven prescriptions. Retail pharmacies play a key role in ongoing therapy for stable patients in outpatient settings. Online pharmacies are gaining momentum, especially in urban areas, as digital health adoption rises and convenience influences purchasing behavior. Other distribution channels, including institutional and government supply programs, support access in underserved or rural regions, especially in emerging economies. It reflects a balanced mix of traditional and modern channels supporting the Global SGLT2 Inhibitors Market.
Segmentation:
By Drugs
- Jardiance (empagliflozin)
- Farxiga (dapagliflozin)
- Invokana (canagliflozin)
- Inpefa (sotagliflozin)
- Terns (dapagliflozin/saxagliptin)
- Other SGLT2 Inhibitors
By Indication
- Type 2 Diabetes
- Cardiovascular
- Chronic Kidney Disease (CKD)
- Others
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America SGLT2 Inhibitors Market size was valued at USD 5,232.24 million in 2018 to USD 6,809.45 million in 2024 and is anticipated to reach USD 12,298.77 million by 2032, at a CAGR of 7.7% during the forecast period. North America accounts for approximately 40% of the Global SGLT2 Inhibitors Market share. It leads due to strong healthcare infrastructure, high prevalence of type 2 diabetes, and early adoption of innovative therapies. The U.S. drives the majority of regional demand, supported by favorable reimbursement policies and rapid uptake of SGLT2 inhibitors for cardiovascular and renal indications. Regulatory approvals and updated clinical guidelines encourage physician confidence. Key pharmaceutical players operate from this region and maintain aggressive R&D pipelines. Hospital systems and retail chains actively stock branded formulations, improving access and adherence. Digital health platforms and prescription monitoring further strengthen market penetration across urban and suburban areas.
Europe
The Europe SGLT2 Inhibitors Market size was valued at USD 3,885.48 million in 2018 to USD 4,938.67 million in 2024 and is anticipated to reach USD 8,500.53 million by 2032, at a CAGR of 7.1% during the forecast period. Europe holds nearly 28% share of the Global SGLT2 Inhibitors Market. The market benefits from robust public healthcare systems and widespread clinical adoption across major economies including Germany, the UK, and France. European Medicines Agency approvals for expanded indications accelerate product availability. Cardiologists and nephrologists increasingly prescribe SGLT2 inhibitors for heart failure and CKD. Government focus on chronic disease management supports long-term use in high-risk populations. Regional pricing negotiations influence market dynamics but maintain affordability in most cases. Local manufacturers and distributors collaborate with global brands to optimize supply chains. Clinical trials across the region also enhance prescriber trust and broaden application scope.
Asia Pacific
The Asia Pacific SGLT2 Inhibitors Market size was valued at USD 2,244.60 million in 2018 to USD 3,137.38 million in 2024 and is anticipated to reach USD 6,485.47 million by 2032, at a CAGR of 9.5% during the forecast period. Asia Pacific represents approximately 21% of the Global SGLT2 Inhibitors Market. Rapid urbanization, rising diabetes prevalence, and expanding middle-class populations fuel demand across countries like China, India, and Japan. Governments in the region are investing in diabetes screening and early intervention programs. Pharmaceutical companies expand their footprint through strategic partnerships and local manufacturing. Public and private insurance schemes increasingly cover innovative antidiabetic drugs. Retail pharmacies and online platforms improve last-mile access in urban centers. Growing physician awareness and regional clinical trials support safe prescribing. Asia Pacific is emerging as a high-growth region with long-term market potential.
Latin America
The Latin America SGLT2 Inhibitors Market size was valued at USD 786.90 million in 2018 to USD 1,025.00 million in 2024 and is anticipated to reach USD 1,714.82 million by 2032, at a CAGR of 6.7% during the forecast period. Latin America accounts for around 6% of the Global SGLT2 Inhibitors Market share. Brazil and Mexico lead regional demand, supported by rising diabetes burden and expanding healthcare infrastructure. Market growth is supported by improved regulatory frameworks and the introduction of branded therapies. Distribution networks are expanding to reach underserved areas. Economic constraints and limited insurance coverage restrict broader access in lower-income segments. Efforts to integrate SGLT2 inhibitors into national formularies are gaining momentum. Healthcare providers gradually adopt these agents for dual glycemic and cardiovascular benefits. E-commerce and pharmacy chains help increase product visibility and reach.
Middle East
The Middle East SGLT2 Inhibitors Market size was valued at USD 501.81 million in 2018 to USD 619.40 million in 2024 and is anticipated to reach USD 1,013.04 million by 2032, at a CAGR of 6.4% during the forecast period. The region holds close to 3% of the Global SGLT2 Inhibitors Market. Gulf Cooperation Council (GCC) countries such as Saudi Arabia and the UAE dominate the regional landscape. High diabetes prevalence, rising obesity rates, and government-led health reforms support demand. Public healthcare systems actively adopt newer therapies in tertiary care centers. Market access remains strong in urban regions, with private hospitals driving much of the volume. Local partnerships and in-country manufacturing reduce dependency on imports. Awareness campaigns improve early diagnosis and medication uptake. The Middle East continues to build its therapeutic capacity across chronic disease management.
Africa
The Africa SGLT2 Inhibitors Market size was valued at USD 248.97 million in 2018 to USD 443.06 million in 2024 and is anticipated to reach USD 680.44 million by 2032, at a CAGR of 5.1% during the forecast period. Africa represents approximately 2% of the Global SGLT2 Inhibitors Market share. The region faces challenges such as low diagnosis rates, limited specialist care, and affordability issues. South Africa and Egypt lead market development with growing access to branded therapies. International aid programs and partnerships play a role in expanding essential medicine access. Awareness around SGLT2 inhibitors is improving among healthcare providers. Supply chain inefficiencies and out-of-pocket costs limit adoption in rural areas. Efforts to scale chronic care infrastructure are underway across major cities. Africa shows gradual progress in expanding access to advanced diabetes management therapies.
Key Player Analysis:
- Boehringer Ingelheim International GmbH
- AstraZeneca
- Merck & Co., Inc.
- Johnson & Johnson Services, Inc. (Janssen Pharmaceuticals, Inc.)
- TheracosBio, LLC
- Lexicon Pharmaceuticals, Inc.
- Eli Lilly and Company
- Bristol-Myers Squibb Company
- Glenmark Pharmaceuticals Ltd.
Competitive Analysis:
The Global SGLT2 Inhibitors Market features a highly competitive landscape dominated by a few multinational pharmaceutical companies with extensive R&D capabilities. Key players include Boehringer Ingelheim, AstraZeneca, Johnson & Johnson (Janssen), Eli Lilly, and Merck & Co. These companies lead with strong product portfolios, including Jardiance, Farxiga, and Invokana, supported by continuous clinical research and global regulatory approvals. It witnesses high product differentiation based on efficacy, safety profiles, and expanding indications in cardiovascular and renal conditions. Companies invest in lifecycle management strategies and fixed-dose combinations to retain market share. Collaborations and co-marketing agreements further consolidate competitive positioning. Emerging firms and generics manufacturers are gradually entering the market but face regulatory and innovation barriers. The Global SGLT2 Inhibitors Market maintains moderate-to-high entry barriers due to intellectual property protections and strict safety standards.
Recent Developments:
- In July 2025, Boehringer Ingelheim reported strong global growth with Jardiance® (empagliflozin)-a leading SGLT2 inhibitor-generating €4.3billion in sales during the first half of the year. The company also advanced several late-stage therapies for kidney and metabolic health, underscoring ongoing innovation within its cardio-renal-metabolic portfolio.
- In March 2025, AstraZeneca’s Farxiga® (dapagliflozin) was highlighted in the landmark DapaTAVI trial, showing the SGLT2 inhibitor to be safe and effective in reducing death and worsening heart failure in older adults undergoing transcatheter aortic valve replacement. This represents expanded research and clinical utility for Farxiga beyond standard diabetes indications.
- In July 2025, Merck & Co. completed the acquisition of SpringWorks Therapeutics for $3.4billion. The deal included two FDA-approved therapies for rare tumors, reflecting Merck’s effort to broaden its specialty medicines portfolio, though not specifically SGLT2-related. In addition, in July 2025 Merck announced the acquisition of Verona Pharma, bringing the first-in-class COPD therapy Ohtuvayre® into its cardio-pulmonary pipeline.
- In March 2023, TheracosBio received FDA approval for Brenzavvy™ (bexagliflozin), a new oral SGLT2 inhibitor for type 2 diabetes. This milestone followed a multi-year integrated manufacturing partnership with Piramal Pharma Solutions, facilitating Brenzavvy’s regulatory and commercial development.
Market Concentration & Characteristics:
The Global SGLT2 Inhibitors Market is moderately concentrated, with a few key players holding significant revenue share due to their first-to-market advantage and broad regulatory approvals. It is characterized by high innovation, continuous clinical trial activity, and growing emphasis on combination therapies. The market is shaped by patent-protected drugs, with limited biosimilar competition to date. It sees steady demand from both endocrinology and cardiology sectors, with increasing crossover in therapeutic applications. High brand loyalty, safety benchmarks, and real-world evidence further strengthen incumbent positions in the market.
Report Coverage:
The research report offers an in-depth analysis based on Drugs, Indication, and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand will rise with expanding indications across cardiovascular and renal disease management.
- Ongoing R&D will lead to new drug formulations and improved fixed-dose combinations.
- Emerging markets will experience faster growth due to rising diabetes prevalence and healthcare access.
- Real-world evidence and long-term safety data will boost prescriber and patient confidence.
- Digital health integration will support therapy adherence and enhance treatment outcomes.
- Market share will shift toward combination therapies tailored for complex patient profiles.
- Regulatory approvals in non-diabetic populations will create new revenue streams.
- Pricing pressure and patent expirations may lead to biosimilar development and market entry.
- Online and retail pharmacy growth will enhance product accessibility, especially in urban areas.
- Strategic collaborations and regional partnerships will accelerate global market expansion.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Burden of Diabetes and Cardiovascular Comorbidities
The increasing prevalence of type 2 diabetes and associated cardiovascular complications is driving demand for SGLT2 inhibitors, as these drugs offer both glycemic control and cardioprotective benefits, making them attractive for high-risk patient populations.
Favorable Regulatory Endorsements and Clinical Guidelines
Expanded regulatory approvals and endorsements from major clinical guidelines for SGLT2 inhibitors in heart failure and chronic kidney disease are boosting prescriber confidence and accelerating early-stage prescriptions across multiple specialties.
Increased R&D and Pipeline Expansion
Major pharmaceutical companies are investing heavily in developing next-generation SGLT2 inhibitors and combination therapies, leading to a broader range of indications, improved safety profiles, and increased product launches that fuel market growth.
Rising Awareness and Access in Emerging Economies
Healthcare initiatives, public-private partnerships, and improved infrastructure in emerging markets are expanding access to SGLT2 inhibitors, increasing diagnosis rates, and supporting market penetration in previously underserved regions.
Integration of Digital Health Tools
The adoption of digital health technologies, such as glucose monitoring apps and wearables, is enhancing therapeutic monitoring and adherence for patients on SGLT2 inhibitors, leading to better outcomes and supporting sustained market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global SGLT2 Inhibitors Market?
What factors are driving the growth of the Global SGLT2 Inhibitors Market?
What are the key segments within the Global SGLT2 Inhibitors Market?
Who are the major players in the Global SGLT2 Inhibitors Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drugs
- 1.2.1 Jardiance (empagliflozin)
- 1.2.2 Farxiga (dapagliflozin)
- 1.2.3 Invokana (canagliflozin)
- 1.2.4 Inpefa (sotagliflozin)
- 1.2.5 Qtern (dapagliflozin/saxagliptin)
- 1.2.6 Other SGLT2 Inhibitors
- 1.3 By Indication
- 1.3.1 Type 2 Diabetes
- 1.3.2 Cardiovascular
- 1.3.3 Chronic Kidney Disease (CKD)
- 1.3.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 12,900.00 million → 2032: USD 30,693.09 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global SGLT2 Inhibitors Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global SGLT2 Inhibitors Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global SGLT2 Inhibitors Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global SGLT2 Inhibitors Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global SGLT2 Inhibitors Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global SGLT2 Inhibitors Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global SGLT2 Inhibitors Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global SGLT2 Inhibitors Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 12,900.00 million → 2032: USD 30,693.09 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global SGLT2 Inhibitors Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drugs - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Jardiance (empagliflozin)
- 12.3.7.2 Farxiga (dapagliflozin)
- 12.3.7.3 Invokana (canagliflozin)
- 12.3.7.4 Inpefa (sotagliflozin)
- 12.3.7.5 Qtern (dapagliflozin/saxagliptin)
- 12.3.7.6 Other SGLT2 Inhibitors
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Indication - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Type 2 Diabetes
- 12.4.7.2 Cardiovascular
- 12.4.7.3 Chronic Kidney Disease (CKD)
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global SGLT2 Inhibitors Geographic Market Outlook, 2018-2032
- 13.1 Regional Market Size and Share, 2018
- 13.2 Regional Market Forecast, 2018-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global SGLT2 Inhibitors Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2018-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global SGLT2 Inhibitors Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2018
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2018-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Boehringer Ingelheim International GmbH
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 AstraZeneca
- 17.4 Merck & Co., Inc.
- 17.5 Johnson & Johnson Services, Inc. (Janssen Pharmaceuticals, Inc.)
- 17.6 TheracosBio, LLC
- 17.7 Lexicon Pharmaceuticals, Inc.
- 17.8 Eli Lilly and Company
- 17.9 Bristol-Myers Squibb Company
- 17.10 Glenmark Pharmaceuticals Ltd.
- 17.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

