
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Shipbuilding Market Size 2024 | USD 161,702.69 Million |
| Shipbuilding Market, CAGR | 4.10% |
| Shipbuilding Market Size 2032 | USD 223,009.36 Million |
Market Overview
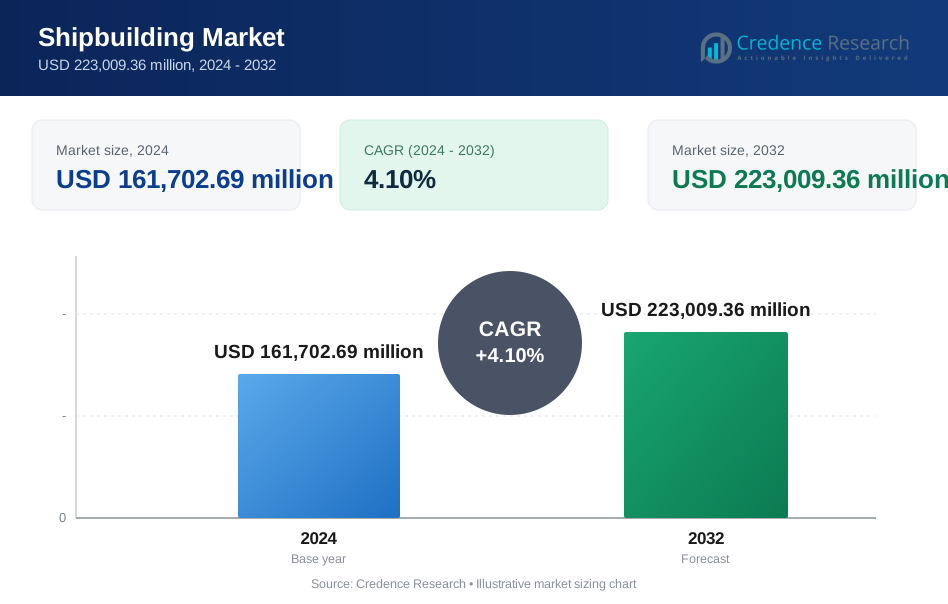
The Shipbuilding Market is projected to grow from USD 161,702.69 million in 2024 to USD 223,009.36 million by 2032, reflecting a compound annual growth rate (CAGR) of 4.10%.
The Shipbuilding Market is driven by rising global trade, increasing demand for new and advanced vessels, and growing investments in maritime infrastructure. Key trends include the adoption of eco-friendly ship technologies and the shift towards automation and digitalization in shipbuilding processes, which enhance efficiency and reduce operational costs. Additionally, regulatory pressures for reducing emissions are pushing shipbuilders to develop energy-efficient and sustainable vessels. The growing demand for specialized ships, such as LNG carriers and offshore support vessels, also contributes to the market’s expansion, positioning it for steady growth in the coming years.
The Shipbuilding Market is dominated by the Asia Pacific region, particularly countries like China, South Korea, and Japan, which together hold over 40% of the market share due to their advanced shipyards and strong government support. Europe also plays a key role, with around 20% market share, driven by high-value ship production, such as luxury cruise liners and naval vessels. Key players in the global market include Hyundai Heavy Industries, Samsung Heavy Industries, Daewoo Shipbuilding and Marine Engineering, TSUNEISHI SHIPBUILDING Co. Ltd., and Mitsubishi Heavy Industry, known for their expertise and innovation in shipbuilding.
Market Drivers
Increasing Global Trade and Expanding Maritime Tourism
The rise of globalization has significantly increased the demand for efficient maritime transportation, with international trade surging due to the interconnectedness of global economies. For instance, the World Trade Organization (WTO) reports that global trade has grown remarkably over the last century, with exports today being more than 40 times larger than in 1913. Emerging markets, particularly in developing nations, are experiencing rapid industrialization, leading to a higher demand for raw materials and goods transported by sea. This growth in maritime activity is also reflected in the expansion of maritime tourism, driven by rising disposable incomes. As individuals have more financial freedom, the appeal of luxury cruises and unique travel experiences by sea continues to grow, fueling demand for passenger vessels and driving the need for shipbuilding advancements to meet these new leisure trends.
Infrastructure Development and Improved Connectivity
Ongoing investments in maritime infrastructure are crucial to supporting the growing volume of maritime trade and tourism. For instance, the U.S. Department of Transportation’s Maritime Administration (MARAD) announced over $653 million to fund 41 port improvement projects across the nation under the Port Infrastructure Development Program (PIDP) to improve the safety, efficiency, and reliability of the movement of goods. The expansion of ports and terminals is necessary to accommodate larger vessels and increased shipping traffic. Improved connectivity through infrastructure upgrades, such as dredging, construction of new ports, and the implementation of advanced navigational aids, ensures safer and more efficient maritime operations. These developments not only enhance the capacity of maritime networks but also strengthen global trade routes, enabling the shipbuilding market to thrive as demand for more efficient and modern vessels continues to rise.
Technological Advancements and Military Modernization
Technological innovations are a key driver of the shipbuilding market, with improvements in vessel efficiency and sustainability taking center stage. Advanced propulsion systems, hull designs, and eco-friendly materials are contributing to the creation of fuel-efficient ships that meet growing environmental concerns. Additionally, the increasing use of automation and digital technologies, such as autonomous ships and digital twin models, is streamlining shipbuilding processes, reducing operational costs, and enhancing overall productivity. Meanwhile, geopolitical tensions are pushing countries to modernize their naval fleets, investing in advanced military vessels like aircraft carriers and submarines to ensure technological superiority and national security, further driving the demand in the shipbuilding sector.
Environmental Regulations and Demand for Cleaner Technologies
The tightening of environmental regulations is another major factor influencing the shipbuilding market. Governments worldwide are imposing stricter emissions standards, compelling shipbuilders to develop vessels with cleaner propulsion systems, such as those powered by LNG (liquified natural gas) or hybrid technologies. This shift towards environmentally sustainable shipping is not only a regulatory requirement but also a response to the growing global demand for greener technologies. As a result, the shipbuilding industry is adapting to create energy-efficient vessels that meet both regulatory standards and the expectations of environmentally conscious customers.
Market Trends
Larger Vessel Sizes and Environmental Sustainability
The shipbuilding market is witnessing a growing demand for larger vessels, such as ultra-large container ships and very large crude carriers (VLCCs), driven by the need to enhance cargo capacity and transport goods more efficiently. These vessels offer economies of scale, reducing operating costs per unit of cargo, which makes them particularly appealing to shipping companies focused on cost-effectiveness. As global trade continues to grow, larger ships play a crucial role in meeting increased shipping demands while simultaneously optimizing fuel consumption and operational costs. For instance, a recent survey by the International Maritime Organization (IMO) highlighted that the adoption of larger vessels has led to a significant reduction in fuel consumption per ton-mile, contributing to lower greenhouse gas emissions. In parallel, the focus on environmental sustainability is transforming ship designs and propulsion technologies. Shipbuilders are increasingly integrating cleaner propulsion options, such as LNG (liquified natural gas), hybrid power systems, and fuel cells, to meet stricter environmental regulations aimed at reducing greenhouse gas emissions. Energy-efficient ship designs, including advanced hull optimizations and renewable energy sources, are further contributing to the reduction of ships' environmental footprints, aligning with global sustainability goals and improving overall vessel performance.
Automation, Digitalization, and Modular Construction
The rise of automation and digitalization is another significant trend reshaping the shipbuilding market. The development of autonomous ships, powered by artificial intelligence and advanced navigation technologies, promises to revolutionize maritime operations by enhancing safety, efficiency, and reducing the need for human intervention in hazardous environments. Digital twin technology is also playing a key role, allowing shipbuilders to create virtual replicas of ships to optimize design, predict maintenance needs, and enhance operational efficiencies throughout a vessel’s lifecycle. Moreover, the adoption of modular construction techniques is gaining momentum as shipbuilders seek to reduce construction time and costs. By prefabricating ship sections separately and assembling them at shipyards, manufacturers can achieve greater flexibility and standardization in ship design. This approach not only speeds up the building process but also enables shipbuilders to respond more quickly to market demands and customization needs. Together, these trends signal a shift towards more efficient, flexible, and technologically advanced shipbuilding processes, allowing the industry to adapt to modern challenges while maintaining competitiveness in an increasingly complex global market.
Market Challenges Analysis
Overcapacity, Fluctuating Demand, and Rising Costs
The shipbuilding industry faces significant challenges related to overcapacity, where excess shipbuilding capacity has created an intensely competitive environment. As a result, prices for new vessels have been driven down, reducing profitability for shipbuilders and shipping companies alike. This overcapacity strains the financial health of the industry, forcing companies to operate with thinner margins while still managing rising operational costs. Fluctuating demand further complicates the market, with ship orders highly dependent on economic cycles. For instance, the Organisation for Economic Co-operation and Development (OECD) has considered adjusting the shipbuilding capacity to reduce the imbalance based on the demand forecast. During downturns, reduced shipping activity leads to lower demand for new vessels, exacerbating the overcapacity issue. Geopolitical events and trade tensions introduce additional uncertainty, making it difficult for shipbuilders to predict future demand and plan their production accordingly. Moreover, the rising costs of fuel present an ongoing challenge, as higher fuel prices increase operating expenses for shipping companies, which in turn reduces their ability to invest in new vessels. To mitigate this, the industry is focusing on developing fuel-efficient ships, but these solutions take time and capital to implement effectively.
Environmental Regulations, Technological Disruption, and Labor Shortages
Stricter environmental regulations have also placed pressure on the shipbuilding industry, requiring significant investments in cleaner technologies and the retrofitting of existing vessels to meet emissions standards. Compliance with these regulations can be costly and technologically complex, as shipbuilders must develop and integrate advanced propulsion systems and cleaner energy solutions. In parallel, technological disruption in the form of autonomous ships and digitalization is rapidly changing the industry’s landscape. While these advancements promise greater efficiency, they also introduce uncertainties around job displacement and the need for shipbuilders to continually adapt to new technologies to stay competitive. Labor shortages further compound these challenges, with a critical shortage of skilled workers, particularly in engineering and ship construction. Attracting and retaining qualified talent has become essential for the long-term viability of the shipbuilding industry, as the sector must bridge skill gaps to keep pace with technological advancements and regulatory demands. Without sufficient talent, the industry risks falling behind in innovation and productivity.
Market Segmentation Analysis:
By Type:
The Shipbuilding Market is segmented by various ship types, each catering to specific needs within the maritime industry. Cruise ships represent a significant portion of the market, driven by growing demand for leisure and tourism activities. Cargo ships, including container vessels and bulk carriers, form the backbone of global trade, transporting large quantities of goods and materials across international waters. Military vessels, such as aircraft carriers and submarines, are crucial for national security, with governments investing in modernizing their fleets. Tugs, fishing vessels, and bunker tankers also play essential roles in supporting maritime operations, while small passenger ships and general cargo carriers serve regional and local transportation needs. Each ship type is designed with specific technical requirements, contributing to the overall diversity and growth of the shipbuilding market.
By End-User:
The Shipbuilding Market is further divided by end-users, primarily into the transport and military sectors. The transport segment dominates the market, driven by the global expansion of maritime trade and the increasing demand for efficient, large-capacity vessels to meet the growing needs of commerce. The military sector, however, plays a critical role in the market as countries invest heavily in naval fleets to ensure national security and geopolitical influence. Military shipbuilding is characterized by the development of technologically advanced and specialized vessels, such as destroyers, frigates, and submarines, which require significant resources and expertise. Both segments are key drivers of the shipbuilding market, influencing technological advancements and fueling ongoing growth.
Segments:
Based on Type:
- Cruise Ships
- Cargo Ships
- Military Vessels
- Tugs
- Fishing Vessels
- Bunker Tankers
- Small Passenger Ships
- Small General Cargo Carriers
Based on End-User:
- Transport
- Military
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
Asia Pacific
Asia Pacific holds the largest market share in the global shipbuilding market, accounting for over 40% of the total industry revenue. The region is dominated by countries like China, South Korea, and Japan, which are home to some of the world’s largest and most advanced shipyards. These countries benefit from strong government support, access to advanced technology, and a highly skilled labor force, enabling them to produce a wide range of vessels, from large cargo ships to advanced military vessels. China's strategic investments in maritime infrastructure and its growing shipbuilding capacity position it as a leader in the global market. Similarly, South Korea and Japan maintain a competitive edge due to their expertise in constructing technologically advanced ships, such as LNG carriers and ultra-large container ships. Asia Pacific’s dominance in the shipbuilding market is further fueled by the region’s rapidly expanding trade activities and maritime transport requirements.
Europe
Europe accounts for a significant portion of the global shipbuilding market, with approximately 20% market share, primarily driven by countries like Germany, Italy, and France. The European shipbuilding industry is known for its focus on high-value ships, such as luxury cruise liners, naval vessels, and specialized vessels for offshore energy sectors. European shipyards are renowned for their advanced engineering capabilities and high-quality craftsmanship, which makes them leaders in constructing complex, high-tech vessels. Additionally, the region is a key player in the production of military ships, with several European nations heavily investing in naval modernization programs. Europe's shipbuilding market is also influenced by stringent environmental regulations, which have spurred the development of eco-friendly and energy-efficient ship designs. This emphasis on sustainability, coupled with the region's focus on innovation and quality, continues to bolster Europe's standing in the global shipbuilding industry.
Key Player Analysis
- Daewoo Shipbuilding and Marine Engineering
- TSUNEISHI SHIPBUILDING Co. Ltd.
- Imabari Shipbuilding
- Hyundai Heavy Industries
- Northstar Shipbuilding Private Limited
- Samsung Heavy Industries
- Mitsubishi Heavy Industry
- United Shipbuilding Corporation
- L&T India
Competitive Analysis
In the Shipbuilding Market, leading players such as Hyundai Heavy Industries, Samsung Heavy Industries, Daewoo Shipbuilding and Marine Engineering, TSUNEISHI SHIPBUILDING Co. Ltd., and Mitsubishi Heavy Industry dominate the competitive landscape. These companies benefit from advanced shipyard facilities, strong government backing, and continuous investment in research and development to innovate and maintain technological leadership. They focus on producing a wide range of vessels, from commercial and cargo ships to military and specialized vessels, while responding to market demands for more eco-friendly and energy-efficient ships. Competition among these players is intense, driven by the need to meet strict environmental regulations and growing global demand for larger, technologically advanced vessels. Additionally, their extensive global networks and established customer bases allow them to secure long-term contracts, which further strengthens their competitive positions.
Recent Developments
- In June 2024, TSUNEISHI SHIPBUILDING commercialized a new energy-saving device.
- In February 2023, Imabari built the world’s first ship using low CO2 steel from Kobe Steel.
Market Concentration & Characteristics
The Shipbuilding Market exhibits a moderate to high level of market concentration, with a few key players dominating the industry, particularly in regions like Asia Pacific and Europe. Companies such as Hyundai Heavy Industries, Samsung Heavy Industries, and Daewoo Shipbuilding and Marine Engineering control a significant portion of the global market, benefiting from advanced technology, large-scale shipyards, and government support. These major players focus on high-volume production and technological innovation, including eco-friendly vessels and automation. However, smaller shipbuilders, often specializing in niche markets like luxury yachts or specialized vessels, also play a vital role in the industry. The market is characterized by high capital investment requirements, long production cycles, and the need for skilled labor. Additionally, stringent environmental regulations and evolving customer demands for fuel-efficient and technologically advanced ships further shape the competitive landscape, encouraging both consolidation and innovation within the industry.
Report Coverage
The research report offers an in-depth analysis based on Type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Global demand for larger and more fuel-efficient vessels will continue to rise as shipping companies seek cost-effective solutions.
- Environmental regulations will push shipbuilders to develop cleaner propulsion technologies such as LNG and hybrid systems.
- Automation and digitalization in shipbuilding processes will drive efficiency and reduce construction time.
- The adoption of autonomous ships is expected to grow, transforming operational models and reducing crew requirements.
- Military modernization efforts will lead to increased investments in advanced naval vessels and defense-related shipbuilding.
- Offshore wind energy projects will create demand for specialized ships, such as installation and service vessels.
- The market will witness increased competition among shipbuilders in emerging markets, particularly in Asia and Africa.
- Modular construction techniques will gain popularity, reducing costs and offering greater flexibility in ship design.
- Demand for luxury cruise liners and passenger vessels will grow alongside expanding global tourism.
- Supply chain optimization will become a focus as shipbuilders seek to manage rising material costs and ensure production efficiency.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Global Trade and Maritime Tourism
The expansion of international trade and the rise in maritime tourism are driving demand for new and advanced vessels, as more goods and passengers are transported by sea. This trend is especially pronounced in emerging markets and regions with growing disposable incomes, fueling the need for both cargo and passenger ships.
Infrastructure Development and Improved Connectivity
Significant investments in port and maritime infrastructure, such as new terminals and navigational aids, are enabling the accommodation of larger vessels and higher shipping volumes. These upgrades support the growth of the shipbuilding market by increasing the demand for modern, efficient ships.
Technological Advancements and Automation
Innovations in ship design, propulsion systems, and digitalization - including automation and digital twin technology - are making shipbuilding processes more efficient and cost-effective. These advancements allow shipbuilders to meet evolving customer requirements and regulatory standards, while reducing operational costs.
Environmental Regulations and Demand for Cleaner Technologies
Stricter global emissions standards are compelling shipbuilders to develop vessels with cleaner propulsion systems, such as LNG and hybrid technologies. This regulatory pressure is accelerating the adoption of energy-efficient and sustainable ship designs, driving market growth.
Military Modernization and Naval Investments
Geopolitical tensions and the need for national security are prompting governments to invest in modernizing their naval fleets. This results in increased demand for technologically advanced military vessels, such as submarines and aircraft carriers, supporting the shipbuilding sector.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Shipbuilding Market?
What factors are driving the growth of the Shipbuilding Market?
What are the key segments within the Shipbuilding Market?
What are some challenges faced by the Shipbuilding Market?
Who are the major players in the Shipbuilding Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Cruise Ships
- 1.2.2 Cargo Ships
- 1.2.3 Military Vessels
- 1.2.4 Tugs
- 1.2.5 Fishing Vessels
- 1.2.6 Bunker Tankers
- 1.2.7 Small Passenger Ships
- 1.2.8 Small General Cargo Carriers
- 1.3 By End-User
- 1.3.1 Transport
- 1.3.2 Military
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 161,702.69 million → 2032: USD 223,009.36 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Shipbuilding Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Shipbuilding Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Shipbuilding Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Shipbuilding Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Shipbuilding Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Shipbuilding Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Shipbuilding Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Shipbuilding Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 161,702.69 million → 2032: USD 223,009.36 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Shipbuilding Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Cruise Ships
- 12.3.7.2 Cargo Ships
- 12.3.7.3 Military Vessels
- 12.3.7.4 Tugs
- 12.3.7.5 Fishing Vessels
- 12.3.7.6 Bunker Tankers
- 12.3.7.7 Small Passenger Ships
- 12.3.7.8 Small General Cargo Carriers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Transport
- 12.4.7.2 Military
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Shipbuilding End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Shipbuilding Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Shipbuilding Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Shipbuilding Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Hyundai Heavy Industries
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Samsung Heavy Industries
- 18.4 Daewoo Shipbuilding and Marine Engineering
- 18.5 TSUNEISHI SHIPBUILDING Co. Ltd.
- 18.6 Mitsubishi Heavy Industry
- 18.7 Imabari Shipbuilding
- 18.8 United Shipbuilding Corporation
- 18.9 L&T India
- 18.10 Northstar Shipbuilding Private Limited
- 18.11 Fincantieri
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

