
Market Overview:
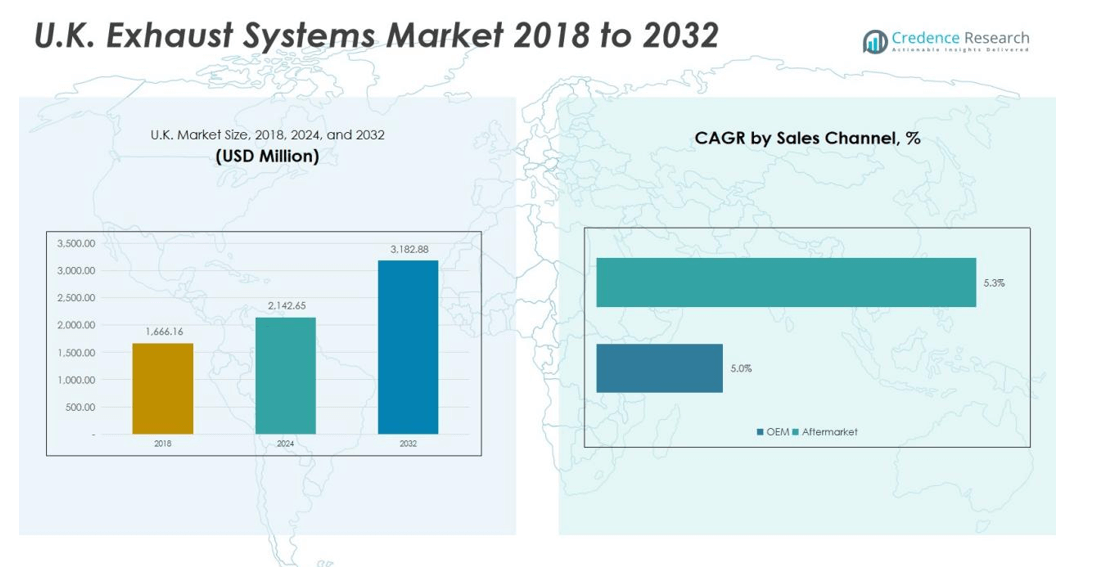
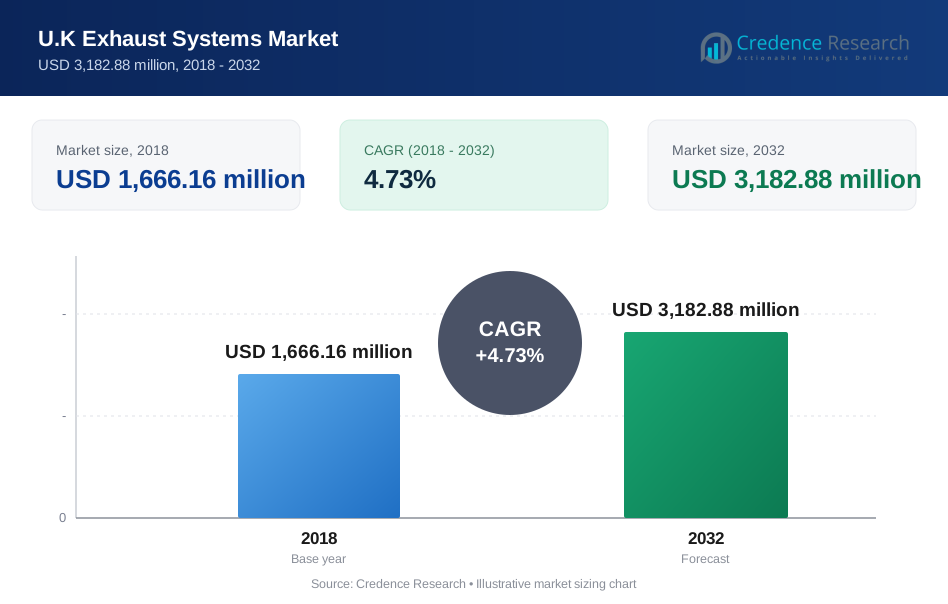
The U.K Exhaust Systems Market size was valued at USD 1,666.16 million in 2018 to USD 2,142.65 million in 2024 and is anticipated to reach USD 3,182.88 million by 2032, at a CAGR of 4.73% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.K Exhaust Systems Market Size 2024 | USD 2,142.65 million |
| U.K Exhaust Systems Market, CAGR | 4.73% |
| U.K Exhaust Systems Market Size 2032 | USD 3,182.88 million |
Stringent emission norms aligned with Euro 6 and the upcoming Euro 7 standards drive innovation in exhaust system design. Manufacturers are developing advanced catalytic converters, diesel particulate filters, and lightweight materials to improve fuel efficiency and reduce emissions. The shift toward hybrid and plug-in hybrid vehicles boosts demand for efficient exhaust solutions that maintain performance while meeting sustainability goals.
Regionally, England remains the primary hub for the exhaust systems industry due to its strong automotive manufacturing base, R&D facilities, and presence of leading OEMs. The Midlands and Northern England contribute significantly through specialized component production and engineering innovation. Wales and Scotland are emerging markets, driven by new investments in green mobility and government initiatives supporting low-emission vehicle manufacturing.
Market Insights:
- The U.K. Exhaust Systems Market was valued at USD 1,666.16 million in 2018, reached USD 2,142.65 million in 2024, and is expected to attain USD 3,182.88 million by 2032, growing at a CAGR of 4.73% during the forecast period.
- England accounts for nearly 58% of the market share, driven by a strong automotive manufacturing base and major OEM presence. The Midlands and Northern England contribute about 25% combined, supported by advanced R&D centers and specialized component production facilities.
- Wales and Scotland together hold around 12% of the market and represent the fastest-growing regions, fueled by investments in green mobility infrastructure and hybrid vehicle component manufacturing.
- By product type, components dominate with approximately 68% share, led by catalytic converters, mufflers, and exhaust pipes, which are vital for emission reduction.
- By vehicle type, passenger vehicles represent nearly 61% of total market revenue, driven by high ownership rates and strong demand for efficient, low-emission mobility solutions.
Market Drivers:
Stringent Emission Norms Driving Innovation and Compliance
The U.K. Exhaust Systems Market is strongly influenced by strict emission regulations aligned with Euro 6 and upcoming Euro 7 standards. These policies compel manufacturers to integrate advanced catalytic converters, diesel particulate filters, and selective catalytic reduction systems. It fosters continuous innovation in exhaust materials and designs that enhance performance while meeting environmental targets. The regulatory environment pushes OEMs to adopt lightweight alloys and composite structures, reducing emissions without compromising engine output.
- For instance, in July 2025, Bentley Motors introduced a new titanium Akrapovič sports exhaust system for its Continental GT, GT Convertible, and Flying Spur models, achieving a weight reduction of up to 10 kilograms while maintaining acoustic refinement and compliance with Euro 7 requirements.
Rising Adoption of Hybrid and Plug-In Hybrid Vehicles
The growing shift toward hybrid and plug-in hybrid vehicles acts as a major growth driver for the U.K. Exhaust Systems Market. Hybrid powertrains still require efficient exhaust management to control emissions from combustion engines during operation. It drives demand for compact and thermally efficient exhaust systems capable of managing variable temperature and flow conditions. Automakers are investing in flexible exhaust architectures that ensure durability and performance under hybrid usage patterns.
- For Instance, Faurecia equipped the Hyundai IONIQ Hybrid with a compact Exhaust Heat Recovery System. The system was capable of capturing up to 75% of exhaust heat and contributed to fuel savings of up to 7% by enabling faster engine and cabin warm-up, which allowed the hybrid to operate more often in electric mode.
Increasing Focus on Lightweight and High-Performance Materials
Manufacturers are prioritizing lightweight materials such as stainless steel, aluminum, and titanium in exhaust design. This transition reduces vehicle weight, improving fuel economy and cutting emissions. The U.K. automotive sector’s emphasis on high-performance vehicles further supports innovation in heat-resistant and corrosion-proof materials. It creates a competitive edge for domestic suppliers and encourages partnerships with global material technology firms.
Government Incentives and Expansion of Sustainable Mobility Programs
Government policies promoting low-emission mobility and electric-hybrid integration are accelerating exhaust technology upgrades. The U.K. government’s Clean Air Strategy and zero-emission vehicle mandates are encouraging innovation in emission control components. Public and private funding for sustainable automotive R&D strengthens technological advancement in exhaust systems. It enhances the nation’s capacity to meet long-term carbon reduction goals while supporting automotive sector competitiveness.
Market Trends:
Integration of Advanced Emission Control and Thermal Management Technologies
The U.K. Exhaust Systems Market is witnessing a major shift toward advanced emission control systems that combine efficiency and durability. Manufacturers are integrating selective catalytic reduction (SCR), gasoline particulate filters (GPF), and active regeneration systems to meet future Euro 7 standards. It reflects the automotive industry’s focus on optimizing temperature management and exhaust gas treatment across all driving conditions. Demand for intelligent exhaust valves and heat recovery mechanisms is increasing to improve engine performance and reduce energy losses. Tier-1 suppliers are investing in smart sensors and electronic control units that monitor emission levels in real time. This trend strengthens compliance, enhances vehicle reliability, and aligns with the country’s carbon neutrality objectives by 2050.
- For instance, Faurecia (now FORVIA) introduced its Compact Exhaust Heat Recovery System (EHRS) weighing under 3 kilograms, delivering up to 7% improvement in fuel efficiency for hybrid vehicles such as the Hyundai IONIQ and Ford F-150 through faster heat recovery and improved thermal control.
Adoption of Lightweight, Modular, and Electrified Exhaust Architectures
The transition toward electrification and hybridization is reshaping design priorities for exhaust systems in the United Kingdom. Manufacturers are adopting modular exhaust platforms made from lightweight materials like titanium and composite alloys to reduce mass and manufacturing costs. The integration of electric heating elements and noise control modules enhances thermal management in hybrid vehicles. It promotes consistent emission reduction even under cold-start conditions, a key focus for urban emission control. The market is also seeing a rise in 3D printing and digital simulation tools that accelerate prototype development and customization. These innovations improve system adaptability across diverse vehicle categories, supporting sustainable mobility goals and driving steady growth within the U.K. Exhaust Systems Market.
- For instance, Tenneco and Eaton jointly developed an integrated exhaust thermal management system in 2025 that uses Eaton’s TVS Roots blower to heat the SCR catalyst to around 250°C, cutting cold-start nitrogen oxide emissions by over 90% for Euro 7-compliant vehicles in the UK automotive market.
Market Challenges Analysis:
Rising Electric Vehicle Adoption Reducing Demand for Conventional Exhaust Systems
The growing shift toward electric vehicles poses a long-term challenge for the U.K. Exhaust Systems Market. Pure electric vehicles eliminate the need for exhaust systems, directly impacting future demand. It pressures manufacturers to diversify into hybrid-compatible or alternative thermal management components. The government’s 2035 ban on new petrol and diesel cars further accelerates this transition. OEMs and suppliers must adapt their production strategies to remain relevant in a changing mobility landscape. The transition requires heavy investment in R&D and supply chain restructuring to sustain profitability.
High Production Costs and Supply Chain Disruptions Impacting Competitiveness
Rising costs of raw materials such as stainless steel, nickel, and titanium are increasing the overall production expenses for exhaust system manufacturers. It affects pricing flexibility and reduces margins for small and medium suppliers. Global supply chain disruptions and fluctuating import tariffs have further complicated component availability. Manufacturers face pressure to balance quality with cost efficiency while maintaining compliance with strict emission regulations. The need for advanced testing, certification, and material sourcing also adds operational complexity. These challenges slow product innovation and hinder competitiveness within the U.K. Exhaust Systems Market.
Market Opportunities:
Expansion of Hybrid and Plug-In Hybrid Vehicle Segment Creating Growth Avenues
The rapid growth of hybrid and plug-in hybrid vehicles presents strong opportunities for the U.K. Exhaust Systems Market. These vehicles still rely on efficient exhaust systems to manage emissions during combustion engine operation. It encourages innovation in compact, thermally stable, and energy-efficient exhaust solutions. Manufacturers are focusing on integrating smart sensors and lightweight materials to enhance system performance and durability. The market can benefit from the government’s continued investment in hybrid mobility programs that bridge the transition to full electrification. This segment offers a sustainable revenue stream for suppliers adapting to changing propulsion technologies.
Adoption of Smart Manufacturing and Advanced Material Technologies
The shift toward Industry 4.0 and smart manufacturing creates new opportunities for local exhaust system producers. Automation, robotics, and AI-driven design tools help improve precision, reduce waste, and shorten production cycles. It supports the creation of modular and customizable exhaust platforms tailored for diverse vehicle types. Advanced material technologies such as ceramic coatings and corrosion-resistant alloys further expand product longevity. Collaborations between research institutions and OEMs enhance R&D capabilities and accelerate innovation. These advancements position the U.K. Exhaust Systems Market to strengthen its global competitiveness while meeting evolving emission and performance standards.
Market Segmentation Analysis:
By Product Type
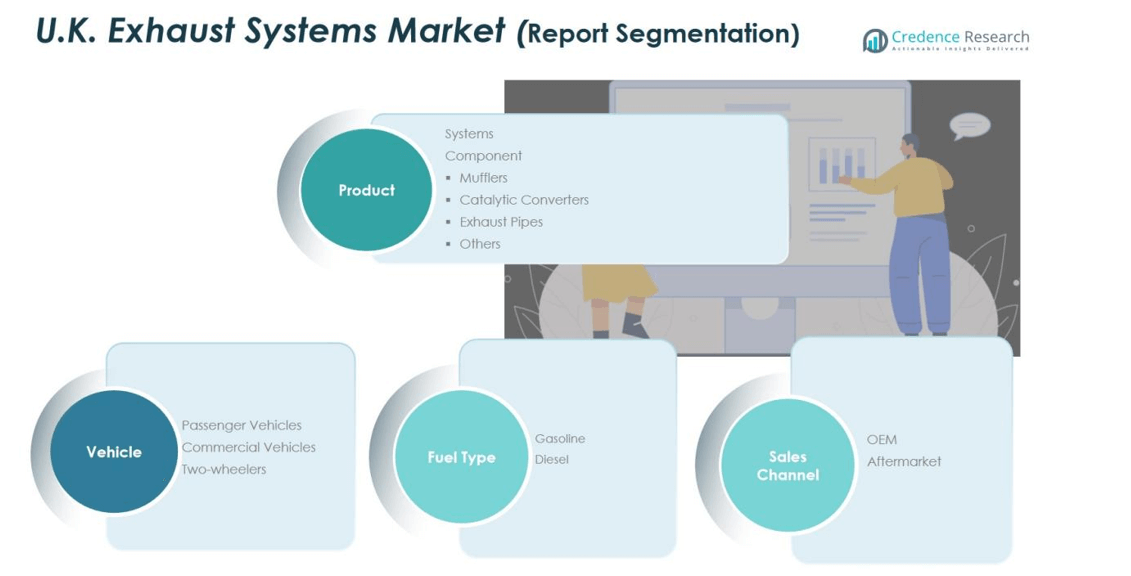
The U.K. Exhaust Systems Market is segmented into systems and components, including mufflers, catalytic converters, exhaust pipes, and others. Components hold a major share due to their critical role in emission reduction and noise control. It benefits from increasing demand for advanced catalytic converters and particulate filters to meet Euro 6 and Euro 7 standards. Manufacturers are investing in lightweight and corrosion-resistant materials to extend product life and enhance fuel efficiency. The systems segment continues to grow with integration of modular and hybrid-compatible exhaust assemblies in new vehicle platforms.
- For Instance, Milltek also offers systems for the Cupra Formentor 1.4 TSi e-hybrid, these were available before 2024, with some products dating back to 2022.
By Vehicle Type
Passenger vehicles dominate the market due to high ownership rates and consumer demand for cleaner, efficient mobility solutions. The commercial vehicle segment shows steady growth driven by logistics and public transport expansion. It focuses on robust exhaust designs capable of handling higher emission volumes and extended operational hours. Two-wheelers contribute a smaller share but benefit from urban mobility programs and rising motorcycle sales across cities.
- For Instance, Hero MotoCorp launched the Splendor Plus Xtec 2.0 in 2024, which features i3S idle start-stop technology and has an ARAI-certified mileage of 73 kmpl.
By Fuel Type
Gasoline-powered vehicles lead the U.K. Exhaust Systems Market due to their widespread adoption and ongoing upgrades in emission control technologies. Diesel vehicles continue to hold relevance in the commercial and heavy-duty sectors, supported by advancements in selective catalytic reduction (SCR) systems. It faces regulatory pressure to reduce particulate and NOx emissions, encouraging adoption of cleaner alternatives and hybrid-compatible exhaust solutions.
Segmentations:
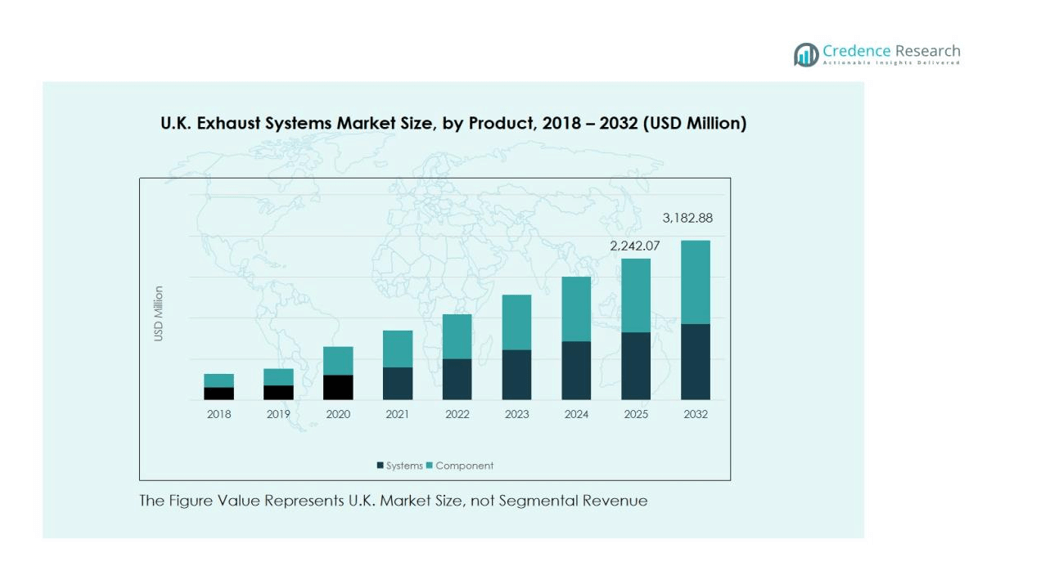
By Product Type
- Systems
- Components
- Mufflers
- Catalytic Converters
- Exhaust Pipes
- Others
By Vehicle Type
- Passenger Vehicles
- Commercial Vehicles
- Two-Wheelers
By Fuel Type
- Gasoline
- Diesel
By Sales Channel
- OEM
- Aftermarket
Regional Analysis:
Dominance of England Driven by Strong Automotive Manufacturing Base
England represents the largest share of the U.K. Exhaust Systems Market due to its well-established automotive ecosystem. The Midlands and Northern England serve as major production hubs for OEMs and Tier-1 suppliers, including companies specializing in emission control technologies. It benefits from advanced R&D facilities, engineering expertise, and proximity to global automotive leaders. The presence of brands such as Jaguar Land Rover and Ford supports consistent demand for high-performance exhaust components. Government incentives for sustainable manufacturing and innovation strengthen England’s position as the core region for exhaust system development.
Emerging Growth in Wales and Scotland Through Green Mobility Investments
Wales and Scotland are emerging regional contributors, supported by growing investments in low-emission vehicle infrastructure and component manufacturing. The expansion of local assembly units and supplier networks improves the regional value chain for exhaust production. It benefits from national programs promoting clean mobility and the shift toward hybrid and plug-in hybrid vehicles. Research partnerships between universities and automotive companies are fostering innovation in lightweight and recyclable exhaust materials. These developments create new opportunities for suppliers focusing on eco-friendly designs and cost-efficient production methods.
Northern Ireland’s Focus on Aftermarket and Export Opportunities
Northern Ireland plays a smaller but strategic role in the U.K. Exhaust Systems Market through its aftermarket and export-oriented operations. The region supports component manufacturing for replacement parts and specialized exhaust assemblies. It leverages its logistics connectivity and technical workforce to cater to European demand. Local firms are investing in digital manufacturing processes to enhance precision and quality standards. The region’s focus on value-added exports positions it as an emerging contributor within the overall U.K. exhaust systems landscape.
Key Player Analysis:
- GT Exhausts
- Futaba Industrial Co., Ltd.
- MagnaFlow
- Yutaka Giken
- Eberspächer
- PD Gough
- BOSAL
- Sejong Industrial Co., Ltd.
- Milltek
- Continental AG
Competitive Analysis:
The U.K. Exhaust Systems Market is moderately consolidated, with competition centered on technology innovation, material efficiency, and emission compliance. Key players include GT Exhausts, Futaba Industrial Co., Ltd., MagnaFlow, Yutaka Giken, Eberspächer, PD Gough, and BOSAL. It focuses on developing lightweight, high-durability exhaust components to meet Euro 7 standards and reduce carbon output. Companies are expanding R&D capabilities and forming strategic alliances with OEMs to enhance product performance and cost efficiency. Local firms emphasize customization and precision engineering to maintain competitiveness against global brands. Continuous investment in smart manufacturing and hybrid-compatible exhaust systems strengthens market positioning and supports long-term growth.
Recent Developments:
- In September 2025, Futaba Industrial released its Earnings Results Presentation for the first three months of the fiscal year ending March 31, 2025 (112th term).
- In September 2025, Purem by Eberspächer developed Direct Air Capture Technology designed to remove CO₂ from the atmosphere, expanding the company's expertise beyond traditional exhaust systems.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Vehicle Type, Fuel Type and Sales Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The U.K. Exhaust Systems Market will evolve through increased focus on emission reduction and system efficiency.
- Manufacturers will prioritize R&D for lightweight and hybrid-compatible exhaust architectures.
- The adoption of Euro 7 standards will accelerate demand for advanced catalytic converters and particulate filters.
- OEMs will invest in intelligent exhaust monitoring systems with integrated sensors and data analytics.
- Hybrid and plug-in hybrid vehicles will continue to offer steady opportunities for system innovation.
- Automation and AI-driven manufacturing will improve precision, consistency, and production speed.
- Sustainability initiatives will drive greater use of recyclable and corrosion-resistant materials.
- Aftermarket demand will remain stable, supported by replacement and upgrade needs in older vehicles.
- Collaborations between local firms and international suppliers will expand technological capabilities and export reach.
- Long-term growth will depend on balancing regulatory compliance with cost efficiency and design innovation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the U.K. Exhaust Systems Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the U.K. Exhaust Systems Market projected to grow between 2024 and 2032?
Which U.K. Exhaust Systems Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the U.K. Exhaust Systems Market?
Who are the leading companies in the U.K. Exhaust Systems Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 U.K Exhaust Systems Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2018; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 U.K Exhaust Systems Snapshot
- 2.1.1 Market Size – Historical (2018) & Forecast (2018-2032) (2018: USD 1,666.16 million → 2032: USD 3,182.88 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 U.K Exhaust Systems Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2018 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2018
- 2.3.2 Top 10 Players by Volume Share – 2018 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. U.K Exhaust Systems Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 U.K Exhaust Systems Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 U.K Exhaust Systems Drivers
- 3.3 U.K Exhaust Systems Restraints & Challenges
- 3.4 U.K Exhaust Systems Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 U.K Exhaust Systems Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 U.K Exhaust Systems Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, U.K Exhaust Systems category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 U.K Exhaust Systems Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. U.K Exhaust Systems Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2018)
- 5.1.2 Export Volume by Destination Country (2018) (Where Applicable)
- 5.1.3 Import Value by Source Country (2018)
- 5.1.4 Import Volume by Source Country (2018) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2018)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2018)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to U.K Exhaust Systems in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 U.K Exhaust Systems Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2018
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 U.K Exhaust Systems Share Analysis – 2018
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution ( vs. 2018)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 U.K Exhaust Systems Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in U.K Exhaust Systems (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in U.K Exhaust Systems
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. U.K Exhaust Systems – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2018 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2018-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. U.K Exhaust Systems – Priority Domestic Market 1
Chapter 10. U.K Exhaust Systems – Priority Domestic Market 2
Chapter 11. U.K Exhaust Systems – Priority Domestic Market 3
Chapter 12. U.K Exhaust Systems – Priority Domestic Market 4
Chapter 13. U.K Exhaust Systems Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
