
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
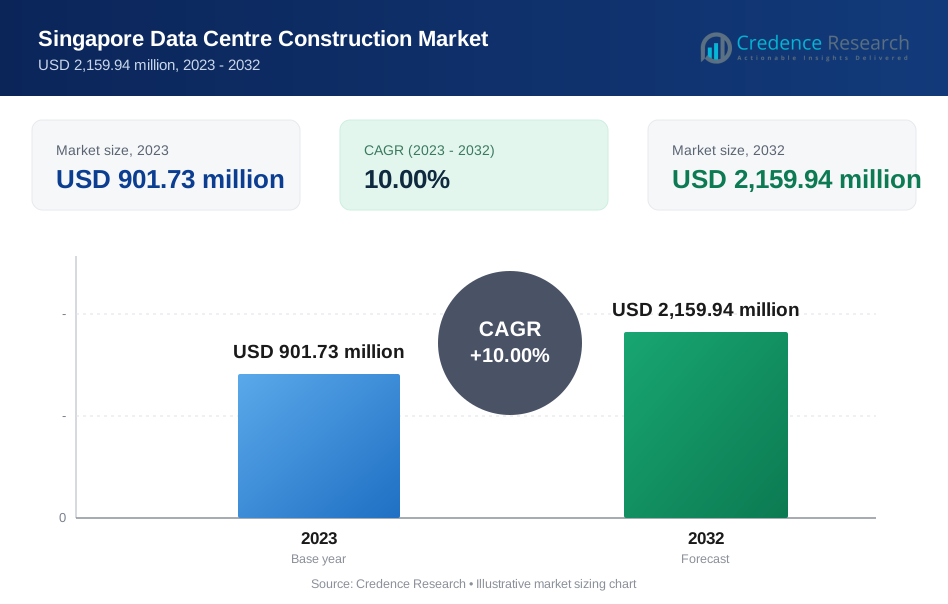
| Singapore Data Centre Construction Market Size 2023 | USD 901.73 Million |
| Singapore Data Centre Construction Market, CAGR | 10.00% |
| Singapore Data Centre Construction Market Size 2032 | USD 2,159.94 Million |
Market Overview
The Singapore Data Centre Construction Market is projected to grow from USD 901.73 million in 2023 to USD 2,159.94 million by 2032, reflecting a compound annual growth rate (CAGR) of 10.00%.
The Singapore Data Centre Construction Market is driven by the growing demand for cloud computing, big data analytics, and digital transformation across various industries. The country’s strategic location in Asia, robust connectivity infrastructure, and supportive government policies attract major global tech companies to establish data centers. Additionally, Singapore’s focus on sustainability and energy efficiency aligns with global trends, prompting the integration of green technologies and renewable energy in data center operations. The increasing adoption of AI and IoT technologies further boosts the need for advanced data storage and processing facilities, contributing to the market's rapid growth.
The Singapore Data Centre Construction Market is primarily concentrated in key areas such as Jurong, Changi, and Woodlands, benefiting from the country's strategic geographic location and robust infrastructure. Singapore's role as a regional data hub is supported by its extensive network of undersea cables, reliable power supply, and advanced telecommunications infrastructure. These factors make it an attractive destination for data center investments. Leading players in the market include AECOM, NTT Ltd., Fortis Construction, IBM Corporation, and Schneider Electric SE, all of which leverage their expertise in building state-of-the-art facilities that meet the growing demand for cloud computing and digital services.
Market Drivers
Robust Infrastructure
The reliability of Singapore’s infrastructure is a critical factor in the growth of its data center market. The country boasts a highly reliable and efficient power grid, ensuring that data centers have an uninterrupted power supply, which is crucial for maintaining operations. Despite the challenges posed by the tropical climate, advancements in cooling technologies have enabled data centers to manage heat efficiently, ensuring optimal performance and energy efficiency. For instance, the Green Data Centre Roadmap encourages the adoption of energy-efficient hardware and software, and the implementation of innovative cooling technologies. Singapore's well-developed telecommunications infrastructure supports high-speed internet connectivity, making it possible for data centers to handle large volumes of data traffic smoothly. These infrastructure strengths are pivotal in supporting the expanding demand for data center services in the region.
Growing Demand for Cloud Services
The increasing adoption of cloud computing services is a major driver of the Singapore data center construction market. As businesses increasingly rely on cloud-based solutions for their operations, the demand for robust data storage, processing, and retrieval capabilities continues to grow. For instance, the public cloud market in Singapore has become a cornerstone of the country’s digital transformation journey, with companies across various sectors migrating their workloads and applications to the public cloud. The proliferation of data-intensive applications, such as artificial intelligence, machine learning, and the Internet of Things (IoT), further fuels the need for advanced data center infrastructure. These technologies generate vast amounts of data, necessitating the expansion of data center capacities to accommodate and efficiently manage these data loads. The trend towards digital transformation across various industries underscores the critical role of data centers in supporting modern business operations and innovation.
Strategic Geographic Location
Singapore’s strategic location in Southeast Asia provides excellent connectivity to major markets, making it a prime hub for data center operations. Its position allows for seamless data flow across the region, significantly reducing latency and improving service delivery for businesses. The country is also home to numerous undersea cable landing stations, which enhance its connectivity to global networks. These cables are critical for international data transmission, making Singapore a pivotal point for data flow between Asia and the rest of the world. This robust connectivity infrastructure makes Singapore an attractive location for companies looking to establish or expand their data center operations.
Stable Political and Economic Environment
Singapore's stable political and economic environment is a significant driver of its data center construction market. The government has consistently supported the growth of the industry through favorable policies, infrastructure development, and financial incentives. This proactive stance has created a business-friendly climate that attracts both local and international data center operators. The strong rule of law, efficient bureaucracy, and predictable regulatory environment further enhance Singapore’s appeal as a secure and reliable location for business operations. These factors combine to create a conducive environment for investment in the data center sector, ensuring steady growth and development.
Market Trends
Sustainability, Energy Efficiency, and Data Center Interconnection
Sustainability and energy efficiency are becoming key priorities for data center operators in Singapore, driven by the need to minimize environmental impact and reduce operational costs. The industry is increasingly adopting green initiatives, including the use of renewable energy sources such as solar power to power data center operations. For instance, advanced cooling systems, power management technologies, and energy-efficient data center designs are being implemented to optimize energy consumption, ensuring that data centers operate with minimal energy waste. These measures not only reduce the carbon footprint of data centers but also enhance their economic viability by lowering energy costs. Additionally, Singapore is emerging as a major data center interconnection hub, attracting businesses that require robust connectivity and low-latency connections. The presence of multiple carrier-neutral data centers and interconnection points facilitates seamless data exchange and connectivity between different data centers and cloud platforms. This extensive connectivity infrastructure enables businesses to establish reliable, high-speed connections, reducing latency and improving the performance of real-time applications.
Hyper-Scale Data Centers and Modular Data Centers
The Singapore Data Centre Construction Market is experiencing significant growth driven by the expansion of hyper-scale and modular data centers. Major cloud service providers like Google, Amazon Web Services (AWS), and Microsoft are heavily investing in large-scale hyper-scale data centers to meet the rising demand for cloud-based services in the region. These hyper-scale facilities offer immense storage capacity and processing power, making them ideal for handling the vast amounts of data generated by modern businesses. Their ability to support large-scale data operations positions Singapore as a critical hub for cloud service providers, serving both regional and global markets. In parallel, there is a growing popularity of modular data centers due to their scalability and flexibility. Unlike traditional data centers, modular facilities can be quickly expanded or relocated, adapting to changing business requirements. This flexibility is particularly beneficial in a dynamic market environment where technology needs can evolve rapidly. Moreover, modular construction techniques allow for faster deployment times, significantly reducing the time-to-market for new data center projects. This approach enables businesses to scale their operations efficiently, meeting demand without the long lead times associated with traditional construction methods.
Market Challenges Analysis
Land Constraints, High Land Costs, and Cooling Challenges
The Singapore Data Centre Construction Market faces significant challenges related to land constraints and high land costs. As a small island nation, Singapore has limited land availability, making it difficult to acquire suitable plots for large-scale data center projects. The scarcity of land drives up demand, resulting in high land prices, which can significantly increase the overall cost of constructing data centers. For instance, Singapore ranks as the most expensive market for land cost in Southeast Asia. These high land costs are a major concern for data center operators, as they can affect the financial feasibility of new projects. Additionally, Singapore's tropical climate presents cooling challenges, with high humidity and temperatures increasing the energy required to maintain optimal operating conditions for data centers. Traditional cooling methods can be highly energy-intensive, leading to increased operational costs and higher carbon footprints. Data center operators must invest in advanced cooling technologies and energy-efficient designs to mitigate these challenges, balancing the need for effective cooling with the imperative to minimize energy consumption and environmental impact.
Regional Competition, Regulatory Challenges, and Talent Shortages
Singapore also faces competition from neighboring countries such as Malaysia and Indonesia, which offer lower land and potentially lower energy costs. These countries are becoming attractive alternatives for data center investments, offering competitive pricing and incentives to lure data center operators away from Singapore. This regional competition pressures Singapore to maintain its attractiveness by offering favorable policies and enhancing its data center infrastructure. Furthermore, navigating Singapore's complex regulatory landscape can be time-consuming and costly. Compliance with stringent data privacy and security regulations, such as the General Data Protection Regulation (GDPR) and the Personal Data Protection Act (PDPA), imposes additional burdens on data center operators. These regulations require substantial investments in security infrastructure and compliance measures to protect sensitive data and ensure adherence to legal standards. Talent shortages present another challenge, as the demand for skilled professionals in data center design, construction, and operations outpaces supply. This talent gap can hinder project execution and drive up labor costs as companies compete for qualified personnel. The need to attract and retain skilled talent is critical to the successful development and operation of data centers in Singapore, making investment in training and workforce development a priority for the industry. Balancing these challenges while maintaining competitiveness and adhering to regulatory standards is essential for the sustained growth of the Singapore Data Centre Construction Market.
Market Segmentation Analysis:
By Type:
The Singapore Data Centre Construction Market is segmented by type into Tier 1, Tier 2, Tier 3, and Tier 4 facilities, each offering different levels of reliability, redundancy, and security. Tier 1 and Tier 2 data centers provide basic infrastructure and limited redundancy, suitable for non-critical applications. However, the market shows a strong preference for Tier 3 and Tier 4 facilities, driven by the demand for high reliability and uptime. These advanced data centers offer higher levels of redundancy and are designed to ensure continuous operation, even during maintenance or unexpected outages, making them ideal for mission-critical applications. Industries such as finance, healthcare, and IT, which require robust data handling and uninterrupted service, are increasingly investing in Tier 3 and Tier 4 data centers. The focus on these high-tier facilities reflects Singapore's commitment to providing secure, reliable, and scalable data infrastructure to support the country's growing digital economy.
By Infrastructure:
The Singapore Data Centre Construction Market is also segmented based on infrastructure, including IT infrastructure, power distribution and cooling (PD & Cooling) infrastructure, and miscellaneous infrastructure. IT infrastructure, which consists of networking equipment, servers, and storage solutions, is critical for ensuring high-speed connectivity and efficient data management. As the demand for cloud services, big data analytics, and AI applications grows, investment in advanced IT infrastructure is increasing. PD & Cooling infrastructure is vital for maintaining optimal operating conditions, providing reliable power distribution and effective cooling systems to prevent downtime and ensure data center efficiency. In Singapore's tropical climate, advanced cooling technologies are essential to manage energy consumption and operational costs. Miscellaneous infrastructure includes security systems, fire suppression, and monitoring equipment, which are crucial for ensuring the safety and reliability of data center operations. This comprehensive approach to infrastructure development supports the growing need for robust, secure, and scalable data center solutions, enabling Singapore to maintain its position as a leading data center hub in Southeast Asia.
Segments:
Based on Type:
- Tier 1
- Tier 2
- Tier 3
- Tier 4
Based on Infrastructure:
- IT Infrastructure
- Networking Equipment
- Server
- Storage
- PD & Cooling Infrastructure
- Power Distribution
- Cooling
- Miscellaneous Infrastructure
Based on Vertical:
- IT & Telecom
- BFSI
- Government & Defense
- Healthcare
- Energy
- Others
Based on the Geography:
- West Region
- East Region
- Central Region
- North Region
- North-East Region
Regional Analysis
East Region
East Region dominating at approximately 60% market share. This area, encompassing districts such as Chai Chee, Loyang, and Tampines, has emerged as the epicenter of Singapore's data centre ecosystem. The East Region's prominence is attributed to its strategic proximity to submarine cable landing stations, providing crucial international connectivity. Major technology parks in this area, such as Changi Business Park and Loyang Industrial Estate, have attracted significant investments from both local and international data centre operators. The region benefits from robust power infrastructure, advanced cooling solutions, and strong government support for digital infrastructure development. Data centres in the East Region are characterized by their scale and sophistication, often incorporating cutting-edge technologies such as AI-driven operations and liquid cooling systems to optimize performance and energy efficiency. The concentration of facilities in this area has created a thriving ecosystem of supporting industries, further cementing its position as Singapore's primary data centre hub.
West Region
The West Region of Singapore holds approximately 30% market share in the data centre construction market, establishing itself as a significant secondary hub. This region, including areas like Jurong and Tuas, has seen growing interest from data centre operators looking to diversify their geographic presence within the city-state. The West Region's appeal lies in its proximity to major industrial zones and the future Tuas Mega Port, positioning it well for edge computing and industrial IoT applications. Data centres in this region often focus on serving the specific needs of manufacturing and logistics sectors, with designs tailored to support high-performance computing and low-latency applications. The area has also attracted investments in green data centres, with operators leveraging the region's developing infrastructure to implement sustainable technologies and renewable energy solutions. As Singapore continues to strengthen its position as a global data centre hub, the West Region is expected to play an increasingly important role in balancing the distribution of digital infrastructure across the island and supporting the nation's smart city initiatives.
Key Player Analysis
- AECOM
- NTT Ltd.
- Fortis Construction
- IBM Corporation
- SAS Institute Inc.
- Schneider Electric SE
- Turner Construction Co.
- ABB Ltd
- Delta Power Solutions
- Precomp Singapore
- TNS Asia Pacific PTE Ltd
Competitive Analysis
The Singapore Data Centre Construction Market is highly competitive, with major players such as AECOM, NTT Ltd., Fortis Construction, IBM Corporation, and Schneider Electric SE dominating the landscape. These companies leverage their extensive experience, technological expertise, and strong local presence to maintain their market positions. They offer comprehensive solutions, including design, construction, and integration of advanced IT and cooling systems, ensuring efficient and sustainable data center operations. Their competitive advantage lies in their ability to deliver large-scale, high-capacity facilities that meet the stringent demands of global cloud service providers and multinational corporations. Additionally, these players are at the forefront of adopting innovative technologies, such as modular construction and energy-efficient designs, to optimize costs and enhance operational efficiency. Their strong partnerships with local authorities and adherence to Singapore’s strict regulatory standards further bolster their market standing, making them the preferred choice for data center projects in the region.
Recent Developments
- In December 2023, NTT and TEPCO Power Grid, Inc. agreed to establish a new company to jointly develop and operate data centers in the Inzai-Shiroi area of Greater Tokyo, Japan.
- In August 15, 2024, IBM and the National University of Singapore (NUS) announced an intention to establish a new AI research and innovation center.
- In 2024, Schneider Electric announced a collaboration with NVIDIA to optimize data center infrastructure and introduce AI data center reference designs.
Market Concentration & Characteristics
The Singapore Data Centre Construction Market is characterized by a high level of market concentration, with a few key players such as AECOM, NTT Ltd., and Schneider Electric SE leading the industry. These companies dominate the market due to their extensive experience, advanced technological capabilities, and comprehensive service offerings, including design, construction, and maintenance of state-of-the-art data centers. The market is marked by a strong emphasis on sustainability and energy efficiency, driven by Singapore’s commitment to reducing carbon emissions and enhancing energy security. Data centers in Singapore are increasingly adopting green technologies, such as advanced cooling systems and renewable energy sources, to meet these goals. The market is also shaped by Singapore’s strategic geographic location, robust infrastructure, and supportive government policies, which attract significant foreign investment. These characteristics make Singapore a preferred hub for data center operations, catering to the growing demand for cloud services, data storage, and digital transformation across Southeast Asia.
Report Coverage
The research report offers an in-depth analysis based on Type, Infrastructure, Vertical and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for data centers in Singapore will continue to grow, driven by the increasing adoption of cloud computing and digital services.
- Investment in hyper-scale data centers will rise to meet the needs of global cloud service providers and large enterprises.
- Sustainability will remain a key focus, with data center operators integrating renewable energy sources and energy-efficient technologies.
- The development of modular and scalable data centers will become more common to address space constraints and enable quicker deployment.
- Singapore's strategic location will continue to attract international data center operators looking to serve the Southeast Asian market.
- Advanced cooling technologies will be increasingly adopted to manage energy consumption and maintain efficiency in Singapore's tropical climate.
- The government will likely introduce more incentives and policies to promote data center growth and enhance Singapore's position as a digital hub.
- The demand for edge computing and micro data centers will rise to support low-latency applications and improve service delivery.
- Data privacy and security will remain critical, prompting continued investment in robust cybersecurity measures.
- Competition with neighboring countries will intensify, pushing Singapore to innovate and maintain its competitive edge in the data center market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Singapore Data Centre Construction Market?
What factors are driving the growth of the Singapore Data Centre Construction Market?
What are the key segments within the Singapore Data Centre Construction Market?
What are some challenges faced by the Singapore Data Centre Construction Market?
Who are the major players in the Singapore Data Centre Construction Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Singapore Data Centre Construction Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Singapore Data Centre Construction Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 901.73 million → 2032: USD 2,159.94 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Singapore Data Centre Construction Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Singapore Data Centre Construction Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Singapore Data Centre Construction Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Singapore Data Centre Construction Market Drivers
- 3.3 Singapore Data Centre Construction Market Restraints & Challenges
- 3.4 Singapore Data Centre Construction Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Singapore Data Centre Construction Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Singapore Data Centre Construction Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Singapore Data Centre Construction category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Singapore Data Centre Construction Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Singapore Data Centre Construction Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Singapore Data Centre Construction market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Singapore Data Centre Construction Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Singapore Data Centre Construction Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Singapore Data Centre Construction Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Singapore Data Centre Construction (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Singapore Data Centre Construction Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Singapore Data Centre Construction Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Singapore Data Centre Construction Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Singapore Data Centre Construction Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Singapore Data Centre Construction Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Singapore Data Centre Construction Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Singapore Data Centre Construction Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Singapore Data Centre Construction Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Singapore Data Centre Construction Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
