
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| South Korea Automotive Air Filter Market Size 2024 | USD 194.970 Million |
| South Korea Automotive Air Filter Market, CAGR | 6.66% |
| South Korea Automotive Air Filter Market Size 2032 | USD 326.673 Million |
Market Overview
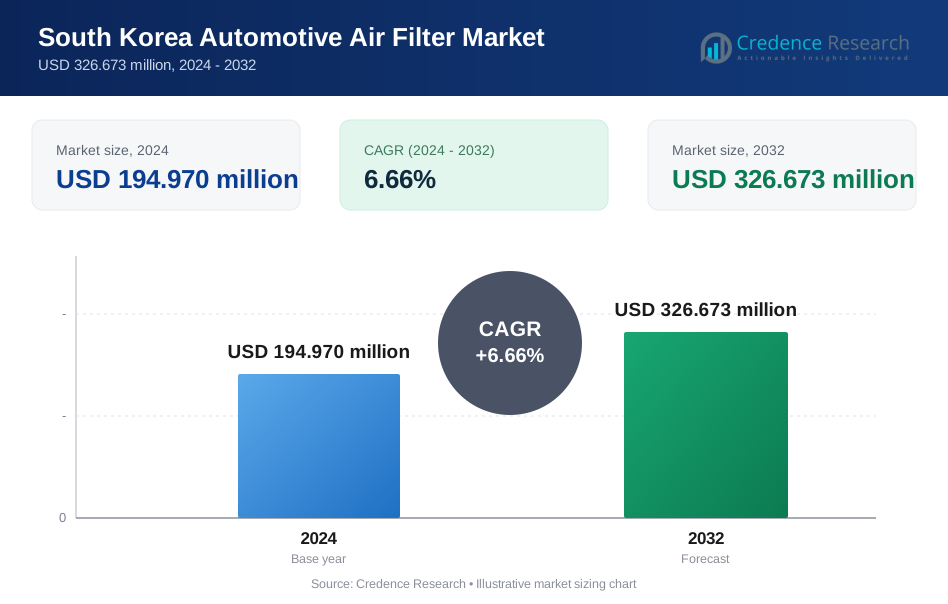
South Korea Automotive Air Filter Market size was valued at USD 194.970 million in 2024 and is anticipated to reach USD 326.673 million by 2032, at a CAGR of 6.66% during the forecast period (2024-2032).
The South Korea Automotive Air Filter Market is driven by stringent emission regulations, rising vehicle production, and growing consumer awareness of air quality. The government's focus on reducing vehicular emissions has increased the adoption of advanced air filtration systems. Additionally, the expansion of the automotive sector, fueled by increasing disposable income and urbanization, is boosting demand for efficient air filters. The shift toward electric and hybrid vehicles is further accelerating innovation in high-performance filtration technologies. Key market trends include the rising adoption of HEPA and activated carbon filters, which enhance air purification by removing fine particulates and pollutants. Moreover, manufacturers are integrating nanotechnology to improve filter efficiency and durability. The growing preference for cabin air filters, driven by heightened health concerns, is another notable trend. E-commerce platforms and aftermarket sales channels are expanding, offering consumers easy access to high-quality air filters, thereby strengthening market growth.
The South Korea automotive air filter market is driven by regional industrial hubs and key manufacturing centers, with major demand concentrated in urbanized and industrialized regions such as Seoul, Gyeonggi, Busan, and Daegu. These areas have a high concentration of vehicle ownership, automotive production facilities, and aftermarket service providers, contributing to the steady demand for cabin and engine air filters. The market is highly competitive, with the presence of both domestic and international manufacturers focusing on technological advancements, eco-friendly materials, and high-performance filtration systems. Key players such as Roki Co., Ltd., Toyota Boshoku Corporation, Guangzhou Yifeng Auto Parts Co., Ltd., Bengbu Jinwei Filters Co., Ltd., and Zhejiang Universe Filter Co., Ltd. are actively investing in research and development to enhance filter efficiency and durability. Additionally, the rising adoption of electric and hybrid vehicles is pushing manufacturers to develop advanced air purification solutions, ensuring continued market expansion.
Market Insights
- The South Korea automotive air filter market was valued at USD 194.970 million in 2024 and is projected to reach USD 326.673 million by 2032, growing at a CAGR of 6.66% during the forecast period.
- Increasing vehicle ownership and rising concerns about air pollution and in-cabin air quality are driving demand for advanced automotive air filters.
- The growing adoption of electric and hybrid vehicles is fueling the need for high-efficiency cabin air filters with HEPA and activated carbon technology.
- Leading manufacturers are investing in technological advancements to develop eco-friendly and long-lasting air filters that offer superior filtration and durability.
- The market faces challenges due to the high cost of premium air filters and the availability of low-cost counterfeit products in the aftermarket.
- Seoul, Gyeonggi, Busan, and Daegu are the key regional markets, driven by vehicle production and strong consumer demand.
- Major players, including Roki Co., Ltd. and Toyota Boshoku Corporation, are expanding their product portfolios to maintain a competitive edge.
Market Drivers
Stringent Emission Regulations Driving Market Growth
The South Korea automotive air filter market is witnessing significant growth due to the implementation of stringent emission regulations. The government has enforced strict policies to reduce vehicular emissions, compelling automakers to integrate high-efficiency air filters in their vehicles. For instance, the transition from Euro 5 to Euro 6 standards has necessitated the use of advanced after-treatment technologies, such as diesel particulate filters, which require high-quality air filtration systems to maintain efficiency and reduce emissions. Regulations such as Euro 6 and South Korea's Clean Air Conservation Act have led to an increased demand for advanced air filtration systems that enhance engine performance while minimizing environmental impact. These regulations aim to limit the release of particulate matter and nitrogen oxides, making it essential for vehicles to adopt high-quality engine and cabin air filters. As a result, automotive manufacturers are continuously upgrading their filtration technologies to comply with evolving standards, fueling market expansion. Additionally, regulatory bodies are encouraging research and development in eco-friendly air filter solutions, further boosting innovation and market growth.
Increasing Vehicle Production and Fleet Expansion
The rising production of automobiles and the expansion of the vehicle fleet are key drivers of the South Korea automotive air filter market. The country is home to major automobile manufacturers such as Hyundai, Kia, and Renault Korea Motors, which are continuously increasing their production capacities to meet growing domestic and international demand. For example, Hyundai and Kia have expanded their production lines to accommodate the growing demand for passenger and commercial vehicles, directly increasing the need for engine and cabin air filters. The increasing number of passenger and commercial vehicles on the roads has directly boosted the need for engine and cabin air filters to maintain optimal vehicle performance. Furthermore, the expansion of ride-hailing and logistics services has increased the operational lifespan of vehicles, necessitating frequent air filter replacements. As consumers prioritize fuel efficiency and engine longevity, the demand for high-performance air filters continues to rise. Additionally, the growing preference for electric and hybrid vehicles is leading to the development of specialized air filtration systems tailored for these vehicles, further driving market growth.
Rising Consumer Awareness of Air Quality and Health Benefits
Growing concerns over air pollution and its adverse effects on human health have significantly influenced consumer preferences in South Korea. Urbanization and industrialization have led to increased air pollution levels, prompting vehicle owners to invest in high-quality cabin air filters that provide clean and purified air inside vehicles. The demand for advanced filtration solutions, such as HEPA and activated carbon filters, has surged as consumers seek protection against allergens, pollutants, and harmful airborne particles. Additionally, the COVID-19 pandemic heightened awareness of respiratory health, further driving the adoption of premium cabin air filters that offer enhanced filtration efficiency. As consumers become more informed about the role of air filters in maintaining a healthier in-car environment, manufacturers are focusing on developing technologically advanced filters with antimicrobial and anti-allergen properties, ensuring sustained market demand.
Technological Advancements and Aftermarket Growth
Continuous advancements in air filtration technologies are playing a crucial role in the expansion of the South Korea automotive air filter market. Innovations in nanotechnology and synthetic fiber materials have improved filter efficiency, durability, and overall performance. Manufacturers are investing in research and development to create next-generation filters that provide superior filtration while extending replacement intervals. Additionally, the rise of e-commerce platforms and the growing automotive aftermarket sector have made it easier for consumers to access high-quality air filters. Online sales channels and authorized service centers are expanding their product offerings, allowing vehicle owners to purchase and replace filters conveniently. The availability of customizable and high-efficiency air filters for different vehicle models has further strengthened aftermarket demand. As a result, both OEM and aftermarket sales channels are contributing to the overall growth of the automotive air filter market in South Korea.
Market Trends
Growing Adoption of High-Efficiency Particulate Air (HEPA) and Activated Carbon Filters
The demand for advanced air filtration solutions is rising in South Korea, with HEPA and activated carbon filters gaining widespread adoption. Consumers are increasingly prioritizing air quality inside vehicles due to rising pollution levels and health concerns. For instance, the South Korean government's emphasis on improving indoor air quality has led to increased consumer awareness about the benefits of HEPA filters, which are known for their ability to trap fine particulate matter, allergens, and airborne pollutants. Similarly, activated carbon filters are gaining popularity for their effectiveness in eliminating odors, harmful gases, and volatile organic compounds (VOCs). Automotive manufacturers are integrating these advanced filtration technologies into cabin air filters to enhance passenger comfort and safety. The rising awareness of respiratory health, especially post-COVID-19, is further accelerating the adoption of these high-efficiency filters, driving innovation in air purification systems for vehicles.
Increasing Demand for Electric Vehicle (EV) Air Filtration Systems
As South Korea continues to expand its electric vehicle (EV) market, the demand for specialized air filtration systems tailored for EVs is increasing. Unlike internal combustion engine (ICE) vehicles, EVs do not require traditional engine air filters, but they still require high-quality cabin air filters to maintain air purity. For example, Hyundai and Kia have been investing in the development of advanced cabin air filtration systems for their EV models, focusing on multi-layered filtration systems and smart air filters that adapt to real-time air quality conditions. Innovations include these advanced filtration technologies that cater to EV-specific requirements. Additionally, as EV adoption grows, manufacturers are investing in research to improve the longevity and efficiency of air filters, ensuring enhanced passenger comfort and environmental sustainability. This trend is expected to shape the future of air filtration solutions in South Korea’s automotive industry.
Rising Popularity of Smart and IoT-Enabled Air Filters
Technological advancements are revolutionizing the South Korean automotive air filter market, with the introduction of smart and IoT-enabled filtration systems. These next-generation air filters come equipped with sensors that monitor air quality in real time and provide alerts when replacements are needed. Some smart air filters can automatically adjust filtration efficiency based on external air conditions, ensuring optimal performance. Automakers are integrating these intelligent filtration solutions into high-end vehicles to enhance user convenience and improve overall air quality management. The growing consumer preference for connected and automated vehicle features is driving investments in smart filtration technology, paving the way for further advancements in this segment. As digital transformation accelerates in the automotive sector, the adoption of IoT-enabled air filters is expected to gain momentum.
Expansion of the Aftermarket and E-Commerce Sales Channels
The South Korean automotive air filter market is witnessing a surge in aftermarket demand, driven by increased vehicle ownership and growing awareness of periodic air filter replacements. Consumers are actively seeking high-performance air filters through both traditional service centers and online platforms. The expansion of e-commerce channels has made it easier for vehicle owners to purchase and replace air filters conveniently. Major aftermarket brands are leveraging digital platforms to offer customized filter solutions, ensuring compatibility with various vehicle models. Additionally, the rising trend of do-it-yourself (DIY) vehicle maintenance is encouraging consumers to buy aftermarket air filters online. As online retail platforms continue to expand their product offerings and delivery networks, the accessibility and affordability of automotive air filters are expected to improve, further driving market growth.
Market Challenges Analysis
Intense Competition and Price Sensitivity Restraining Market Growth
The South Korea automotive air filter market faces challenges due to intense competition among domestic and international manufacturers. The presence of numerous players has led to price wars, making it difficult for companies to maintain profit margins while delivering high-quality products. For instance, the proliferation of counterfeit and low-quality air filters in the market has forced legitimate manufacturers to invest in anti-counterfeiting measures and quality certifications to differentiate their products. Consumers often prioritize cost-effective solutions, creating pressure on manufacturers to balance affordability with performance. Additionally, counterfeit and low-quality air filters flooding the market pose a significant challenge, as they undermine consumer trust and impact sales of genuine products. The availability of cheaper alternatives in the aftermarket segment further intensifies competition, forcing manufacturers to adopt aggressive pricing strategies. To overcome these challenges, companies must focus on differentiating their products through technological innovations, superior filtration efficiency, and extended durability. Furthermore, increased consumer awareness of the long-term benefits of high-performance air filters could help shift the market toward quality-driven purchasing decisions.
Limited Consumer Awareness and Replacement Frequency Concerns
Despite the growing demand for air filters, many vehicle owners in South Korea remain unaware of the importance of regular air filter replacement. Neglected or clogged air filters can reduce engine efficiency, increase fuel consumption, and compromise cabin air quality, yet many consumers delay replacements due to a lack of awareness or perceived cost concerns. This challenge is particularly evident in the aftermarket segment, where non-specialist retailers and service providers may not emphasize the necessity of timely filter changes. Additionally, some consumers opt for extended replacement intervals to save costs, leading to potential vehicle performance issues in the long run. To address this, manufacturers and automotive service providers must strengthen educational initiatives through marketing campaigns, service reminders, and digital engagement strategies. Promoting the benefits of routine air filter maintenance and highlighting the impact on vehicle longevity and health can encourage more frequent replacements, supporting sustainable market growth.
Market Opportunities
The South Korea automotive air filter market presents significant growth opportunities driven by advancements in filtration technology and increasing demand for premium air purification solutions. The rising adoption of electric and hybrid vehicles is creating a need for specialized air filtration systems tailored to these models. Unlike traditional internal combustion engine (ICE) vehicles, EVs rely heavily on high-efficiency cabin air filters to enhance passenger comfort and safety. Manufacturers can capitalize on this shift by developing advanced filtration technologies, such as multi-layered HEPA and activated carbon filters, to meet the evolving needs of EV consumers. Additionally, integrating smart and IoT-enabled air filters that monitor air quality in real time can enhance product differentiation and drive demand among tech-savvy consumers. As automakers focus on enhancing in-vehicle air quality, suppliers of high-performance air filters have an opportunity to collaborate with original equipment manufacturers (OEMs) and establish long-term supply agreements.
The expansion of e-commerce and the growing aftermarket sector further contribute to market opportunities by improving accessibility and consumer engagement. With more vehicle owners opting for online purchases, companies can leverage digital platforms to expand their reach and offer customized air filtration solutions for different vehicle models. The increasing trend of do-it-yourself (DIY) vehicle maintenance also presents an opportunity for aftermarket brands to provide easy-to-install air filters with extended durability and enhanced efficiency. Additionally, growing consumer awareness regarding air pollution and its health implications is expected to boost demand for premium cabin air filters. Manufacturers who emphasize product innovation, eco-friendly materials, and enhanced filtration capabilities can strengthen their market position. By focusing on strategic partnerships, technological advancements, and digital marketing initiatives, companies can capitalize on the evolving automotive air filter market in South Korea and drive long-term growth.
Market Segmentation Analysis:
By Type:
The South Korea automotive air filter market is segmented into cabin air filters and engine air filters, both of which play a crucial role in enhancing vehicle performance and passenger comfort. Cabin air filters are witnessing significant demand growth due to rising consumer awareness of air quality inside vehicles. With increasing pollution levels and health concerns, vehicle owners are prioritizing high-efficiency cabin air filters, such as HEPA and activated carbon filters, to protect against allergens, pollutants, and harmful airborne particles. Automakers are integrating advanced filtration systems into modern vehicles, further driving demand for premium cabin air filters. On the other hand, engine air filters remain essential for maintaining optimal fuel efficiency and engine performance by preventing dust, debris, and contaminants from entering the engine. The increasing production of passenger and commercial vehicles in South Korea, coupled with stringent emission regulations, is fueling the demand for high-performance engine air filters that enhance fuel economy and reduce emissions, ensuring long-term market growth.
By Material:
Based on material, the market is categorized into paper, foam, and synthetic air filters, each offering distinct advantages in terms of filtration efficiency and durability. Paper-based air filters dominate the market due to their cost-effectiveness, widespread adoption, and ease of replacement. These filters provide efficient particle filtration, making them the preferred choice for both cabin and engine air filtration systems. However, foam air filters are gaining popularity, particularly in high-performance and off-road vehicles, due to their enhanced dust-holding capacity and reusability. These filters offer longer service life and improved airflow, making them ideal for demanding environments. Synthetic air filters, made from advanced fiber materials, are experiencing growing demand due to their superior filtration capabilities and durability. They provide high resistance to moisture and contaminants, ensuring extended filter life and reduced maintenance costs. As vehicle owners seek long-lasting and efficient air filtration solutions, the adoption of synthetic and foam-based filters is expected to increase, contributing to the overall growth of the South Korea automotive air filter market.
Segments:
Based on Type:
- Cabin Air Filter
- Engine Air Filter
Based on Material:
- Paper
- Foam
- Synthetic
Based on Vehicle:
- Passenger Cars
- Light Commercial Vehicles (LCVs)
- Heavy Commercial Vehicles (HCVs)
Based on Distribution Channel:
- OEMs
- Aftermarket
Based on the Geography:
- Seoul Metropolitan Region
- Gyeonggi Province
- Busan and Ulsan Regions
- Daegu Region
Regional Analysis
Seoul Metropolitan Region
The Seoul Metropolitan Region holds the largest share of the South Korea automotive air filter market, accounting for approximately 35% of total market revenue. As the most densely populated and economically developed area, Seoul has a high concentration of passenger vehicles, commercial fleets, and premium car owners who prioritize advanced air filtration systems. The rising concerns about urban air pollution and respiratory health issues have accelerated the adoption of HEPA and activated carbon cabin air filters, particularly in high-end and electric vehicles. Additionally, stringent vehicle emissions regulations in Seoul drive the demand for high-performance engine air filters to enhance fuel efficiency and reduce emissions. The growing electric vehicle (EV) market in Seoul further contributes to market expansion, with leading automakers focusing on integrating smart and IoT-enabled air filters to improve air quality monitoring inside vehicles. This sustained demand is expected to reinforce Seoul’s position as the dominant regional market for automotive air filters in South Korea.
Gyeonggi Province
Gyeonggi Province holds the second-largest share of the South Korea automotive air filter market, contributing approximately 28% to overall industry revenues. This region is home to major automotive manufacturing plants, industrial hubs, and a growing population of vehicle owners, making it a crucial market for both OEM and aftermarket air filter sales. With a substantial number of commuters traveling between Seoul and Gyeonggi, the demand for high-quality cabin air filters remains strong, driven by increased exposure to road dust, exhaust fumes, and fine particulate matter (PM2.5). Additionally, the presence of major industrial zones results in higher air pollution levels, prompting vehicle owners to opt for advanced air filtration solutions. The increasing fleet of commercial vehicles and public transportation in the province further fuels demand for durable engine air filters that enhance performance and extend engine life. Given its strategic location and industrial significance, Gyeonggi Province continues to be a major growth driver for the South Korean automotive air filter market.
Busan and Ulsan Regions
The Busan and Ulsan regions collectively hold a 20% share of the automotive air filter market, benefiting from their role as major port cities and industrial centers. Busan, as South Korea’s largest port, experiences high commercial vehicle density, leading to sustained demand for heavy-duty engine air filters that can withstand harsh operating conditions. Meanwhile, Ulsan, home to Hyundai’s largest automobile manufacturing plant, contributes significantly to the OEM air filter market. The increasing production of both internal combustion engine (ICE) vehicles and electric vehicles (EVs) in these regions boosts the demand for high-performance cabin and engine air filters. Additionally, Busan’s rapidly growing urban population and expanding vehicle ownership support the adoption of premium cabin air filters that improve air quality inside vehicles. As the manufacturing and transportation sectors continue to grow, the Busan-Ulsan region is expected to maintain a strong position in the South Korean automotive air filter market.
Daegu Region
The Daegu region accounts for 17% of South Korea’s automotive air filter market, driven by its automotive component manufacturing industry and rising vehicle ownership rates. Known for its strong presence in the automotive supply chain, Daegu serves as a key production hub for engine components, air filtration systems, and other vehicle parts. This industrial expertise has resulted in an increasing demand for high-performance and specialized air filters, particularly in the commercial vehicle segment. Additionally, as air quality concerns grow, consumers in Daegu are shifting toward multi-layered and synthetic cabin air filters that offer better filtration efficiency and longer replacement cycles. The expansion of the e-commerce sector in Daegu is also contributing to market growth, as more consumers purchase aftermarket air filters online for DIY maintenance. With continued advancements in automotive technology and air filtration solutions, Daegu’s role in the South Korean automotive air filter market is expected to expand in the coming years.
Key Player Analysis
- Roki Co., Ltd.
- Toyota Boshoku Corporation
- Guangzhou Yifeng Auto Parts Co., Ltd.
- Bengbu Jinwei Filters Co., Ltd.
- Zhejiang Universe Filter Co., Ltd.
- Sakura Filter Industries Co., Ltd.
- Dongguan Shenglian Filter Manufacturing Co., Ltd.
- YBM Group
- Airmatic Filterbau GmbH
Competitive Analysis
The South Korea automotive air filter market is highly competitive, with several key players focusing on product innovation, strategic partnerships, and expansion to strengthen their market presence. Leading companies such as Roki Co., Ltd., Toyota Boshoku Corporation, Guangzhou Yifeng Auto Parts Co., Ltd., Bengbu Jinwei Filters Co., Ltd., Zhejiang Universe Filter Co., Ltd., Sakura Filter Industries Co., Ltd., Dongguan Shenglian Filter Manufacturing Co., Ltd., YBM Group, and Airmatic Filterbau GmbH are actively investing in R&D to develop high-performance filtration solutions that enhance engine efficiency and improve in-cabin air quality. These companies emphasize advanced filtration technologies, including HEPA, activated carbon, and synthetic filters, to meet rising consumer demand for better air purification and emission control. Additionally, manufacturers are expanding their aftermarket services and OEM collaborations to capture a larger share of the growing automotive industry. However, intense price competition and the presence of counterfeit products challenge market growth. To maintain their competitive edge, leading players focus on technological advancements, sustainable filter materials, and efficient distribution networks, ensuring long-term profitability in the evolving South Korea automotive air filter market.
Recent Developments
- In January 2025, Donaldson Company, Inc. partnered with Daimler Truck North America to feature its advanced air filter technology in the Freightliner SuperTruck III, a hydrogen fuel cell truck project.
- In January 2025, Freudenberg Filtration Technologies introduced the "micronAir Gas Shield" line, a premium activated carbon selection for automotive cabin air filters, offering regionally customized options to adsorb harmful gases and odors.
- In July 2024, Mann+Hummel launched nanofiber-based cabin air filters, known as Mann-Filter FreciousPlus, which effectively filter ultra-fine particles and pollutants.
- In January 2024, Robert Bosch GmbH replaced the FILTER+ cabin air filter with the enhanced FILTER+pro, offering improved filtration performance and reduced germ transmission.
Market Concentration & Characteristics
The South Korea automotive air filter market exhibits a moderate to high market concentration, with a mix of established global players and domestic manufacturers competing for market share. Leading companies focus on technological innovation, product differentiation, and OEM partnerships to strengthen their position. The market is characterized by a strong emphasis on quality, efficiency, and environmental sustainability, with increasing demand for high-performance filters made from synthetic and eco-friendly materials. Additionally, the presence of strict emission regulations and rising consumer awareness about air quality has led to the development of advanced filtration solutions, including HEPA and activated carbon filters. While premium filters dominate the OEM segment, the aftermarket sector remains highly fragmented, with numerous regional suppliers offering cost-effective alternatives. The competitive landscape continues to evolve as companies expand their distribution networks, invest in R&D, and adopt sustainable manufacturing practices, ensuring steady growth in the South Korea automotive air filter market.
Report Coverage
The research report offers an in-depth analysis based on Type, Material, Vehicle, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The South Korea automotive air filter market is expected to witness steady growth, driven by increasing vehicle sales and rising air pollution concerns.
- Advancements in filtration technology will lead to the development of high-efficiency air filters with improved durability and performance.
- Growing adoption of electric and hybrid vehicles will boost demand for advanced cabin air filters with HEPA and activated carbon technology.
- Stricter emission regulations will encourage automakers to integrate superior engine air filters to enhance fuel efficiency and reduce pollutants.
- Expansion of the automotive aftermarket sector will create opportunities for cost-effective and high-performance air filters.
- Manufacturers will focus on sustainable and eco-friendly filter materials to align with global environmental policies.
- Increasing consumer awareness about in-cabin air quality will drive the demand for premium and smart air filtration systems.
- Strategic collaborations between OEMs and filter manufacturers will strengthen supply chains and enhance product innovation.
- The rise of e-commerce platforms will expand accessibility to aftermarket air filters, boosting sales across urban and rural areas.
- Competition among key players will intensify, leading to continuous advancements in filtration efficiency and product differentiation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the South Korea Automotive Air Filter market?
What factors are driving the growth of the South Korea Automotive Air Filter market?
What are the key segments within the South Korea Automotive Air Filter market?
What are some challenges faced by the South Korea Automotive Air Filter market?
Who are the major players in the South Korea Automotive Air Filter market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 South Korea Automotive Air Filter Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global South Korea Automotive Air Filter Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 194.970 million → 2032: USD 326.673 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 South Korea Automotive Air Filter Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. South Korea Automotive Air Filter Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 South Korea Automotive Air Filter Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 South Korea Automotive Air Filter Market Drivers
- 3.3 South Korea Automotive Air Filter Market Restraints & Challenges
- 3.4 South Korea Automotive Air Filter Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 South Korea Automotive Air Filter Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 South Korea Automotive Air Filter Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, South Korea Automotive Air Filter category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 South Korea Automotive Air Filter Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. South Korea Automotive Air Filter Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the South Korea Automotive Air Filter market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 South Korea Automotive Air Filter Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 South Korea Automotive Air Filter Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 South Korea Automotive Air Filter Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in South Korea Automotive Air Filter (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New South Korea Automotive Air Filter Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global South Korea Automotive Air Filter Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America South Korea Automotive Air Filter Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe South Korea Automotive Air Filter Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific South Korea Automotive Air Filter Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America South Korea Automotive Air Filter Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East South Korea Automotive Air Filter Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa South Korea Automotive Air Filter Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. South Korea Automotive Air Filter Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
