
Market Overview
The South Korea Data Centre Market is projected to grow from USD 9,664.57 million in 2024 to an estimated USD 16,674.08 million based on 2032, with a compound annual growth rate (CAGR) 7.06% from 2025 to 2032. This growth reflects the country’s rising dependence on cloud computing, artificial intelligence (AI), and big data analytics.| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| South Korea Data Centre Market Size 2024 | USD 9,664.57 million |
| South Korea Data Centre Market, CAGR | 7.06% |
| South Korea Data Centre Market Size 2032 | USD 16,674.08 million |
Market Insights
- The South Korea Data Centre Market is projected to grow from USD9,664.57 million in 2024 to USD16,674.08 million by 2032, with a CAGR of 7.06% from 2025 to 2032, driven by digital transformation and increasing data demands.
- Key drivers include the rising adoption of cloud computing, the integration of 5G technology, rapid digitalization across industries, and government support for smart city initiatives and enhanced cybersecurity infrastructure.
- Cloud services are central to the market's growth, as businesses increasingly migrate to cloud environments to optimize costs, scalability, and performance for critical data storage and processing.
- Edge computing is expanding rapidly to meet the low-latency requirements of IoT, 5G, and real-time applications, leading to greater investments in distributed data centre infrastructure across South Korea.
- There is a growing emphasis on green data centres powered by renewable energy, driven by both government policies and market demand for sustainable, energy-efficient infrastructure.
- Seoul remains the primary data centre hub, while Gyeonggi and Incheon are emerging as secondary markets due to lower costs and increased infrastructure development to support growing demand.
- Challenges include limited land availability and power constraints in urban areas, as well as complex regulatory compliance and high operational costs, which may hinder the scalability of new data centre projects.
Report Scope
This report segments the South Korea Data Centre Market as follows: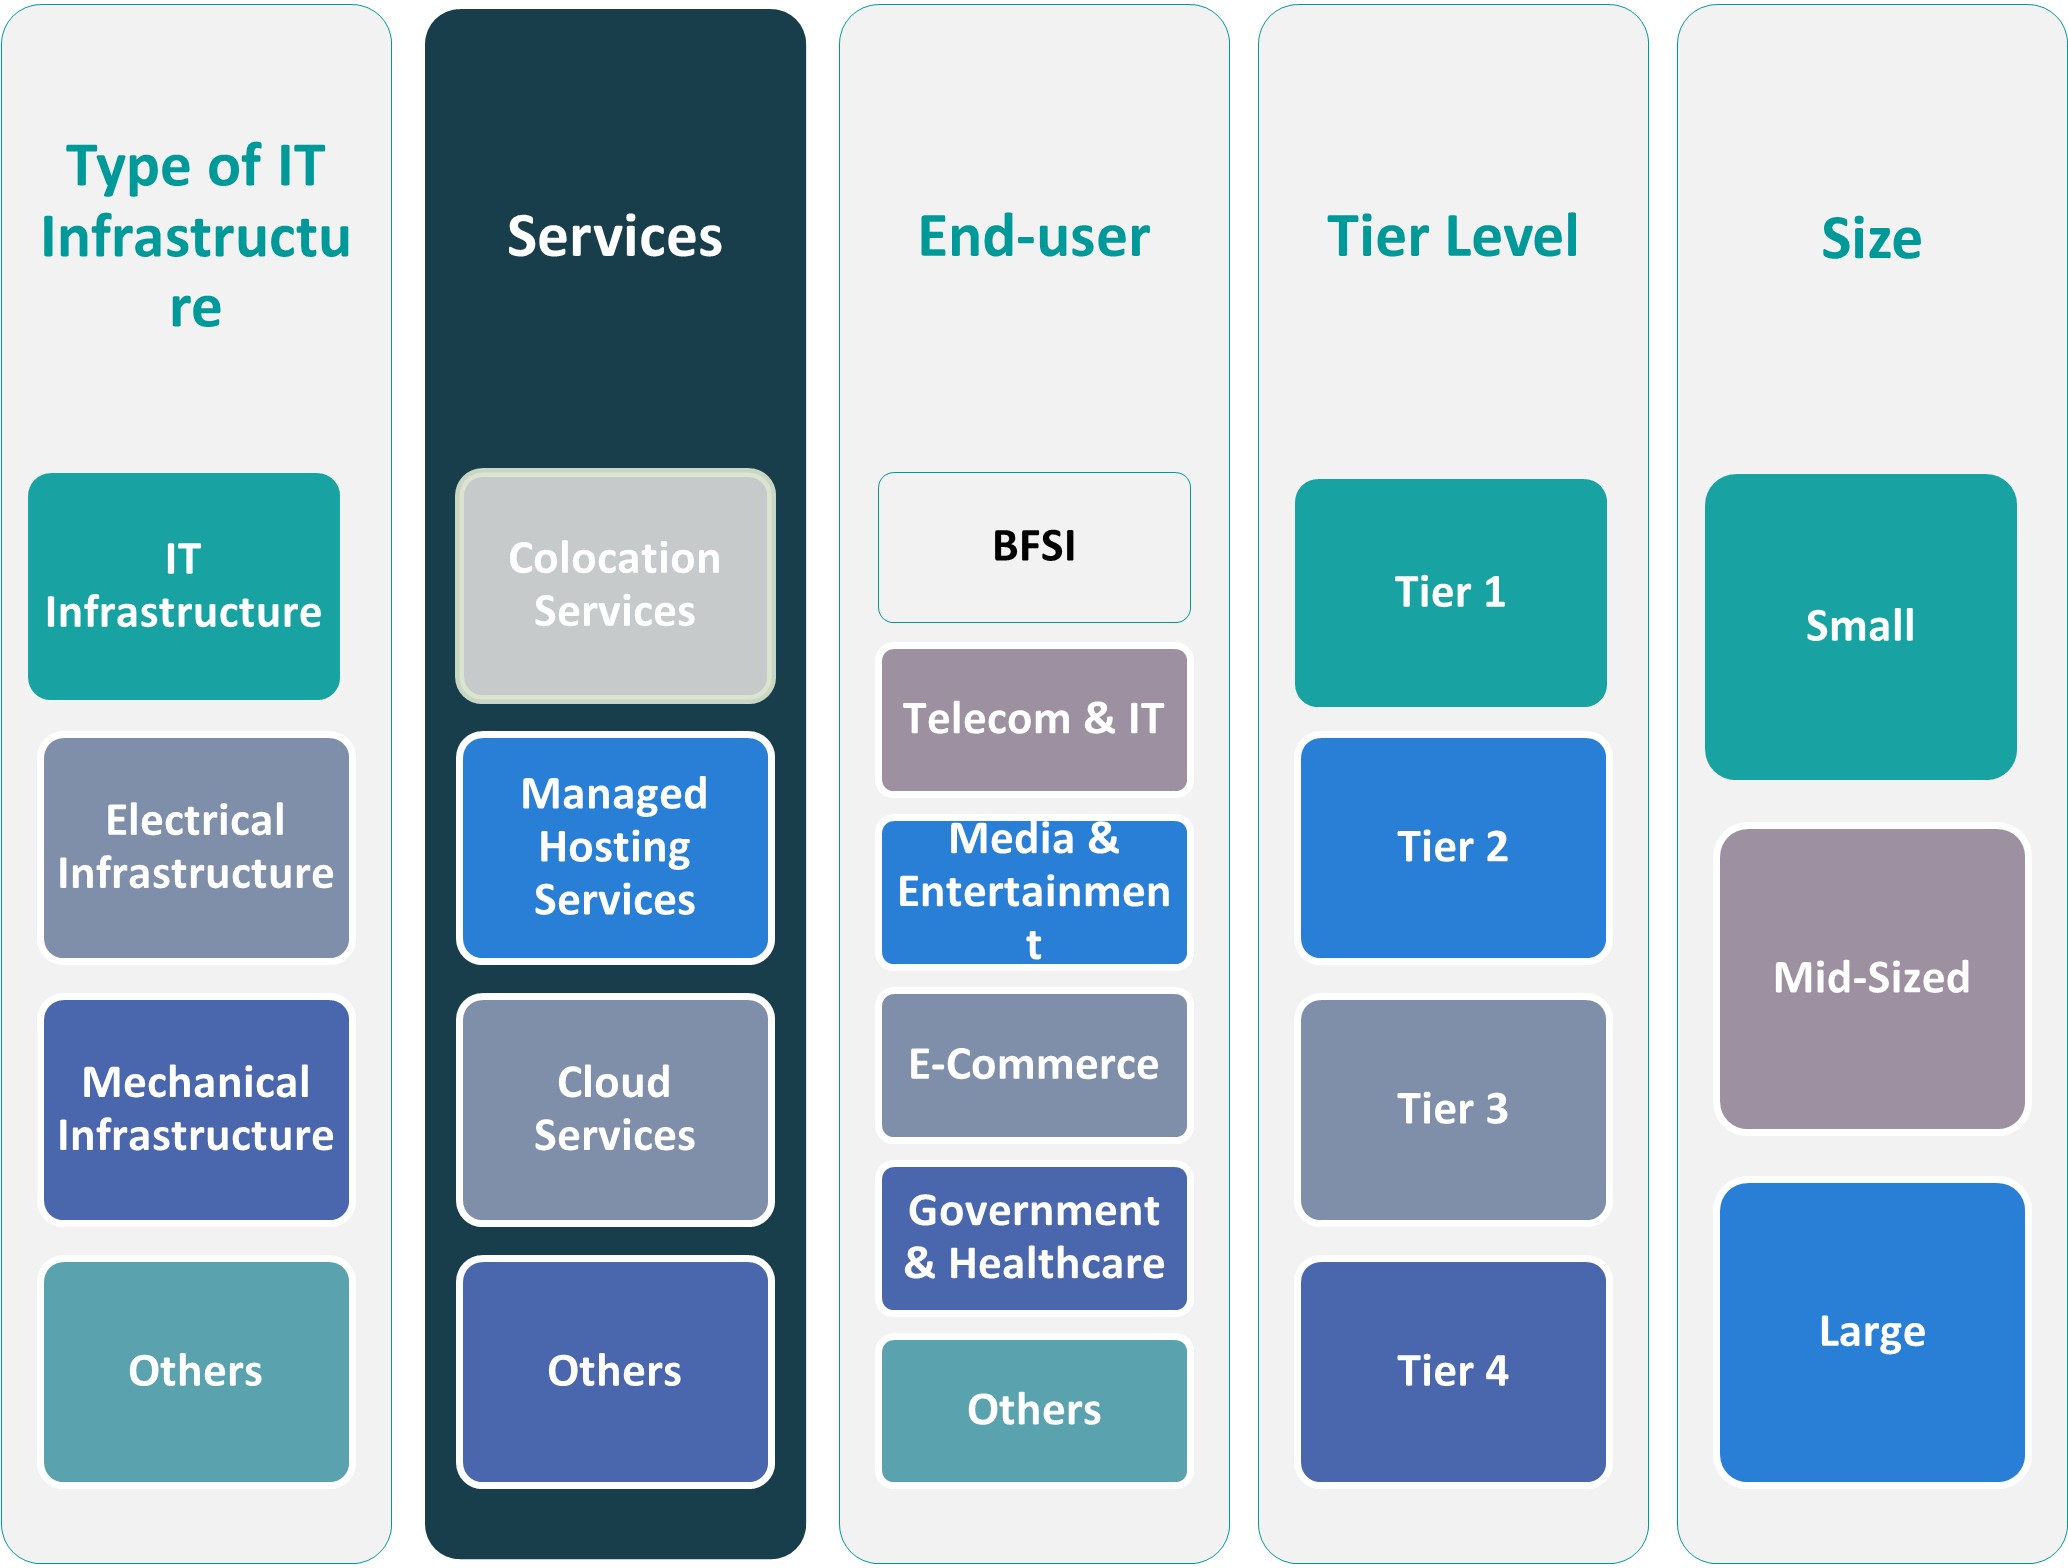
Market Drivers
Rapid Digital Transformation and Cloud Adoption
The South Korea data centre market is significantly driven by the rapid pace of digital transformation across both public and private sectors. Enterprises are increasingly adopting cloud computing models to support scalable operations, reduce IT infrastructure costs, and enhance system agility. Cloud service providers, including global leaders like Amazon Web Services, Microsoft Azure, and Google Cloud, are expanding their regional footprint in South Korea due to rising demand. The shift to hybrid and multi-cloud environments, particularly in finance, healthcare, retail, and manufacturing industries, has led to a surge in demand for high-performance, secure, and scalable data centre infrastructure. Moreover, digitalization of government services under initiatives like “Digital New Deal” has further spurred the construction of new data centres to accommodate the growing volume of public sector data. For instance, South Korea had 50.4 million internet users in early 2025, with an online penetration rate of 97.4%. This structural shift toward cloud and data-intensive technologies ensures a continuous pipeline of investment into hyperscale and colocation data centres.Strong Government Support and Regulatory Initiatives
Government-led initiatives and favorable regulatory frameworks play a crucial role in driving the growth of the South Korea data centre market. The South Korean government is actively promoting digital infrastructure as a strategic asset through its “K-Digital Strategy,” which emphasizes AI development, 5G commercialization, and national data sovereignty. These efforts aim to reinforce the country’s status as a digital powerhouse and data hub in the Asia Pacific region. The government also offers tax benefits and infrastructure support for companies investing in energy-efficient and green data centres. Additionally, data protection laws such as the Personal Information Protection Act (PIPA) and guidelines on data localisation are pushing businesses to establish or co-locate their servers within South Korea, thereby contributing to rising demand for in-country data centre facilities. For instance, South Korea had 69.2 million cellular mobile connections in early 2025, equivalent to 134% of the total population. These policy measures ensure that data security and compliance remain central to market expansion.Deployment of 5G and Edge Computing Technologies
The commercial rollout of 5G technology in South Korea has substantially impacted the data centre landscape. With one of the world's fastest 5G adoption rates, the country is experiencing a surge in data generation from mobile devices, IoT applications, autonomous vehicles, and smart city deployments. This data-intensive environment requires low-latency infrastructure capable of processing information in near real-time, prompting the need for edge data centres across urban and semi-urban regions. Edge computing solutions reduce network congestion and enhance responsiveness for critical applications, including telemedicine, remote learning, and industrial automation. As telcos and infrastructure providers expand 5G networks, there is parallel investment in regional data centres to support localized computing needs. This integration of 5G with edge and core data centres is expected to redefine workload management and enable real-time service delivery across sectors.Focus on Green Data Centres and Sustainability
Environmental sustainability has emerged as a key growth driver in the South Korea data centre market. As global climate change pressures intensify, businesses and governments are prioritizing the development of eco-friendly infrastructure. Energy-efficient data centres that utilize renewable energy sources, advanced cooling systems, and AI-based energy management solutions are gaining traction. South Korea’s commitment to carbon neutrality by 2050, combined with growing stakeholder emphasis on ESG (Environmental, Social, Governance) compliance, is encouraging investments in green data centre projects. Moreover, leading data centre operators are partnering with utility providers and technology vendors to develop sustainable power supply chains, such as leveraging solar and wind energy. Innovations in immersion cooling and waste heat recovery are also being explored to reduce energy consumption. These green initiatives not only align with global best practices but also attract international clients seeking environmentally responsible data storage solutions. As sustainability becomes a key procurement criterion, green data centres are poised to become mainstream in South Korea’s digital infrastructure landscape.Market Trends
Expansion of Hyperscale Data Centres
One of the most prominent trends in the South Korea data centre market is the rapid expansion of hyperscale facilities. As demand for cloud services, big data analytics, and high-performance computing accelerates, both global and domestic providers are investing heavily in hyperscale infrastructures. Major players such as Google, AWS, Microsoft, and Naver Cloud are either expanding their existing campuses or developing new hyperscale projects to meet growing workload requirements. For instance, South Korea’s data centre market saw significant investment in 2024, with hyperscale providers allocating billions of won toward infrastructure expansion. These facilities offer vast capacity, scalable resources, and operational efficiency, making them ideal for handling AI applications, streaming services, and enterprise-level cloud operations. Additionally, hyperscale data centres benefit from economies of scale and are designed to accommodate modular expansion, allowing service providers to adjust capacity in line with demand. The ongoing digital transformation of sectors like finance, education, and manufacturing continues to fuel this trend, reinforcing South Korea’s position as a strategic data hub in the Asia Pacific region.Surge in Edge Data Centre Deployments
Driven by the widespread rollout of 5G and IoT technologies, South Korea is witnessing an increase in edge data centre deployments. These smaller, decentralized facilities are strategically located closer to end-users and devices to minimize latency and support real-time data processing. For instance, telecommunications providers like SK Telecom and KT Corporation have invested heavily in edge computing nodes alongside their 5G infrastructure. Edge data centres are becoming essential to power applications such as autonomous vehicles, remote healthcare, AR/VR platforms, and smart factory operations. Moreover, edge centres enable efficient bandwidth utilization by processing data locally, reducing reliance on central data facilities. This trend is particularly relevant in urban environments such as Seoul and Busan, where data consumption and connected device density are extremely high. As real-time data processing becomes critical for user experience and operational efficiency, edge data centres are set to play an increasingly central role in the country’s IT ecosystemIncreased Investment in Renewable Energy and Sustainable Practices
Sustainability is emerging as a core focus area in the South Korea data centre market, prompting a rise in green data centre development. Data centre operators are aligning their infrastructure with global ESG goals and South Korea’s national carbon neutrality commitment for 2050. Companies are investing in renewable energy sources, such as solar and wind, to power their facilities, and exploring innovative cooling techniques like liquid immersion and free-air cooling to minimize energy usage. Partnerships between tech firms and utility companies are being established to ensure access to clean energy grids and optimize power procurement. Additionally, operators are incorporating AI-driven energy management systems to monitor and reduce power consumption across server farms. This green shift not only addresses environmental concerns but also improves brand reputation and attracts clients seeking sustainable IT solutions. As regulatory bodies place more emphasis on emissions standards, the trend toward energy-efficient, low-carbon data centres will continue to reshape infrastructure development in South Korea.Integration of Artificial Intelligence and Automation
Artificial Intelligence (AI) and automation technologies are becoming integral to the operation and management of modern data centres in South Korea. Operators are deploying AI-driven tools for predictive maintenance, intelligent workload distribution, and real-time monitoring of environmental conditions like temperature and humidity. These capabilities help reduce operational costs, prevent downtime, and improve energy efficiency. Automation is also streamlining routine processes such as server provisioning, network optimization, and security management. The integration of robotic process automation (RPA) and machine learning further enhances data centre agility by enabling dynamic resource allocation based on real-time usage patterns. As workloads become more complex with the proliferation of AI and machine learning applications themselves, data centres are evolving into intelligent ecosystems capable of self-optimization. This trend is especially critical for hyperscale and colocation centres managing diverse client needs and fluctuating traffic loads. By embracing AI and automation, South Korean data centres are setting benchmarks for operational excellence, scalability, and responsiveness in a digitally connected economy.Market Challenges
Land and Power Constraints in Urban Hubs
One of the major challenges facing the South Korea data centre market is the scarcity of suitable land and reliable power supply in densely populated urban areas such as Seoul and its surrounding regions. As demand for large-scale data centre facilities increases, operators struggle to secure sufficient real estate that meets zoning, accessibility, and infrastructure requirements. High property costs and regulatory limitations further complicate the establishment of new data centres in metropolitan zones. According to industry reports, Korea Electric Power Corp. (KEPCO) now takes approximately 12 months to confirm power supply for new data centre projects, compared to 2-3 months previously. Additionally, the immense power consumption required for running and cooling modern data centres places a considerable strain on local grids. South Korea’s energy mix, which remains heavily reliant on fossil fuels and nuclear power, poses concerns regarding sustainable power availability and grid stability. In response, the Korean government passed three legislations in 2024 to stabilize the sector, including new operational requirements for large digital service providers and data centre operators. These limitations hinder the scalability of data centre operations, delay project timelines, and elevate operational costs. As the market matures, the need for collaborative urban planning, energy infrastructure upgrades, and regional data centre diversification becomes increasingly critical to support long-term growth.Stringent Regulatory Compliance and Data Sovereignty Issues
The evolving regulatory landscape in South Korea, particularly concerning data protection and sovereignty, presents a complex challenge for both domestic and international data centre operators. Laws such as the Personal Information Protection Act (PIPA) impose strict compliance requirements for the collection, storage, and processing of personal data. Additionally, mandates regarding the physical localization of sensitive data restrict cross-border data flows, creating barriers for multinational cloud service providers and enterprises with global operations. Operators must invest heavily in regulatory expertise, data governance frameworks, and compliance systems to meet these legal obligations. Non-compliance can lead to significant penalties, reputational damage, and operational disruptions. Furthermore, the fast-changing nature of digital regulations necessitates continuous monitoring and adaptation, increasing the cost and complexity of doing business in the data centre sector. Balancing innovation and compliance remains a key challenge that could limit market agility and affect foreign investment.Market Opportunities
Growth in Cloud Computing and AI Demand
The rapid adoption of cloud computing and the increasing demand for Artificial Intelligence (AI) applications present significant growth opportunities for the South Korea data centre market. As businesses across sectors such as finance, healthcare, and manufacturing shift towards cloud-first strategies, there is a heightened need for robust data storage, processing, and security solutions. Additionally, AI-driven applications, including machine learning, big data analytics, and deep learning, require scalable, high-performance computing infrastructure. Data centres that can offer the necessary resources to support these advanced technologies, such as high-density storage, low-latency processing, and secure environments, are in high demand. Cloud service providers, both global and local, are increasingly expanding their operations in South Korea to cater to this growing market, presenting opportunities for data centre operators to offer colocation, managed services, and tailored infrastructure solutions. This trend is expected to continue as businesses prioritize data-driven decision-making, further boosting the market for next-generation data centres.Expansion of 5G and Edge Computing Infrastructure
The rollout of 5G technology in South Korea opens up significant opportunities for the data centre market, particularly in the area of edge computing. With 5G facilitating ultra-low latency and high-speed data transmission, there is a pressing need for localized data processing closer to end-users. Edge data centres, which process data at the periphery of networks, enable faster response times and greater bandwidth efficiency, especially for IoT, autonomous vehicles, and smart city applications. Telecom operators and service providers are investing heavily in 5G infrastructure, creating demand for decentralized edge facilities. Data centre operators can capitalize on this trend by offering distributed, high-performance solutions that meet the latency and security requirements of emerging technologies, positioning themselves as key enablers of the next generation of digital services in Soth Korea.Market Segmentation Analysis
By Type of Infrastructure The South Korea data centre market is broadly segmented by the type of infrastructure, which plays a crucial role in defining the efficiency and functionality of a data centre. The IT infrastructure segment encompasses the hardware and software components that support data storage, processing, and management. This segment has experienced growth with the rising demand for high-performance computing and advanced technologies like AI, IoT, and big data analytics. The electrical infrastructure segment includes the power supply systems essential for the smooth operation of data centres. With the increasing focus on sustainability, operators are investing in renewable energy solutions to meet the growing power demands. The mechanical infrastructure segment includes cooling and ventilation systems, which are critical for ensuring optimal temperature control in data centres. Given the high power consumption of modern data centres, advanced cooling technologies like liquid cooling and free-air cooling are becoming increasingly prevalent. Finally, the "others" category includes ancillary infrastructure such as fire suppression systems, security systems, and backup generators, all of which are vital for the safe and continuous operation of data centres. By Service Type The South Korea data centre market is also segmented based on the types of services offered. Colocation services dominate the market, where businesses lease space in a shared data centre facility. These services are ideal for organizations seeking cost-effective data storage and management solutions without the high capital expenditure of building their own infrastructure. Managed hosting services are also popular, providing businesses with outsourced IT management and support for hosting applications and websites. The growing demand for cloud computing services has led to an expansion of cloud services, where data centres offer scalable, on-demand storage, computing, and network resources. The "others" segment includes additional services like disaster recovery, backup solutions, and data security services that are integral to a comprehensive data centre offering.Segments
Based on Type of Infrastructure- IT Infrastructure
- Electrical Infrastructure
- Mechanical Infrastructure
- Others
- Colocation Services
- Managed Hosting Services
- Cloud Services
- Others
- BFSI
- IT & Telecom
- Media & Entertainment
- E-Commerce
- Government & Healthcare
- Others
- Tier 1
- Tier 2
- Tier 3
- Tier 4
- Small
- Mid-Sized
- Large
- Seoul
- Incheon and Gyeonggi
- Other regions (Busan, Daejeon, and Ulsan)
Regional Analysis
Seoul (60-65%) As the capital and economic hub of South Korea, holds the dominant market share. It accounts for approximately 60-65% of the total data centre infrastructure in the country. Seoul’s position as the business and financial center, combined with its highly developed IT ecosystem and dense population, makes it an ideal location for the establishment of both hyperscale and colocation data centres. The city is home to major cloud service providers like Amazon Web Services (AWS), Microsoft, and Google, which have expanded their presence to cater to increasing demand for cloud services and digital transformation. Seoul’s strategic location and advanced infrastructure further solidify its lead, driving demand for data centre services across various industries such as BFSI, IT & telecom, and e-commerce. Incheon and Gyeonggi Province (20-25%) Incheon and Gyeonggi Province follow as the secondary regions in terms of market share, collectively contributing around 20-25% to the data centre market. Incheon’s proximity to Seoul and its international airport provides an attractive location for data centres that require strong connectivity and accessibility to global markets. Gyeonggi Province benefits from relatively lower land costs compared to Seoul, making it an appealing choice for large-scale data centre operations. Several multinational companies and local service providers are capitalizing on these regions to expand their data centre footprints, particularly with the growing need for edge computing and 5G infrastructure. As regional data hubs, Incheon and Gyeonggi are increasingly accommodating demand for both traditional data centre services and emerging technologies.Key players
- Kakao Corp
- Korea Telecom (KT)
- Equinix
- Cisco Systems
- IBM
Competitive Analysis
The South Korea data centre market is highly competitive, with key players like Kakao Corp, Korea Telecom (KT), Equinix, Cisco Systems, and IBM leading the charge. Kakao Corp leverages its strong presence in South Korea's digital ecosystem, offering cloud and data services to support its messaging and gaming platforms. KT, one of the largest telecom providers in South Korea, offers extensive colocation and managed hosting services, backed by a robust infrastructure. Equinix stands out as a global leader in data centre services, providing interconnection and cloud services that cater to both local and international clients. Cisco Systems, with its cutting-edge networking solutions, plays a key role in enabling seamless connectivity for data centres. IBM’s expertise in enterprise IT infrastructure, cloud services, and AI-powered data solutions strengthens its position in the market, particularly with large enterprises looking for scalable and secure data solutions. These companies compete based on service offerings, scalability, and technological advancements in the rapidly growing South Korean data centre space.Recent Developments
- In December 2024, Kakao's CEO, Shina Chung, visited the Ansan data centre on December 24 to ensure operational stability ahead of the year-end holidays, a peak period for KakaoTalk's messaging traffic.
- In September 2024, KT Cloud announced plans to establish an AI data centre demonstration centre in Seoul to showcase its capabilities in artificial intelligence and cloud services. The centre is set to launch in November 2025 at KT's Mok-dong DC 2 Center in the Yangcheon District of Seoul.
- In Q1 2024, Equinix launched its new IBX data centre in Seoul, located within the SL2x hyperscale facility in Goyang-si, Gyeonggi-do. The centre offers 475 cabinets of capacity and is part of Equinix's xScale platform.
- In November 2024, Cisco released its 2024 AI Readiness Index for South Korea, highlighting the country's preparedness for AI adoption and identifying areas for improvement in infrastructure and talent.
- In November 2024, IBM and Yonsei University deployed the first IBM Quantum System One in South Korea at the university's new Quantum Computing Center, marking a significant milestone in the country's quantum computing capabilities.
Market Concentration and Characteristics
The South Korea data centre market exhibits moderate to high concentration, with a few key players dominating the industry. Major companies such as Kakao Corp, Korea Telecom (KT), Equinix, Cisco Systems, and IBM hold significant market shares, offering a range of services including colocation, cloud computing, managed hosting, and interconnection solutions. The market is characterized by rapid growth driven by increasing demand for cloud services, edge computing, and AI-driven infrastructure. Despite the dominance of a few large players, there is room for regional and niche providers to capture market share, particularly in response to the growing need for localized data processing in areas like Incheon, Gyeonggi, and beyond. Additionally, there is a strong emphasis on sustainability, with many operators investing in energy-efficient solutions and renewable energy sources to meet the country's environmental goals. This competitive and rapidly evolving market environment fosters innovation and continued investment in advanced technologiesReport Coverage
The research report offers an in-depth analysis based on Type of Infrastructure, Service Type, End User, Tier level of Infrastructure, Size and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.Future Outlook
- As businesses in South Korea increasingly migrate to the cloud, the demand for data centres offering scalable, on-demand resources will continue to rise. Cloud service providers will expand their footprints, further solidifying the market's growth.
- With the growing reliance on real-time data processing, edge data centres will play a pivotal role in supporting IoT and 5G technologies. This trend will lead to a decentralization of data processing, boosting the demand for regional data centres.
- The expansion of hyperscale data centres will be a dominant trend, driven by the need for high-performance computing and storage solutions. Larger providers will scale up infrastructure to accommodate increasing cloud and AI workloads.
- The ongoing rollout of 5G networks will drive the need for more data centre facilities to handle increased data traffic. Data centres will be critical to support the low latency requirements of 5G applications.
- Environmental sustainability will continue to be a priority, with data centre operators focusing on energy-efficient technologies and renewable energy sources to reduce their carbon footprint. Green data centres will become the industry standard.
- The South Korean government’s support for digital infrastructure, coupled with stringent data protection laws, will shape the market landscape. Operators will need to comply with evolving regulations related to data security and sovereignty.
- As South Korea remains a strategic data hub in Asia, international data centre providers will increase investments to meet the growing demand for data services in the region. This trend will encourage more competition and innovation.
- Data centres will increasingly adopt AI-driven solutions for predictive maintenance, workload optimization, and energy management. Automation will play a critical role in improving operational efficiency and reducing costs.
- Blockchain technology adoption for secure and transparent transactions will necessitate more robust data centre infrastructure. Data centres will need to cater to decentralized applications and blockchain mining needs.
- As industries like healthcare, finance, and media continue to grow, specialized data centres tailored to specific industry requirements will emerge. These facilities will offer customized services such as enhanced security, compliance, and performance for verticals with unique needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rapid Digital Transformation and Cloud Adoption
South Korea's enterprises and public sector are rapidly digitizing operations and migrating to cloud-based models, driving demand for scalable, secure, and high-performance data centre infrastructure. The proliferation of cloud services, hybrid and multi-cloud strategies, and digital government initiatives are fueling continuous investment in new data centre capacity.
Strong Government Support and Regulatory Initiatives
The South Korean government actively promotes digital infrastructure through policies like the K-Digital Strategy, offering tax incentives and regulatory support for data centre investments. Data localization laws and strict data protection regulations further compel businesses to establish or colocate servers within the country, boosting domestic data centre demand.
Deployment of 5G and Edge Computing Technologies
South Korea's leadership in 5G rollout and IoT adoption is generating massive volumes of real-time data, necessitating low-latency edge data centres. Investments in distributed infrastructure are rising to support applications such as autonomous vehicles, smart cities, and industrial automation, expanding the data centre footprint beyond traditional hubs.
Focus on Green Data Centres and Sustainability
With a national commitment to carbon neutrality by 2050 and increasing ESG pressures, operators are investing in energy-efficient, renewable-powered data centres. Innovations in cooling, power management, and sustainable design are attracting clients seeking environmentally responsible IT solutions and aligning with government incentives.
Expansion of Hyperscale and Specialized Data Centres
The surge in AI, big data analytics, and high-performance computing is driving the development of hyperscale and industry-specific data centres. Global and domestic providers are scaling up infrastructure to meet the needs of sectors like finance, healthcare, and media, reinforcing South Korea's role as a strategic digital hub in Asia.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the South Korea Data Centre Market in 2023, 2032, and its CAGR?
What are the key drivers for growth in the South Korea Data Centre Market?
Which regions are seeing significant data centre development in South Korea?
Who are the leading players in the South Korea Data Centre Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 BFSI
- 1.2.2 IT & Telecom
- 1.2.3 Media & Entertainment
- 1.2.4 E-Commerce
- 1.2.5 Government & Healthcare
- 1.2.6 Others
- 1.3 By Service Type
- 1.3.1 Colocation Services
- 1.3.2 Managed Hosting Services
- 1.3.3 Cloud Services
- 1.3.4 Others
- 1.4 By Type of Infrastructure
- 1.4.1 IT Infrastructure
- 1.4.2 Electrical Infrastructure
- 1.4.3 Mechanical Infrastructure
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 9,664.57 million → 2024: USD 9,664.57 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2024
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2024
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 South Korea Data Centre Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 South Korea Data Centre Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2024
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2024
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 South Korea Data Centre Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2024
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 South Korea Data Centre Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 South Korea Data Centre Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 South Korea Data Centre Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 South Korea Data Centre Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 South Korea Data Centre Market Outlook, 2024-2024
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 9,664.57 million → 2024: USD 9,664.57 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2024
- 11.2.1 Revenue Forecast to 2024
- 11.2.2 Volume Forecast to 2024
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 South Korea Data Centre Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2024
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2024
- 12.3.4 Volume Forecast, 2024-2024
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 BFSI
- 12.3.7.2 IT & Telecom
- 12.3.7.3 Media & Entertainment
- 12.3.7.4 E-Commerce
- 12.3.7.5 Government & Healthcare
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Service Type - Market Size and Forecast, 2024-2024
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2024
- 12.4.4 Volume Forecast, 2024-2024
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Colocation Services
- 12.4.7.2 Managed Hosting Services
- 12.4.7.3 Cloud Services
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Type of Infrastructure - Market Size and Forecast, 2024-2024
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2024
- 12.5.4 Volume Forecast, 2024-2024
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 IT Infrastructure
- 12.5.7.2 Electrical Infrastructure
- 12.5.7.3 Mechanical Infrastructure
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 South Korea Data Centre End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 South Korea Data Centre Geographic Market Outlook, 2024-2024
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2024
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 South Korea Data Centre Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2024
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 South Korea Data Centre Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2024
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Kakao Corp
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Korea Telecom (KT)
- 18.4 Equinix
- 18.5 Cisco Systems
- 18.6 IBM
- 18.7 LG Uplus Corp.
- 18.8 SK Broadband
- 18.9 Digital Realty
- 18.10 Naver Cloud
- 18.11 Amazon Web Services (AWS)
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

