
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Spain Water Pump Market Size 2023 | USD 1,130.32 million |
| Spain Water Pump Market, CAGR | 2.35% |
| Spain Water Pump Market Size 2032 | USD 1,394.63 million |
Market Overview:
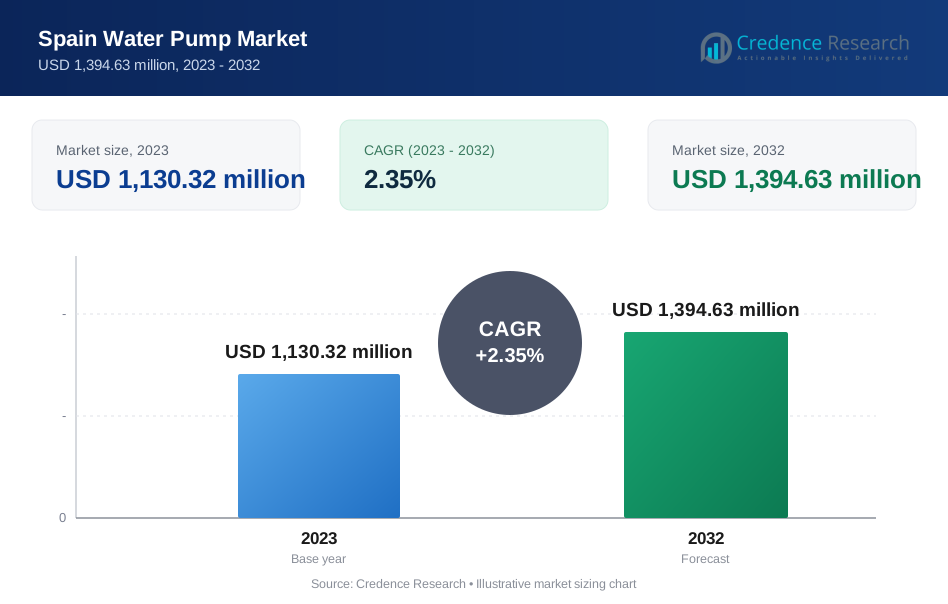
Spain Water Pump Market size was valued at USD 1,130.32 million in 2023 and is anticipated to reach USD 1,394.63 million by 2032, at a CAGR of 2.35% during the forecast period (2023-2032).
The growth of Spain's water pump market is driven by key factors, including substantial investments in renewable energy sources like wind and solar power. The Spanish government aims to generate 74% of the nation’s electricity from renewables by 2030, creating demand for specialized pumps in solar installations, hydroelectric plants, and wind turbines. The shift towards renewable energy also drives the adoption of advanced pumping solutions for energy storage systems, boosting long-term market growth. Additionally, Spain is upgrading its water and wastewater infrastructure to meet environmental standards and support urbanization. The increasing need for efficient water management systems in industrial sectors, coupled with the agricultural industry's shift towards sustainable practices like precision irrigation, further accelerates pump demand. As urbanization expands, the growing requirement for residential and commercial buildings, along with efficient potable water supply and wastewater management, contributes to the overall market expansion.
Spain holds a significant share of the European water pump market, driven by factors such as rapid urbanization, groundwater depletion, and increased consumer spending. The growing demand for water pumps in Spain aligns with regional initiatives focused on improving water infrastructure and adopting sustainable practices. The country’s efforts to reduce water waste and ensure efficient water use are in line with broader EU directives, further fueling the demand for advanced pumping solutions. Spain’s commitment to renewable energy and infrastructure development strengthens its role as a key player in the regional market. The need for energy-efficient pumping systems and adherence to stringent wastewater treatment regulations support the demand for water pumps. Additionally, Spain’s investment in industrial sectors like agriculture, manufacturing, and mining continues to rise, creating opportunities for the deployment of advanced pumping solutions. Spain’s strategic location in Southern Europe also enhances its influence in the European water pump market.
Market Insights:
- The Spain water pump market is expected to grow from USD 1,130.32 million in 2023 to USD 1,394.63 million by 2032, at a CAGR of 2.35%.
- The global water pump market was valued at USD 55,454.00 million in 2023 and is projected to reach USD 80,304.96 million by 2032, growing at a CAGR of 4.2% during the forecast period.
- Key growth drivers include substantial investments in renewable energy sources like wind and solar power, creating demand for specialized pumps in energy storage and generation.
- Spain’s efforts to modernize its water and wastewater infrastructure contribute significantly to the market’s expansion, driven by urbanization and the need for efficient water management systems.
- The agricultural sector plays a crucial role in driving water pump demand, with the adoption of sustainable practices like precision irrigation to optimize water usage.
- Stringent environmental regulations and EU directives on wastewater treatment and water management are pushing the demand for more efficient, energy-saving pumping solutions.
- The high initial investment costs of advanced water pumps could slow market growth, particularly for small-scale industries or municipalities with limited budgets.
- Spain’s regional market is diverse, with regions like Andalusia and Valencia seeing high demand due to their agricultural focus, while urban areas such as Madrid drive pump demand for infrastructure projects.
Market Drivers:
Renewable Energy Expansion
One of the primary drivers of the water pump market in Spain is the country's increasing commitment to renewable energy. The Spanish government has set ambitious targets to generate 74% of its electricity from renewable sources by 2030. This shift towards renewables necessitates the use of specialized pumping systems for various energy-related processes, including water circulation in hydroelectric plants, cooling systems in solar power plants, and fluid transfer in wind turbines. For example, Iberdrola España has commissioned a 225 MW pumping station at the Valdecañas project in Cáceres, which integrates technological improvements to enhance water circulation and storage capacity. As Spain continues to expand its renewable energy infrastructure, the demand for efficient and reliable water pumps is expected to rise. These pumps play a crucial role in ensuring the smooth operation of renewable energy facilities, directly contributing to the sector’s growth.
Infrastructure Development and Modernization
Spain's ongoing efforts to upgrade and modernize its water and wastewater infrastructure are significant contributors to the growth of the water pump market. As part of its commitment to environmental sustainability, the country is investing in advanced water management systems to improve water treatment, reduce waste, and increase overall efficiency. For instance, Canal de Isabel II plans to allocate over €2 billion by 2030 to improve water collection, treatment facilities, and distribution networks, including €450 million for pipe renovations to reduce losses and increase quality. This modernization drive is particularly evident in urban areas, where the demand for reliable water supply and wastewater management systems continues to rise due to rapid urbanization. As cities grow and infrastructure demands increase, the need for efficient pumping solutions becomes more critical, further accelerating market growth.
Agricultural Sector and Sustainable Practices
The agricultural sector in Spain also plays a pivotal role in driving the demand for water pumps. As water scarcity and climate change concerns grow, there has been a significant shift towards sustainable farming practices, including precision irrigation. This method optimizes water usage and reduces waste, thereby improving agricultural productivity. As a result, farmers are increasingly investing in advanced water pumps to support irrigation systems that can deliver water efficiently and effectively across large farming operations. Furthermore, Spain's agricultural policies and initiatives aimed at improving water conservation further contribute to the rising demand for water pumps in the sector, ensuring that resources are utilized sustainably.
Regulatory Compliance and Environmental Standards
Spain's adherence to strict environmental regulations also serves as a significant market driver. The European Union has set stringent directives on wastewater treatment, water management, and pollution control, which Spain is actively implementing. These regulations require the installation of more efficient and technologically advanced water pumping systems to meet compliance standards. Additionally, Spain's focus on reducing water waste and improving the efficiency of water use has prompted investments in energy-efficient pumping systems that align with these environmental goals. As businesses and industries seek to comply with these regulations, the demand for advanced water pumps that can meet sustainability and efficiency standards continues to grow. This regulatory push enhances the market’s expansion, particularly as Spain leads efforts in meeting EU-wide water and environmental directives.
Market Trends:
Adoption of Smart Pumping Solutions
A significant trend in the Spain water pump market is the increasing adoption of smart pumping systems. These systems integrate advanced technologies such as IoT (Internet of Things) sensors and automation to enhance pump performance, monitor efficiency, and reduce energy consumption. As industries and municipalities seek to optimize water management, smart pumps enable real-time monitoring and predictive maintenance, leading to improved system reliability and reduced operational costs. The growing emphasis on automation in water management across various sectors, including industrial and agricultural applications, further accelerates the demand for these technologically advanced solutions. As Spain’s infrastructure modernizes, the trend toward smart pumping solutions is likely to become even more prominent.
Energy-Efficient Pumping Solutions
Another key trend in the Spanish water pump market is the growing demand for energy-efficient pumping systems. With rising energy costs and increased environmental concerns, industries and municipalities are turning to energy-efficient pumps to reduce operational costs and carbon footprints. Energy-efficient pumps are designed to optimize energy use, particularly in systems that operate continuously, such as those used in water treatment plants and irrigation systems. Spain’s commitment to sustainability and its alignment with European Union energy efficiency directives have further driven the demand for such solutions. As energy efficiency becomes a key competitive factor in the water management sector, the demand for energy-efficient pumps is expected to rise steadily.
Integration of Renewable Energy with Pumping Systems
The integration of renewable energy sources with water pumping systems is a growing trend in Spain. This approach reduces the reliance on conventional energy sources and makes water management systems more sustainable. Solar and wind energy are increasingly being used to power water pumps, particularly in remote areas or agricultural applications where access to the grid may be limited. Spain’s strong commitment to expanding renewable energy infrastructure has made this integration more feasible, leading to a rise in solar-powered pumps and wind-powered pumping systems. For instance, the country added 7.3 GW of new photovoltaic and wind power capacity in 2024, driving demand for specialized pumps used in solar panels and hydroelectric plants. This trend not only supports sustainability goals but also provides cost-effective solutions for industries and farmers who aim to reduce energy costs while maintaining efficient water management.
Focus on Water Conservation and Wastewater Reuse
Water conservation and wastewater reuse are becoming increasingly important trends in Spain’s water pump market. The country has faced periodic water shortages due to climate change, which has led to a growing focus on conserving water and recycling wastewater for reuse. This shift is particularly evident in industrial sectors where water is used in large quantities. The demand for advanced pumping systems capable of handling treated wastewater and distributing it efficiently for irrigation or industrial purposes is growing. Additionally, Spain’s regulatory environment, which emphasizes water conservation and wastewater treatment, further supports this trend. For example, Tsurumi submersible aerators are used extensively in WWTPs across Spain to ensure high-quality water treatment for subsequent applications. As water scarcity continues to be a concern, the need for efficient and reliable pumps to facilitate water reuse and conservation efforts will continue to shape the market in the coming years.
Market Challenges Analysis:
High Initial Investment Costs
One of the major restraints in the Spain water pump market is the high initial investment cost associated with advanced pumping systems. Although energy-efficient and smart pumps offer long-term operational savings, their upfront costs can be significant, which may deter smaller enterprises or municipalities with limited budgets from upgrading their existing systems. For instance, the adoption of energy-efficient pumps under the EU's Ecodesign Directive often requires substantial upfront capital, deterring smaller businesses from upgrading their systems. This financial barrier is particularly prominent in sectors like agriculture and small-scale industries, where resource constraints limit the ability to invest in high-cost solutions. As a result, the market may experience slower adoption of advanced technologies, which could hinder overall market growth.
Maintenance and Operational Costs
Despite the benefits of energy-efficient and advanced water pumps, their maintenance and operational costs can also be a challenge. These pumps require specialized knowledge for installation, operation, and maintenance, which can increase service costs over time. In some cases, the lack of skilled technicians and the complexity of maintaining advanced systems may lead to operational inefficiencies, reducing the cost-effectiveness of these pumps. This challenge is more pronounced in remote areas where technical expertise may be scarce. Such issues could potentially limit the adoption of advanced pump solutions across different sectors in Spain.
Regulatory and Compliance Challenges
While Spain’s regulatory framework is beneficial for sustainability, it also poses challenges for businesses. The strict environmental and water management regulations require constant updates and compliance efforts, which can be burdensome for industries that are already facing economic pressures. Keeping up with these regulations demands continuous investments in new technologies and equipment. Companies that fail to meet regulatory requirements risk fines or operational halts, which adds an additional layer of complexity to market participation. This regulatory burden may discourage some businesses from upgrading their water pump systems, thus restricting overall market growth.
Competition and Market Fragmentation
The water pump market in Spain is highly competitive, with numerous local and international players offering a wide range of products. This fragmentation can create challenges for companies trying to differentiate their products and establish a strong market presence. Additionally, smaller players may struggle to compete with larger, well-established firms that have greater resources for R&D, marketing, and distribution. This intense competition can limit profitability for companies in the market, slowing down the pace of innovation and expansion.
Market Opportunities:
The Spain water pump market presents significant opportunities driven by the country’s increasing focus on sustainability and renewable energy. As Spain continues to invest heavily in renewable energy sources such as wind, solar, and hydroelectric power, the demand for specialized pumping systems is expected to grow. The integration of water pumps in energy storage systems and renewable energy facilities, such as solar-powered water pumps for irrigation or water circulation in hydropower plants, offers substantial market potential. Additionally, as Spain aims to reduce its carbon footprint and improve energy efficiency, there is an opportunity for companies to develop advanced, energy-efficient pumping solutions that can meet both environmental and economic goals.
Another promising market opportunity lies in Spain's water conservation efforts and wastewater management. The country’s focus on reducing water waste and promoting water reuse creates a growing demand for efficient water management systems. As industries, municipalities, and agricultural sectors look to optimize water usage and comply with stringent environmental regulations, the need for advanced water pumps will increase. Companies that can provide innovative solutions for wastewater treatment and reuse will be well-positioned to capture a share of this expanding market. Moreover, Spain’s commitment to modernizing its water infrastructure presents opportunities for businesses that offer state-of-the-art water pumping systems, ensuring efficient and reliable water distribution across the nation. The convergence of renewable energy goals and water conservation initiatives will likely drive future growth in the water pump market.
Market Segmentation Analysis:
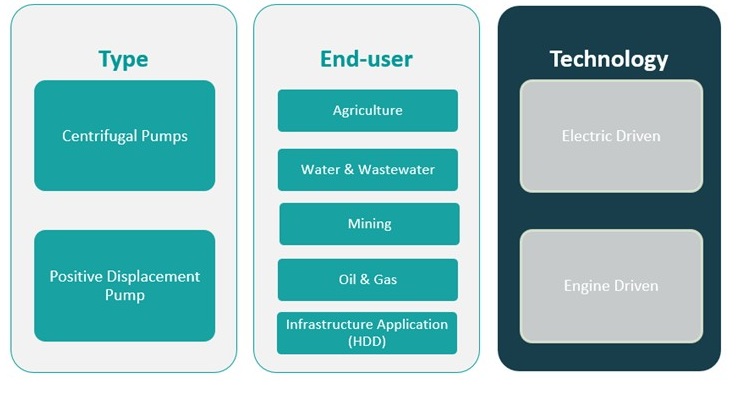
The Spain water pump market can be segmented by type, end-user, and technology, each exhibiting unique characteristics and growth potential.
By Type Segment The market is primarily divided into centrifugal pumps and positive displacement pumps. Centrifugal pumps dominate due to their widespread use in various applications, including water treatment and industrial processes. These pumps are valued for their high efficiency and ability to handle large volumes of water. Positive displacement pumps, on the other hand, are preferred for applications requiring precise flow rates, such as in the oil and gas industry. Both types of pumps are integral to Spain’s growing industrial and infrastructure sectors.
By End-User Segment The key end-user segments in the Spain water pump market include agriculture, water and wastewater, mining, oil and gas, and infrastructure applications. The agriculture sector drives demand for pumps due to the growing emphasis on efficient irrigation systems. In water and wastewater management, pumps are essential for treatment and distribution processes. The mining industry, requiring reliable pumps for dewatering and fluid handling, is another significant segment. Oil and gas operations rely on pumps for fluid transfer, while infrastructure applications, particularly Horizontal Directional Drilling (HDD), require pumps for fluid circulation in construction projects.
By Technology Segment The market is also segmented by technology into electric-driven and engine-driven pumps. Electric-driven pumps are increasingly popular due to their energy efficiency and lower operating costs, making them ideal for urban water management and industrial uses. Engine-driven pumps are preferred in remote or off-grid locations, providing flexibility and reliability for mining, oil, and gas industries, where access to electricity may be limited.
Segmentation:
By Type Segment:
- Centrifugal Pumps
- Positive Displacement Pumps
By End-User Segment:
- Agriculture
- Water & Wastewater
- Mining
- Oil & Gas
- Infrastructure Application (HDD)
By Technology Segment:
- Electric Driven
- Engine Driven
Regional Analysis:
Spain's water pump market is characterized by regional variations influenced by industrial activities, infrastructure development, and agricultural practices. While comprehensive regional market share data is limited, available information provides insight into the distribution and growth prospects across different regions.
Catalonia (25%) Catalonia, with its strong industrial base and agricultural sector, contributes significantly to the water pump market. The region’s need for efficient water management due to frequent water scarcity issues and its agricultural practices (especially irrigation) support a substantial share of the market.
Valencia (20%) Valencia, marked by its agricultural significance and water management challenges (alternating droughts and floods), plays a key role in driving demand for water pumps. Its infrastructure requirements for irrigation and flood control contribute to the region's significant market share.
Andalusia (18%) Andalusia, with its large agricultural lands requiring extensive irrigation systems, is a major consumer of water pumps. The region’s focus on modernizing agricultural practices and improving water efficiency through advanced pumping technologies contributes to its share of the market.
Madrid and Castile and León (15%) Madrid and Castile and León are urban and industrial hubs, driving demand for water pumps in municipal water supply, wastewater treatment, and industrial processes. These regions’ urbanization and industrial activities support a strong, steady market demand for water pumps.
Basque Country and Galicia (12%) These regions, with a solid industrial base and maritime influence, have consistent demand for water pumps in manufacturing processes and marine operations. While their share is relatively smaller compared to agricultural regions, industrial needs still play an essential role in the market.
Other Regions (10%) Other regions in Spain, while contributing to the overall water pump market, have a more limited demand compared to the major agricultural and industrial regions. However, infrastructure development and local water management needs still create opportunities for water pump solutions in these areas.
Key Player Analysis:
- SLB
- Ingersoll Rand
- The Weir Group PLC
- Vaughan Company
- KSB SE & Co. KGaA
- Pentair
- Grundfos Holding A/S
- Xylem
- Flowserve Corporation
- ITT Inc.
- EBARA Corporation
- KSB
Competitive Analysis:
The Spain water pump market is highly competitive, with a mix of local and international players offering a wide range of products and solutions. Key players include multinational companies such as Grundfos, Xylem Inc., and KSB SE & Co. KGaA, which dominate the market with their technologically advanced and energy-efficient pumping systems. These companies have a strong presence across Spain, driven by their extensive product portfolios and reliable service networks. Local manufacturers, such as the Spanish company Hidroconta, also hold significant market share by providing tailored solutions for specific regional needs, particularly in agricultural and wastewater applications. The competitive landscape is further shaped by the increasing demand for smart pumps and energy-efficient systems, which encourages innovation and investment in R&D. Additionally, local companies leverage their understanding of regional water management challenges to offer specialized products, intensifying competition in both the industrial and agricultural segments of the market.
Recent Developments:
- In September 2024, ESPA Group, a subsidiary of Industrias Auxiliares GTE Group S.L., announced the acquisition of Baico Pumps, S.L., a prominent distributor of water pumps and pressure equipment. This strategic move aims to enhance ESPA's product portfolio and expand its presence in over 100 countries. Baico Pumps, which has an annual turnover of €4 million and exports to more than 18 countries, will continue to operate under the leadership of Joan Nierga, ensuring continuity and growth.
- In April 2024, SLB introduced the Reda Agile compact wide-range electric submersible pump system, designed for deep-water applications. This innovative product enhances reliability and operational efficiency in harsh subsea conditions, optimizing fluid handling
Market Concentration & Characteristics:
The Spain water pump market is moderately fragmented, characterized by a blend of multinational corporations and regional manufacturers. Multinational entities such as Grundfos, Xylem Inc., and KSB SE & Co. KGaA have established a strong presence, offering a diverse range of technologically advanced and energy-efficient pumping solutions. These companies leverage global expertise to meet Spain's evolving water management needs. Regional manufacturers, including Spain's Hidroconta, also play a significant role by providing specialized solutions tailored to local requirements, particularly in agricultural and wastewater sectors. This combination of global and local players fosters healthy competition, driving innovation and ensuring a wide array of products to address various applications across Spain's water pump market. Additionally, the increasing demand for energy-efficient and smart pumping systems further intensifies competition, with companies focusing on R&D to cater to the growing need for sustainable solutions.
Report Coverage:
The research report offers an in-depth analysis based on Type Segment, End-User Segment and Technology Segment. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Spain water pump market is expected to grow steadily, driven by increasing infrastructure development and modernization projects.
- Renewable energy initiatives will further propel demand for specialized water pumps in solar and hydroelectric plants.
- Growing agricultural demand for irrigation and water management systems will support the market, especially in regions like Andalusia and Valencia.
- The adoption of energy-efficient and smart pumps will rise as industries and municipalities aim to reduce operational costs.
- Increased regulatory pressure for water conservation and wastewater management will drive demand for advanced pumping solutions.
- Spain's commitment to reducing water waste and improving sustainability will encourage innovation in pump technologies.
- Investment in the mining and oil & gas sectors will create new opportunities for water pump suppliers in industrial applications.
- The shift towards automated and remote-controlled pumping systems will gain momentum in urban water management.
- The market will benefit from the growing focus on wastewater reuse and recycling across various industries.
- Local manufacturers are expected to expand their market share by offering customized solutions for Spain’s unique regional water management needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Renewable Energy Expansion
Spain's ambitious targets for renewable energy generation, especially in wind and solar, are driving demand for specialized water pumps used in energy storage, hydroelectric plants, and solar installations, supporting the growth of advanced pumping solutions.
Infrastructure Development and Modernization
Ongoing investments to upgrade water and wastewater infrastructure, particularly in urban areas, are increasing the need for efficient and reliable water pumps to support potable water supply, distribution, and wastewater management.
Agricultural Sector Shift to Sustainable Practices
The adoption of precision irrigation and sustainable farming practices in Spain's large agricultural sector is boosting demand for advanced water pumps that optimize water usage and improve productivity.
Stringent Environmental Regulations
Compliance with EU directives and national regulations on water management and wastewater treatment is pushing industries and municipalities to invest in energy-efficient and technologically advanced pumping systems.
Urbanization and Water Management Needs
Rapid urbanization and the expansion of residential and commercial buildings are increasing the demand for modern water management systems, driving the adoption of smart and automated water pumps across Spain.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Spain Water Pump Market?
What factors are driving the growth of the Spain Water Pump Market?
What are some challenges faced by the Spain Water Pump Market?
Who are the major players in the Spain Water Pump Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Centrifugal Pumps
- 1.2.2 Positive Displacement Pumps
- 1.3 By End-User
- 1.3.1 Agriculture
- 1.3.2 Water & Wastewater
- 1.3.3 Mining
- 1.3.4 Oil & Gas
- 1.3.5 Infrastructure Application (HDD)
- 1.4 By Technology
- 1.4.1 Electric Driven
- 1.4.2 Engine Driven
- 1.5 By Application
- 1.5.1 Irrigation
- 1.5.2 Municipal Water Supply
- 1.5.3 Industrial Processes
- 1.5.4 Wastewater Treatment
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 1,130.32 million → 2032: USD 1,394.63 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Spain Water Pump Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Spain Water Pump Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Spain Water Pump Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Spain Water Pump Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Spain Water Pump Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Spain Water Pump Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Spain Water Pump Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Spain Water Pump Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 1,130.32 million → 2032: USD 1,394.63 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Spain Water Pump Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Centrifugal Pumps
- 12.3.7.2 Positive Displacement Pumps
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Agriculture
- 12.4.7.2 Water & Wastewater
- 12.4.7.3 Mining
- 12.4.7.4 Oil & Gas
- 12.4.7.5 Infrastructure Application (HDD)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Electric Driven
- 12.5.7.2 Engine Driven
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Irrigation
- 12.6.7.2 Municipal Water Supply
- 12.6.7.3 Industrial Processes
- 12.6.7.4 Wastewater Treatment
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Spain Water Pump End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Spain Water Pump Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Spain Water Pump Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Spain Water Pump Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Grundfos Holding A/S
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Xylem Inc.
- 18.4 KSB SE & Co. KGaA
- 18.5 Flowserve Corporation
- 18.6 ITT Inc.
- 18.7 EBARA Corporation
- 18.8 Pentair
- 18.9 SLB
- 18.10 The Weir Group PLC
- 18.11 Ingersoll Rand
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
