
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
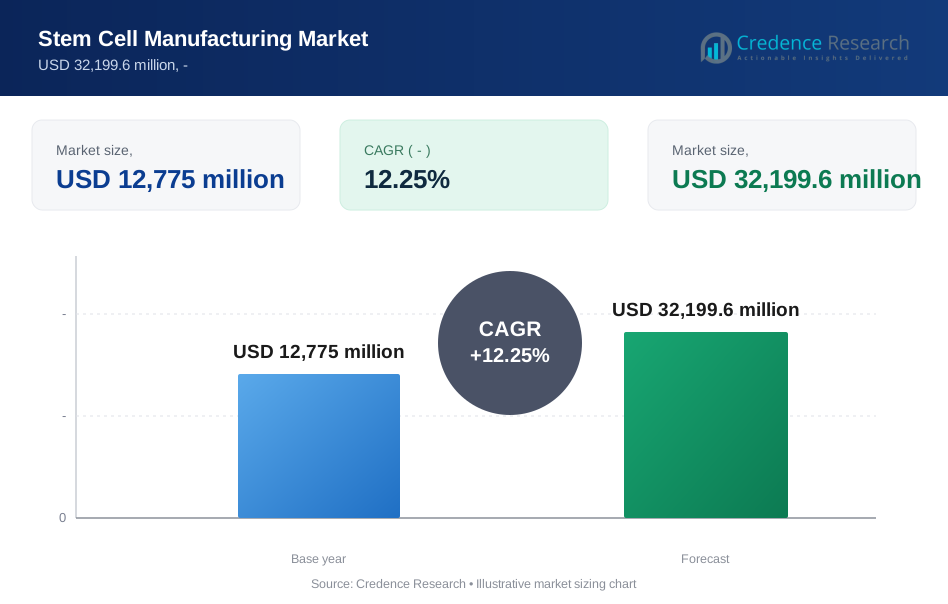
| Stem Cell Manufacturing Market Size 2024 | USD 12,775 Million |
| Sports and Fitness Apps Market, CAGR | 12.25% |
| Sports and Fitness Apps Market Size 2032 | USD 32,199.6 Million |
Market Overview:
The Stem Cell Manufacturing Market is experiencing significant growth, driven by advancements in regenerative medicine and increasing investments in stem cell research. As of 2024, the global Stem Cell Manufacturing Market is valued at approximately USD 12,775 million and is projected to grow at a compound annual growth rate (CAGR) of 12.25% over the forecast period, reaching around USD 32,199.6 million by 2032. This robust growth reflects the rising demand for stem cell therapies and the expanding applications of stem cells in various therapeutic areas, including oncology, orthopaedics, and neurology.
Several key factors are propelling the market's expansion. The increasing prevalence of chronic diseases and the need for innovative treatment options are significant drivers. Additionally, the growing focus on personalized medicine and the potential of stem cell therapies to address previously untreatable conditions are fostering greater investment in manufacturing technologies. Moreover, advancements in cell culture techniques, bioreactors, and quality control measures are enhancing the efficiency and scalability of stem cell production.
Regionally, North America holds the largest share of the Stem Cell Manufacturing Market, primarily due to its well-established research infrastructure, significant funding for stem cell research, and favourable regulatory environment. Europe follows closely, driven by increasing collaborations between research institutions and industry stakeholders, as well as a strong emphasis on clinical trials. The Asia-Pacific region is anticipated to witness substantial growth during the forecast period, fueled by rising investments in healthcare, growing awareness of stem cell therapies, and expanding biopharmaceutical manufacturing capabilities. Emerging economies such as China and India are expected to present considerable opportunities for growth, given their large patient populations and increasing focus on healthcare innovation.
Market Drivers:
Growing Prevalence of Chronic Diseases:
The increasing incidence of chronic diseases is a significant driver of the Stem Cell Manufacturing Market. For instance, the American Cancer Society reports that in 2023, there were an estimated 1.9 million new cancer cases diagnosed in the United States alone, highlighting the urgent need for innovative treatments like stem cell therapies. This rise in chronic conditions has created an urgent demand for innovative treatment solutions, including stem cell therapies, which offer the potential for regenerative and personalized medicine. The International Monetary Fund (IMF) has projected that healthcare spending on chronic disease management will rise by over 8% annually in emerging markets by 2025, further underscoring the need for advanced manufacturing capabilities in stem cell applications.
Advancements in Stem Cell Research:
Significant advancements in stem cell research are propelling the market forward. Major research institutions and organizations, such as the National Institutes of Health (NIH) and the European Molecular Biology Laboratory (EMBL), are making strides in understanding the mechanisms of stem cells and their potential applications in regenerative medicine. For instance, The National Institutes of Health (NIH) reported a 20% increase in funding for stem cell research projects from 2019 to 2023, reaching $2.1 billion in 2023. The California Institute for Regenerative Medicine (CIRM) has awarded over $3 billion in grants for stem cell research since its inception in 2004. In 2022, researchers at the Harvard Stem Cell Institute successfully created functional human heart tissue from stem cells, a breakthrough that could revolutionize cardiac treatments. These advancements not only enhance the efficacy of stem cell therapies but also drive investment in manufacturing technologies required for large-scale production, thus fostering market growth.
Increasing Investment in Biotechnology:
Investment in biotechnology, particularly in the field of stem cell research and manufacturing, is another critical driver of market growth. For instance, according to the World Bank, global investments in biotechnology are expected to increase by 12% annually through 2026. In 2023, venture capital investments in stem cell-related start-ups reached $4.5 billion globally. Pharmaceutical giant Novartis invested $800 million in expanding its cell and gene therapy manufacturing facilities in 2022. The U.S. government's "National Biotechnology and Biomanufacturing Initiative" allocated $2 billion in funding to support advancements in biotechnology, including stem cell manufacturing. This influx of funding is attracting both established pharmaceutical companies and emerging biotech start-ups, fostering innovation in stem cell manufacturing processes and technologies. Additionally, government initiatives aimed at promoting biomanufacturing are providing further incentives for companies to invest in this area, enhancing the overall market landscape.
Supportive Regulatory Environment:
A supportive regulatory environment is crucial for the growth of the Stem Cell Manufacturing Market. Regulatory bodies such as the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) have developed frameworks aimed at facilitating the development and commercialization of stem cell therapies. The FDA has issued guidance documents that clarify the regulatory pathways for stem cell products, while the EMA has introduced streamlined approval processes for advanced therapy medicinal products (ATMPs). For instance, as of 2022, approximately 60% of surveyed biotechnology firms reported that a clear regulatory framework significantly impacts their decision to invest in stem cell research and manufacturing. This supportive environment not only boosts confidence among investors but also accelerates the pace of product development and market entry. The Stem Cell Manufacturing Market is driven by the growing prevalence of chronic diseases, advancements in stem cell research, increasing investment in biotechnology, and a supportive regulatory environment. These factors collectively enhance the attractiveness of the market, paving the way for further growth and innovation in stem cell manufacturing technologies.
Market Trends:
Shift Towards Personalized Medicine:
One of the most significant trends in the Stem Cell Manufacturing Market is the shift towards personalized medicine. The demand for tailored therapies that cater to individual patient profiles is rapidly increasing. According to the National Institutes of Health (NIH), personalized medicine has the potential to transform healthcare by delivering more effective treatments based on genetic, environmental, and lifestyle factors. For instance, as of 2023, approximately 70% of healthcare providers reported a growing interest in personalized treatment options, emphasizing the need for innovative stem cell solutions. The development of patient-specific stem cell therapies is becoming increasingly feasible due to advancements in technology such as CRISPR gene editing and induced pluripotent stem cells (iPSCs). These technologies enable the creation of personalized stem cell lines, paving the way for targeted treatments in areas such as oncology and genetic disorders.
Increased Focus on Sustainable Manufacturing Practices:
Another emerging trend is the increased focus on sustainable manufacturing practices within the stem cell sector. Organizations like the World Health Organization (WHO) and the United Nations have stressed the importance of sustainable healthcare practices to combat climate change and promote environmental health. In response, many stem cell manufacturers are adopting environmentally friendly production methods. For instance, A survey conducted by the International Society for Stem Cell Research (ISSCR) in 2022 indicated that 65% of industry stakeholders are actively pursuing sustainable practices in their manufacturing processes. This includes utilizing renewable energy sources, reducing waste, and optimizing resource consumption. Moreover, regulatory bodies are starting to recognize and reward companies that implement sustainable practices, creating a competitive advantage for those leading the charge in environmental stewardship. the Stem Cell Manufacturing Market is witnessing a notable trend towards personalized medicine and sustainable manufacturing practices. As these trends continue to evolve, they will likely shape the future landscape of stem cell therapies, driving innovation and responsiveness to patient needs while ensuring a commitment to environmental sustainability.
Market Challenge Analysis:
Regulatory Hurdles and High Manufacturing Costs in Stem Cell Manufacturing
Navigating Complex Regulatory Landscapes:
The Stem Cell Manufacturing Market faces significant challenges due to the intricate regulatory environment governing the development and commercialization of stem cell therapies. Regulatory bodies such as the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) impose rigorous guidelines to ensure patient safety and product efficacy. While these regulations are crucial, they often result in prolonged approval processes and increased costs for companies in the sector.
Impact on Market Dynamics:
As of 2023, approximately 58% of industry stakeholders reported that regulatory challenges significantly impact their ability to bring new products to market efficiently. This regulatory complexity can deter investment and innovation in the sector, potentially slowing the pace of advancements in stem cell therapies.
Global Variations in Regulatory Frameworks:
The regulatory landscape varies across different regions, adding another layer of complexity for companies operating globally. For instance, while the FDA has approved 23 cell and gene therapy products between 2017 and 2023, the approval process in other countries may differ significantly. This variability can lead to challenges in global market expansion and product harmonization.
The Financial Burden of Stem Cell Manufacturing:
High Production Costs:
The stem cell manufacturing process involves sophisticated technologies, specialized facilities, and highly skilled personnel, all contributing to elevated operational expenses. These factors make it challenging for companies to achieve cost-effective production while maintaining the high-quality standards required for stem cell therapies.
Impact on Market Access:
According to the World Bank, the high costs associated with cell culture and bioprocessing technologies can limit access to stem cell therapies, particularly in developing regions with constrained healthcare budgets. This financial barrier may restrict market growth and the widespread adoption of stem cell treatments in emerging markets where investment in advanced healthcare solutions is still developing.
Balancing Cost and Quality:
Companies in the stem cell manufacturing sector face the ongoing challenge of balancing the need for cost-effective production with the demand for high-quality, scalable therapies. This balancing act is crucial for ensuring the commercial viability of stem cell products while meeting regulatory standards and patient needs.
Market Segmentation Analysis:
By Type
The Stem Cell Manufacturing Market is primarily segmented into two main types: adult stem cells and embryonic stem cells. Adult stem cells, which can be found in various tissues, are increasingly favoured due to their ethical advantages and potential for treating a range of conditions, including blood disorders and orthopaedic issues. Embryonic stem cells, while holding significant potential for regenerative medicine, face ethical concerns that can limit their use in clinical applications. Additionally, induced pluripotent stem cells (iPSCs) are gaining traction, as they offer the versatility of embryonic stem cells without the associated ethical implications, allowing for patient-specific therapies.
By Technology
In terms of technology, the market is segmented into several key areas, including cell culture techniques, bioreactors, and separation technologies. Cell culture techniques are essential for expanding stem cell populations and ensuring their viability. Bioreactors play a crucial role in providing controlled environments for stem cell growth, significantly enhancing production efficiency. Separation technologies are also critical, enabling the purification and characterization of stem cells to ensure quality and consistency in therapeutic applications. Advances in these technologies are driving innovation and improving the scalability of stem cell manufacturing processes.
By End-User
The end-user segmentation of the Stem Cell Manufacturing Market includes hospitals, research laboratories, and biotechnology companies. Hospitals are increasingly adopting stem cell therapies for treating a variety of conditions, thereby driving demand for manufacturing capabilities. Research laboratories play a pivotal role in advancing stem cell research, often requiring specialized manufacturing solutions to support their experiments and clinical trials. Biotechnology companies are at the forefront of commercializing stem cell therapies, investing in advanced manufacturing technologies to meet regulatory standards and market demands. Each of these segments contributes uniquely to the overall growth and development of the stem cell manufacturing landscape.
Segmentation:
Based on Type:
- Adult Stem Cells
- Embryonic Stem Cells
- Induced Pluripotent Stem Cells (iPSCs)
Based on Technology:
- Cell Culture Techniques
- Bioreactors
- Separation Technologies
- Cryopreservation Technologies
Based on End-User:
- Hospitals
- Research Laboratories
- Biotechnology Companies
- Pharmaceutical Companies
Based on Region:
- North America
- United States
- Canada
- Europe
- United Kingdom
- Germany
- France
- Italy
- Asia-Pacific
- China
- India
- Japan
- Australia
- Latin America
- Brazil
- Mexico
- Middle East and Africa
- South Africa
- UAE
- Saudi Arabia
Regional Analysis:
North America
North America holds the largest share of the Stem Cell Manufacturing Market, accounting for approximately 40% of the global market in 2023. This dominance is primarily driven by a well-established healthcare infrastructure, significant funding for research and development, and a favourable regulatory environment. The United States, in particular, leads the way with major investments from government entities such as the National Institutes of Health (NIH) and the Department of Defence. The increasing prevalence of chronic diseases and the rising demand for innovative therapies further propel market growth in this region. Additionally, North American biotech companies are at the forefront of stem cell research, focusing on personalized medicine and advanced manufacturing techniques. The presence of key players, along with a growing number of clinical trials, enhances the region's competitive landscape, making it a hub for stem cell advancements and applications.
Europe
Europe is the second-largest market for stem cell manufacturing, capturing around 30% of the global market share as of 2023. The region benefits from a robust regulatory framework provided by the European Medicines Agency (EMA), which facilitates the approval of advanced therapy medicinal products (ATMPs). Countries like Germany, the United Kingdom, and France are leading in stem cell research and clinical applications, driven by substantial government funding and academic collaborations. The European Union has also launched initiatives aimed at promoting regenerative medicine, enhancing the market's growth prospects. Furthermore, the increasing focus on personalized medicine and regenerative therapies in Europe aligns with the growing awareness of the potential of stem cells to treat various chronic and degenerative diseases. As a result, many research institutions and biotech firms are actively engaged in developing innovative stem cell therapies and manufacturing processes, contributing to the region's overall market expansion.
Asia-Pacific
The Asia-Pacific region is poised for substantial growth in the Stem Cell Manufacturing Market, projected to account for approximately 25% of the market share by 2023. This growth is fueled by rapidly expanding healthcare infrastructure, increasing investments in biopharmaceuticals, and a rising prevalence of chronic diseases. Countries such as China and India are emerging as key players in stem cell research and manufacturing due to their large populations and growing healthcare expenditures. The Chinese government has made significant investments in regenerative medicine, fostering a supportive environment for stem cell research and clinical applications. Additionally, India is witnessing a surge in private investments and collaborations between academic institutions and industry, aimed at advancing stem cell technologies. The increasing adoption of advanced manufacturing techniques, such as automated bioprocessing, further enhances the region's capacity to meet the growing demand for stem cell therapies. As awareness of stem cell treatments improves, the Asia-Pacific region is expected to see a marked increase in clinical trials and therapeutic applications, making it a critical area for market growth in the coming years.
Key Player Analysis:
- Sartorius
- Becton, Dickinson and Company
- Fujifilm Holdings Corporation
- Lonza Group
- Stemcell Technologies
- Corning Incorporated
- Merck Group
- Thermo Fisher Scientific
- Pluristem Therapeutics Inc.
- Miltenyi Biotec
- Takeda Pharmaceutical Company Limited
- DAIICHI SANKYO COMPANY, LIMITED
- AbbVie Inc.
- Bristol-Myers Squibb Company
- GlaxoSmithKline Plc
- Danaher Corporation
- Accegen
- Cellular Engineering Technologies
Competitive Analysis:
The Stem Cell Manufacturing Market is characterized by a competitive landscape that includes a mix of established companies and emerging biotech firms. Key players such as Thermo Fisher Scientific, Lonza, and Merck are leading the market, leveraging their advanced technologies and extensive R&D capabilities to enhance production efficiency and product quality. These companies focus on strategic partnerships, collaborations, and mergers to expand their portfolios and market reach. Additionally, a number of start-ups are entering the market, driving innovation through the development of novel stem cell therapies and manufacturing techniques. Regulatory support from agencies like the FDA and EMA encourages competition by providing pathways for new entrants. However, the market also faces challenges, including high manufacturing costs and complex regulatory requirements, which can hinder smaller firms from scaling operations effectively. As a result, competitive dynamics are shifting, with larger firms often acquiring promising start-ups to integrate their technologies and accelerate product development. The emphasis on personalized medicine and sustainable manufacturing practices is further shaping competitive strategies, as companies aim to differentiate themselves in an increasingly crowded marketplace. Overall, the competitive landscape is dynamic, with ongoing innovation and collaboration driving growth and transforming the stem cell manufacturing sector.
Recent Developments:
- On May 29, 2024, REPROCELL, a biotechnology company, announced the launch of Master Cell Bank (MCB) manufacturing services for Human Induced Pluripotent Stem Cells (hiPSCs) and Human Mesenchymal Stem Cells (hMSCs) intended for therapeutic applications. By utilizing strict donor recruitment processes and adhering to global regulatory standards, REPROCELL employs a proprietary footprint-free RNA reprogramming method to produce clinically relevant hiPSCs. To enhance their capabilities, REPROCELL has integrated the Cytocentric Xvivo System model 2 from BioSpherix into their GMP Biomanufacturing Facility.
- In August 2022, Applied Stem Cell, Inc. (ASC), a Contract Research Organization (CRO) and Contract Development and Manufacturing Organization (CDMO) specializing in cell and gene therapy, expanded its Current Good Manufacturing Practice (cGMP) facility. ASC remains dedicated to supporting the research community and biotechnology sector in developing and manufacturing cell and gene products, and the expansion includes the construction of four additional cGMP cleanrooms, cryo-storage facilities, process development areas, and quality control/quality assurance spaces.
- In April 2023, the U.S. Food and Drug Administration approved Omisirge (omidubicel), a substantially modified allogeneic cord blood-based cell therapy designed to accelerate the recovery of neutrophils (a subset of white blood cells) and reduce the risk of infection. Developments like this are driving the increasing demand for stem cell therapies and culture media.
- In October 2022, Froilabo (France) launched a new range of fully automated lab-scale bioreactors. These bioreactors offer a wide array of applications suited for academia, research, process development and optimization, scale-up, and production.
- In January 2023, the life science group Sartorius extended a strategic collaboration agreement with RoosterBio Inc. to tackle purification challenges and establish scalable downstream manufacturing processes for exosome-based therapies.
Market Concentration & Characteristics:
The Stem Cell Manufacturing Market exhibits moderate concentration, with a few dominant players alongside numerous emerging companies driving innovation. Major players like Thermo Fisher Scientific, Lonza, and Merck hold significant market shares due to their advanced manufacturing technologies, extensive product offerings, and strong research and development capabilities. These established firms leverage their resources to create comprehensive solutions that cater to a wide range of applications, including regenerative medicine and therapeutic development. However, the landscape is also populated by a growing number of start-ups and small to medium enterprises focused on niche markets and innovative stem cell therapies, which contribute to a dynamic competitive environment. The market is characterized by rapid technological advancements, particularly in areas such as bioprocessing and automation, which enhance production efficiency and scalability. Additionally, regulatory compliance remains a crucial characteristic, as companies must navigate complex guidelines set by authorities like the FDA and EMA to bring their products to market. This results in a strong emphasis on quality control and validation processes, further shaping the operational dynamics within the sector. Overall, the market's concentration and characteristics reflect a balance between established leaders and innovative newcomers, fostering a vibrant ecosystem poised for growth and advancement in stem cell manufacturing.
Report Coverage:
This report provides a comprehensive analysis of the Stem Cell Manufacturing Market, covering various critical aspects that influence its growth and development. It includes detailed segmentation based on product type, technology, end-user, and region, offering insights into market dynamics across North America, Europe, Asia-Pacific, Latin America, and the Middle East and Africa. The report evaluates key drivers, trends, and challenges shaping the industry landscape, alongside a thorough competitive analysis highlighting major players and emerging start-ups. It delves into market concentration and characteristics, emphasizing the balance between established firms and innovative entrants. Furthermore, the report examines regulatory frameworks impacting the sector, assessing how compliance affects market entry and expansion. By integrating qualitative and quantitative data, this report aims to provide stakeholders with actionable insights and strategic recommendations to navigate the evolving market landscape effectively. Additionally, it forecasts market growth through 2032, identifying opportunities for investment and development in the stem cell manufacturing space. Overall, this report serves as a valuable resource for industry participants, investors, and policymakers seeking to understand the current state and future prospects of the stem cell manufacturing market.
Future Outlook:
- The Stem Cell Manufacturing Market is projected to grow significantly.
- Increasing prevalence of chronic diseases will drive demand for innovative stem cell therapies.
- Advances in technology, particularly in bioprocessing and automation, will enhance manufacturing efficiency.
- The shift towards personalized medicine will create new opportunities for tailored stem cell treatments.
- Regulatory environments are expected to evolve, providing clearer pathways for new products.
- Rising investments from both public and private sectors will bolster research and development efforts.
- Asia-Pacific will emerge as a key growth region, fueled by expanding healthcare infrastructure.
- Collaboration between biotech firms and research institutions will accelerate innovation in the field.
- Sustainable manufacturing practices will become increasingly important in response to environmental concerns.
- Overall, the market is poised for robust growth, driven by technological advancements and a focus on patient-centric solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Prevalence of Chronic Diseases
The increasing incidence of chronic diseases such as cancer, diabetes, and neurodegenerative disorders is fueling demand for innovative stem cell therapies, which in turn drives the need for advanced manufacturing capabilities to support large-scale clinical and commercial applications.
Advancements in Stem Cell Research and Technology
Breakthroughs in cell culture techniques, bioreactors, and gene editing technologies are enhancing the efficiency, scalability, and quality of stem cell production, making therapies more accessible and accelerating market growth.
Increasing Investment in Biotechnology
Rising public and private investments in biotechnology, including significant funding for stem cell research and manufacturing infrastructure, are enabling companies to expand production capacity and develop novel therapies, supporting robust market expansion.
Supportive Regulatory Environment
Clearer regulatory frameworks and expedited approval pathways from agencies like the FDA and EMA are reducing barriers to market entry, encouraging innovation, and increasing investor confidence in stem cell manufacturing.
Shift Toward Personalized Medicine
The growing emphasis on personalized medicine is driving demand for patient-specific stem cell therapies, prompting manufacturers to adopt flexible and advanced production technologies that can accommodate individualized treatment approaches.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current value of the Stem Cell Manufacturing Market?
How fast is the market expected to grow?
What is driving the growth of this market?
Which region currently leads the market?
Which region is expected to see substantial growth?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Adult Stem Cells
- 1.2.2 Embryonic Stem Cells
- 1.2.3 Induced Pluripotent Stem Cells (iPSCs)
- 1.3 By End-User
- 1.3.1 Hospitals
- 1.3.2 Research Laboratories
- 1.3.3 Biotechnology Companies
- 1.3.4 Pharmaceutical Companies
- 1.4 By Technology
- 1.4.1 Cell Culture Techniques
- 1.4.2 Bioreactors
- 1.4.3 Separation Technologies
- 1.4.4 Cryopreservation Technologies
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2032: USD 12,775 million → Forecast year: USD 32,199.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2032
- 3.3 Forecast Market Size
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Stem Cell Manufacturing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Stem Cell Manufacturing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Stem Cell Manufacturing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Stem Cell Manufacturing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Stem Cell Manufacturing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Stem Cell Manufacturing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Stem Cell Manufacturing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Stem Cell Manufacturing Market Outlook
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2032: USD 12,775 million → Forecast year: USD 32,199.6 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2032
- 11.2 Market Forecast
- 11.2.1 Revenue Forecast
- 11.2.2 Volume Forecast
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Stem Cell Manufacturing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2032
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast
- 12.3.4 Volume Forecast
- 12.3.5 Base-Year Market Share, 2032
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Adult Stem Cells
- 12.3.7.2 Embryonic Stem Cells
- 12.3.7.3 Induced Pluripotent Stem Cells (iPSCs)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast
- 12.4.4 Volume Forecast
- 12.4.5 Base-Year Market Share, 2032
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Research Laboratories
- 12.4.7.3 Biotechnology Companies
- 12.4.7.4 Pharmaceutical Companies
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast
- 12.5.4 Volume Forecast
- 12.5.5 Base-Year Market Share, 2032
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Cell Culture Techniques
- 12.5.7.2 Bioreactors
- 12.5.7.3 Separation Technologies
- 12.5.7.4 Cryopreservation Technologies
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Stem Cell Manufacturing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Stem Cell Manufacturing Geographic Market Outlook
- 14.1 Regional Market Size and Share, 2032
- 14.2 Regional Market Forecast
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Stem Cell Manufacturing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Stem Cell Manufacturing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2032
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Thermo Fisher Scientific
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Lonza Group
- 18.4 Merck Group
- 18.5 Sartorius
- 18.6 Becton, Dickinson and Company
- 18.7 Fujifilm Holdings Corporation
- 18.8 Stemcell Technologies
- 18.9 Corning Incorporated
- 18.10 Miltenyi Biotec
- 18.11 Takeda Pharmaceutical Company Limited
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

