
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Strapping And Banding Equipment Market Size 2024 | USD 2,483.1 Million |
| Strapping And Banding Equipment Market, CAGR | 5% |
| Strapping And Banding Equipment Market Size 2032 | USD 3,668.66 Million |
Market Overview:
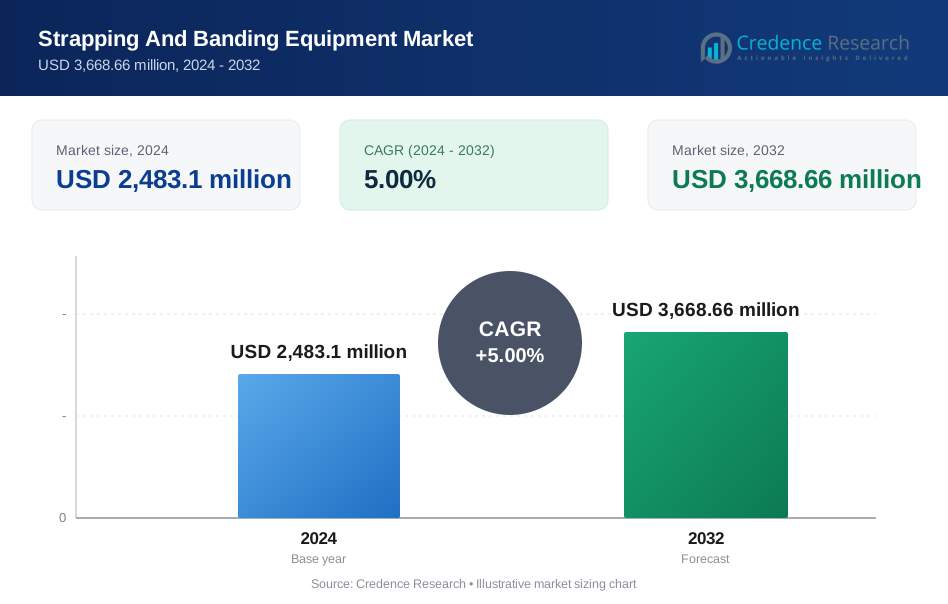
The global Strapping And Banding Equipment Market size was valued at USD 2,483.1 million in 2024 and is anticipated to reach USD 3,668.66 million by 2032, at a CAGR of 5% during the forecast period (2024-2032).
The market growth is driven by the increasing demand for strapping and banding equipment across industries such as packaging, logistics, automotive, and manufacturing, where efficient and reliable packaging solutions are critical. Market drivers include the growing e-commerce sector, which is expanding the need for robust packaging solutions to protect products during transit. Additionally, the rise in the global manufacturing and logistics sectors is contributing to the increasing adoption of automated strapping and banding systems. These systems offer higher efficiency, precision, and scalability in packaging operations. The increased focus on sustainability, coupled with advances in recyclable and eco-friendly materials, further accelerates the adoption of strapping and banding equipment as companies strive to meet sustainability goals.
Regionally, North America dominates the Strapping and Banding Equipment Market, followed closely by Europe. North America’s market share is attributed to the significant presence of key players, robust industrial infrastructure, and high demand from e-commerce and retail sectors. Europe also showcases considerable growth, driven by the manufacturing and automotive sectors, where strapping and banding solutions are essential for packaging and logistics. Asia Pacific is expected to witness the highest growth rate due to the rapid industrialization, increasing manufacturing output, and expanding e-commerce activities in countries like China and India.
Market Insights:
- The market is expected to grow from USD 2,483.1 million in 2024 to USD 3,668.66 million by 2032, driven by rising demand for secure packaging solutions.
- Increasing e-commerce and global trade volumes are driving demand for robust packaging systems to handle high shipping volumes.
- Advancements in automated strapping equipment enhance efficiency and reduce labor costs, boosting adoption across industries.
- The high cost of advanced strapping equipment can deter small-scale manufacturers from investing in such technologies.
- Leads the market due to established manufacturing and logistics infrastructure.
- The fastest-growing region, driven by industrialization and expanding e-commerce in China and India.
- Rising demand for eco-friendly strapping materials aligns with global environmental regulations, creating new opportunities.
Market Drivers:
Growing Demand for E-Commerce and Logistics
The expansion of e-commerce and the increasing volume of online shopping are driving demand for effective packaging solutions. For instance, companies like Loos Machine have developed advanced banding and strapping systems tailored for the logistics and e-commerce sectors. As the need for faster, safer, and more efficient shipping increases, strapping and banding equipment becomes crucial in ensuring products are securely packaged and protected during transit.
Automation in Packaging Processes
Manufacturers are increasingly adopting automated packaging systems to improve productivity, reduce labor costs, and minimize human error. Automated strapping and banding equipment offers higher precision, faster processing speeds, and seamless integration into production lines, contributing to the overall growth of the market.
Sustainability and Eco-Friendly Packaging Solutions
Environmental concerns have prompted businesses to focus on using recyclable materials and reducing waste. Strapping and banding equipment that utilizes biodegradable and eco-friendly materials is gaining popularity. This shift towards sustainable packaging solutions is driving market growth as businesses strive to meet both regulatory standards and consumer expectations for eco-conscious practices.
Industrial Growth and Manufacturing Expansion
The global expansion of industries such as automotive, electronics, and consumer goods is directly influencing the demand for strapping and banding equipment. For instance, the expansion of industries like automotive and electronics has driven the adoption of advanced strapping equipment. As manufacturing processes scale up, companies require efficient and reliable packaging systems to handle increased product volumes, boosting the demand for advanced strapping equipment.
Market Trends
Technological Advancements in Equipment The Strapping and Banding Equipment Market is witnessing continuous innovations aimed at improving efficiency and user experience. Advanced features such as intelligent sensors, adjustable tension settings, and enhanced automation are making strapping equipment more adaptable to different production environments and packaging needs.
Integration of IoT for Smart Packaging Solutions
The integration of the Internet of Things (IoT) into strapping and banding equipment is transforming how these systems are monitored and controlled. IoT-enabled devices allow manufacturers to track the performance of their equipment in real-time, gather data for predictive maintenance, and improve overall operational efficiency.
Shift Towards High-Speed and Low-Noise Equipment As businesses aim to enhance their productivity while maintaining a comfortable working environment, there is a growing trend toward high-speed strapping machines that operate with minimal noise. For instance, INGSOL has developed IoT-enabled smart packaging systems that incorporate real-time tracking and monitoring features. These machines are designed to meet the increasing demand for faster packaging processes without compromising on the quality of the strapping.
Customization and Versatility in Equipment Design Manufacturers are increasingly focusing on offering customizable strapping and banding solutions that cater to diverse packaging requirements. Adjustable features such as strap width, length, and tension settings are in high demand, allowing companies to tailor equipment to specific needs across different industries.
Market Challenges Analysis
Regulatory Compliance Complexity
The strapping and banding equipment market faces stringent regulatory challenges, particularly due to evolving safety and compliance requirements. For instance, the Ministry of Heavy Industry’s (MHI) new Machinery and Electrical Equipment Safety Order affects manufacturers, with 90% classified as MSMEs, increasing the burden of compliance. Additionally, the Bureau of Indian Standards (BIS) certification mandates additional regulatory approvals for manufacturers targeting both domestic and export markets, raising operational costs and administrative complexity. In North America, the Federal Motor Carrier Safety Administration (FMCSA) enforces strict cargo securement standards, requiring continuous updates to equipment specifications and safety protocols, further complicating market adoption. The significant capital investment required for automated strapping equipment presents barriers for small and medium-sized enterprises (SMEs). National Association of Chain Manufacturers (NACM) and the Web Sling and Tiedown Association mandate frequent updates to safety features and equipment standards, increasing ongoing maintenance expenses. Companies must allocate resources for compliance with these safety protocols, affecting operational profitability and long-term ROI. The high costs of integrating automation, coupled with regulatory compliance requirements, create financial constraints for smaller manufacturers.
Technical Expertise and Training Requirements
The shortage of skilled professionals trained in operating and maintaining automated strapping systems poses a critical challenge to market growth. National Accreditation Board for Certification Bodies (NABCB) highlights a shortage of certified technical professionals, affecting nearly 50,000 types of machinery across 463 tariff lines. The complexity of automated systems requires extensive training and expertise, making it difficult for companies with limited technical resources to optimize equipment efficiency. This gap in skilled labor affects the proper implementation, troubleshooting, and maintenance of automated strapping solutions. Strict cargo securement regulations impact material performance and flexibility in strapping solutions. FMCSA’s cargo securement rules impose stringent requirements on tiedown devices, affecting the operational flexibility of transport and logistics industries. Equipment must comply with specific working load limits and safety standards, with unmarked tiedowns facing additional restrictions and lower working load limit ratings. These limitations particularly affect industries requiring specialized strapping solutions for varying product sizes and shapes, challenging manufacturers to develop more adaptive and compliant solutions.
Market Opportunities
The Strapping and Banding Equipment Market presents substantial growth opportunities, driven by the expanding global e-commerce industry and rising demand for efficient packaging solutions across manufacturing, logistics, and construction sectors. As supply chains grow increasingly complex, the need for secure and durable packaging methods becomes critical, offering opportunities for manufacturers to develop innovative strapping equipment tailored to diverse industry needs. The adoption of automated strapping systems is a key opportunity, as businesses seek to optimize packaging processes, reduce labor costs, and enhance productivity. Integration of smart technologies, such as IoT-enabled strapping machines, enables real-time monitoring and maintenance, further boosting demand among forward-looking enterprises.
Emerging markets, particularly in Asia-Pacific and Latin America, offer significant potential due to rapid industrialization and infrastructure development. Countries like China and India are witnessing a surge in demand for cost-effective strapping solutions to support their booming e-commerce and manufacturing industries. Additionally, the growing emphasis on sustainability provides opportunities for manufacturers to innovate with recyclable and biodegradable strapping materials, aligning with global environmental goals and stringent regulations. Companies that focus on energy-efficient equipment, customizable solutions, and localized production to meet specific regional demands are well-positioned to capitalize on these opportunities, ensuring sustained market growth in the coming years.
Market Segmentation Analysis:
By Automation Type
The strapping and banding equipment market is segmented based on automation type, including manual, semi-automatic, and fully automatic systems. Fully automatic strapping machines account for a significant share, as industries seek high-speed and labor-efficient packaging solutions. For instance, fully automatic equipment is expected to dominate the market, holding nearly 49% of the total share by 2033, as manufacturers adopt automation to streamline packaging operations. Semi-automatic systems remain essential for mid-scale businesses, offering cost-effective solutions for moderate production volumes. Manual strapping tools continue to be widely used in smaller operations and remote locations, where automation is not yet feasible.
By Product Type
The market is further divided by product type, including polypropylene (PP) strapping, polyester (PET) strapping, steel strapping, and corded strapping. Polyester (PET) strapping is gaining rapid adoption, replacing steel in many applications due to its high tensile strength, durability, and recyclability. For instance, advancements in reinforced PET strapping have improved break strength by 50% while reducing material weight by 30%, making it a preferred choice in logistics and industrial packaging. Steel strapping remains dominant in heavy industries such as construction and metal processing, where high-strength load securing is required.
By End User
End-user industries include logistics & transportation, manufacturing, construction, food & beverage, and consumer goods. The logistics and transportation sector accounts for the largest share, driven by the rapid expansion of e-commerce and global trade. For instance, horizontal strapping machines dominate the market with a 67.30% share in 2024, particularly in logistics and shipping applications. The manufacturing sector also contributes significantly, using automated strapping systems to enhance production efficiency and reduce packaging waste. The construction industry relies on strapping equipment to secure heavy materials such as steel, timber, and cement, ensuring safe transit and storage.
Segmentations:
By Automation Type:
- Fully-Automatic
- Semi-Automatic
- Manual Automation
By Product Type:
- Horizontal
- Vertical
By End Use:
- Food & Beverages
- Consumer Electronics
- Household
- E-commerce
- Automobile
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds 35% of the global market share, driven by an advanced logistics infrastructure, a well-established manufacturing sector, and a strong emphasis on automation in packaging processes. Companies in the region are integrating high-speed, automated strapping solutions to enhance operational efficiency and meet the high-volume demands of logistics and transportation industries, ensuring faster processing times and reduced labor costs.
Europe
Europe accounts for 30% of the global market share, supported by stringent packaging standards and a robust industrial sector. France and the UK follow closely, leveraging advanced strapping technologies to improve industrial packaging and reduce material waste. Additionally, Europe’s well-established automotive and construction industries further drive demand for high-strength strapping solutions, ensuring durability in product transportation and secure load containment.
Asia-Pacific
Asia-Pacific is the fastest-growing region, contributing 25% of the market share, driven by rapid industrialization and a booming e-commerce sector in China and India. India’s logistics sector, growing at over 10% annually, is adopting modern packaging solutions to improve efficiency and scalability, particularly as online retail and last-mile delivery services expand across the country.
Latin America & Middle East & Africa
Latin America and the Middle East & Africa collectively hold 10% of the global market share, showcasing gradual growth driven by infrastructure development and modernization of logistics networks. Similarly, the UAE and South Africa are key contributors in the Middle East & Africa, adopting strapping technologies to enhance logistics efficiency and comply with global trade standards, ensuring seamless product movement across supply chains.
Key Player Analysis:
- Signode Industrial Group LLC
- Samuel Strapping Systems
- Fromm Packaging Systems
- Polychem Corporation
- Mosca GmbH
- Cyklop International
- StraPack, Inc.
- MJ Maillis Group
- Titan Umreifungstechnik GmbH & Co. KG
- Dynaric, Inc.
Competitive Analysis:
The Strapping and Banding Equipment Market is highly competitive, with key players such as Signode Industrial Group LLC, Samuel Strapping Systems, and Fromm Packaging Systems dominating the industry through advanced product offerings and global distribution networks. These companies prioritize innovation, focusing on automation and eco-friendly solutions to meet the evolving demands of industries such as logistics, manufacturing, and construction. Mid-tier companies like StraPack, Inc. and Polychem Corporation are expanding their market presence by providing cost-effective solutions tailored for small and medium enterprises (SMEs). Additionally, regional players are emphasizing localized production and sustainable materials to align with environmental regulations. The competitive landscape is further shaped by strategic partnerships with e-commerce giants and increased investment in R&D for IoT-enabled strapping solutions, driving technological advancements and expanding market opportunities.
Recent Developments:
- In October 2024, Signode introduced the BXT4 Battery Hand Tool for Plastic Strapping, featuring EasyTrigger™ Technology for enhanced usability and performance.
- In October 2024, Mosca showcased the HUG battery strapping tool and the TR-Connect intelligent strapping machine at the All4Pack tradeshow in Paris, highlighting advancements in flexibility and IoT integration.
- In 2024, StraPack continued to lead in strapping machine innovation, offering high-speed banding machines like the OB360N, capable of up to 30 cycles per minute, catering to diverse packaging needs.
- In December 2022, Signode launched the BST Battery Powered Tool for Sealless Steel Strapping, designed for demanding applications with an ergonomic design and enhanced productivity features.
Market Concentration & Characteristics:
The Strapping and Banding Equipment Market is moderately fragmented, with both global leaders and regional players competing to address diverse industry needs. Major companies such as Signode Industrial Group LLC, Samuel Strapping Systems, and Mosca GmbH dominate the market, leveraging advanced technologies, extensive distribution networks, and a strong focus on innovation to maintain their competitive edge. These players invest heavily in automation, sustainability, and IoT-enabled solutions, catering to the growing demand for efficiency and eco-friendly packaging. Mid-tier companies like StraPack, Inc. and Polychem Corporation focus on cost-effective and customizable offerings for small and medium-sized enterprises. The market is characterized by rising adoption of automated systems, increasing emphasis on recyclable materials, and growing demand across logistics, manufacturing, and construction sectors. Intense competition drives continuous product development, while regional players capitalize on localized needs and cost advantages to enhance market penetration.
Report Coverage:
The research report offers an in-depth analysis based on automation type, product type, end use, and region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for automated strapping and banding equipment will grow as industries prioritize operational efficiency and reduced labor costs.
- Rising e-commerce activities globally will drive the adoption of durable strapping solutions to secure high shipping volumes.
- The focus on sustainability will increase demand for recyclable and biodegradable strapping materials, aligning with global environmental regulations.
- Advancements in IoT-enabled and smart strapping machines will enable real-time monitoring and predictive maintenance, enhancing productivity.
- Emerging markets in Asia-Pacific, Latin America, and Africa will present significant opportunities due to rapid industrialization and infrastructure development.
- Manufacturers will invest in modular and energy-efficient strapping systems to meet the diverse needs of the logistics and transportation sectors.
- Growing demand from the construction industry for heavy-duty steel strapping solutions will support market expansion.
- Partnerships between packaging equipment manufacturers and logistics firms will foster the development of customized strapping solutions.
- Technological innovations, such as automated tensioning and sealing mechanisms, will enhance the safety and reliability of strapping processes.
- Increasing adoption of strapping solutions in the food and beverage sector for secure packaging and distribution will further bolster market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Strapping and Banding Equipment Market?
What factors are driving the growth of the Strapping and Banding Equipment Market?
What are some challenges faced by the Strapping and Banding Equipment Market?
Who are the major players in the Strapping and Banding Equipment Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Strapping And Banding Equipment Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Strapping And Banding Equipment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,483.1 million → 2032: USD 3,668.66 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Strapping And Banding Equipment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Strapping And Banding Equipment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Strapping And Banding Equipment Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Strapping And Banding Equipment Market Drivers
- 3.3 Strapping And Banding Equipment Market Restraints & Challenges
- 3.4 Strapping And Banding Equipment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Strapping And Banding Equipment Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Strapping And Banding Equipment Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Strapping And Banding Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Strapping And Banding Equipment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Strapping And Banding Equipment Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Strapping And Banding Equipment. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Strapping And Banding Equipment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Strapping And Banding Equipment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Strapping And Banding Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Strapping And Banding Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Strapping And Banding Equipment
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Strapping And Banding Equipment Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Strapping And Banding Equipment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Strapping And Banding Equipment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Strapping And Banding Equipment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Strapping And Banding Equipment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Strapping And Banding Equipment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Strapping And Banding Equipment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Strapping And Banding Equipment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
