
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
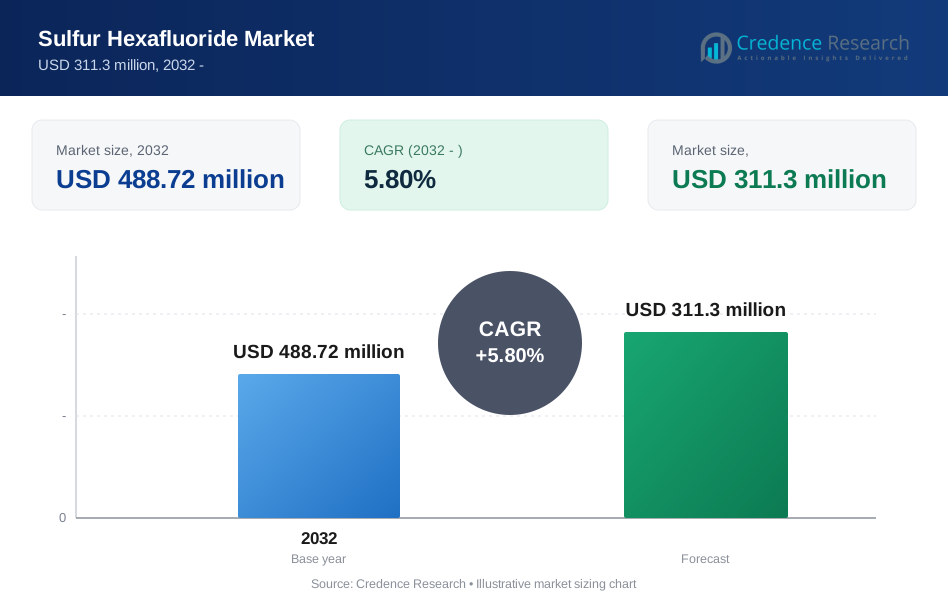
| Sulfur Hexafluoride Market Size 2024 | USD 488.72 million |
| Sulfur Hexafluoride Market, CAGR | 5.80% |
| Sulfur Hexafluoride Market Size 2032 | USD 311.3 million |
Market Overview:
The Sulfur Hexafluoride Market is experiencing notable growth, driven by its increasing applications in various industries such as electronics, healthcare, and power utilities. As of 2024, the global Sulfur Hexafluoride Market is valued at approximately USD 488.72 million and is projected to grow at a compound annual growth rate (CAGR) of 5.80% over the forecast period, reaching around USD 311.3 million by 2032. This expansion is reflective of the rising demand for sulfur hexafluoride in high-voltage electrical equipment, as well as its utility in medical applications such as ultrasound imaging.
Several key factors are propelling market growth. The growing need for reliable insulation mediums in the electrical sector is a primary driver, particularly as global energy demands increase. Furthermore, the environmentally friendly properties of sulfur hexafluoride compared to other insulation gases are boosting its adoption. The technology advancements in the production and recycling processes of sulfur hexafluoride are also contributing positively to market dynamics, enhancing its appeal as a sustainable option.
Regionally, North America currently dominates the Sulfur Hexafluoride Market, driven by the high demand from the electrical and electronics industries, alongside stringent regulations favoring high-performance insulating gases. Europe follows closely, with increasing investments in renewable energy sources and the expansion of electrical infrastructure. The Asia-Pacific region is anticipated to witness substantial growth during the forecast period, fueled by rapid industrialization, expanding healthcare applications, and heightened awareness regarding safety and environmental standards in electrical applications. Emerging economies within this region, particularly China and India, are poised to offer significant growth opportunities, supported by their burgeoning industrial sectors and commitment to improving infrastructure.
Market Drivers:
Growing Demand in Electrical Applications:
The increasing reliance on renewable energy sources and high-voltage electrical systems is significantly driving the demand for sulfur hexafluoride (SF6) in electrical applications. SF6 is widely used as an insulator in high-voltage equipment such as circuit breakers and gas-insulated switchgear (GIS). According to the International Energy Agency (IEA), the global demand for electricity is expected to grow by approximately 25% by 2030. This increase in electricity demand necessitates the deployment of efficient electrical infrastructure, where SF6 plays a crucial role due to its excellent insulating properties. For instance, the International Institute for Sustainable Development (IISD) notes that investments in clean energy technologies are expected to rise by 30% from 2020 to 2025, further propelling the use of SF6 in the electrical sector. Additionally, the U.S. Department of Energy (DOE) emphasizes that improving the reliability and efficiency of power transmission will lead to greater adoption of SF6 in electrical applications, enhancing grid resilience.
Rising Adoption in the Semiconductor Industry:
The semiconductor industry is another significant driver for the sulfur hexafluoride market. SF6 is utilized in the production of semiconductors as a plasma etching gas, which is critical in the fabrication of integrated circuits and microchips. According to the Semiconductor Industry Association (SIA), the global semiconductor market is projected to grow at a compound annual growth rate (CAGR) of 5.1% from 2021 to 2026. This growth is primarily attributed to the increasing demand for electronic devices, including smartphones, tablets, and wearable technology. For instance, a report by the World Semiconductor Trade Statistics (WSTS) highlights that the demand for semiconductors surged by 25% in 2021, underscoring the critical role of SF6 in manufacturing processes. Furthermore, the U.S. National Institute of Standards and Technology (NIST) projects that advancements in semiconductor technology will further drive the requirement for SF6, as it remains essential for high-performance fabrication techniques.
Regulatory Support and Environmental Initiatives:
Regulatory frameworks and environmental initiatives are playing a pivotal role in shaping the sulfur hexafluoride market. Many governments and international bodies are implementing stricter regulations to manage greenhouse gas emissions. SF6, despite its greenhouse gas potential, is essential for many applications where no viable alternatives currently exist. The Intergovernmental Panel on Climate Change (IPCC) has highlighted the importance of SF6 in achieving efficiency and reliability in electrical systems. For instance, the European Union's Green Deal aims to reduce greenhouse gas emissions by at least 55% by 2030, which includes strategies for managing SF6 use in the electrical sector. The U.S. Environmental Protection Agency (EPA) is actively monitoring and regulating SF6 emissions, promoting the development of innovative technologies that reduce SF6 leakage while maintaining performance in electrical applications. The EPA's reports indicate that improved SF6 management can lead to reductions in greenhouse gas emissions by up to 40% in certain sectors.
Technological Advancements in SF6 Applications:
Technological advancements are significantly influencing the sulfur hexafluoride market by enhancing its applications and reducing environmental impacts. Innovations in SF6 handling and recycling technologies are improving the lifecycle management of SF6, thus making its use more sustainable. The introduction of new gas mixtures that include SF6 is also gaining traction, as these alternatives can provide similar insulating properties while reducing overall SF6 usage. For instance, a study by the U.S. Department of Energy (DOE) highlighted that advanced monitoring systems can reduce SF6 leakage by up to 50% in electrical equipment, leading to lower emissions without compromising performance. The National Renewable Energy Laboratory (NREL) further reports that ongoing research into alternative technologies may result in a 25% reduction in the reliance on SF6 by 2035, ensuring that its use aligns with sustainability goals.
Market Trends:
Shift Toward Sustainable Alternatives:
A significant trend in the sulfur hexafluoride (SF6) market is the increasing focus on sustainable alternatives due to environmental concerns. While SF6 is highly effective as an insulating gas, it is also a potent greenhouse gas. As regulatory pressures mount, industries are actively seeking substitutes that offer similar performance with reduced environmental impact. The International Energy Agency (IEA) emphasizes the importance of transitioning to low-carbon technologies, which has prompted research into alternative gas mixtures that can replace or reduce SF6 usage. For instance, the European Commission has allocated funding for projects that focus on developing eco-friendly alternatives to SF6 in electrical applications, with the aim of reducing greenhouse gas emissions by 50% by 2030. These initiatives are crucial for identifying viable substitutes that can maintain the efficiency and reliability of electrical equipment while addressing climate goals. This shift not only fulfills regulatory compliance but is also seen as a strategic move to enhance corporate sustainability profiles, leading to potential long-term cost savings.
Enhanced Lifecycle Management Practices:
Another notable trend is the emphasis on enhanced lifecycle management practices for SF6. Companies are increasingly investing in technologies that monitor and manage the use of SF6 throughout its lifecycle, from production to disposal. This trend is driven by the need to comply with stringent environmental regulations and reduce operational costs associated with SF6 emissions. For instance, the U.S. Environmental Protection Agency (EPA) has reported that companies adopting advanced monitoring systems can achieve a reduction in SF6 emissions by up to 40%. The EPA's initiatives promote best practices in SF6 management, including improved leakage detection technologies and recycling methods. These practices are designed to minimize the release of SF6 into the atmosphere and extend the lifespan of equipment that uses this gas. As organizations implement these enhanced practices, they are likely to experience both environmental benefits and cost efficiencies, contributing to a more sustainable industry overall.
Market Challenge Analysis:
Regulatory and Environmental Pressures:
One of the primary challenges facing the sulfur hexafluoride (SF6) market is the increasing regulatory scrutiny and environmental pressures associated with its use. As a potent greenhouse gas, SF6 has a global warming potential significantly higher than that of carbon dioxide, prompting governments and international organizations to impose stricter regulations on its emissions. The Intergovernmental Panel on Climate Change (IPCC) has highlighted the urgency of addressing SF6 emissions, leading to initiatives aimed at reducing its impact on climate change. For instance, the European Union’s F-Gas Regulation requires significant reductions in the use of fluorinated gases, including SF6, compelling industries to explore alternatives or invest in technologies to mitigate emissions. This regulatory environment presents a dual challenge for companies relying on SF6 for various applications, particularly in the electrical and semiconductor sectors. The compliance costs associated with monitoring and managing SF6 emissions can strain operational budgets, especially for small to medium-sized enterprises. Moreover, the ongoing search for viable alternatives to SF6 adds another layer of complexity, as companies must balance performance with environmental responsibility. Research and development (R&D) efforts to find substitutes can be costly and time-consuming, with uncertainties regarding the long-term effectiveness and reliability of these alternatives. As such, organizations must navigate these regulatory challenges while maintaining operational efficiency and competitiveness in the market.
Technological Limitations and Market Adoption:
Another significant challenge facing the SF6 market is the technological limitations surrounding the adoption of alternatives. While research is ongoing to develop eco-friendly substitutes, many of these emerging technologies are still in the experimental stages and may not yet meet the performance standards required for critical applications such as high-voltage electrical systems. For instance, although gas mixtures that include lower levels of SF6 have shown promise, they often lack the same insulating properties and reliability that industries have come to expect from pure SF6. This uncertainty can hinder the widespread adoption of alternative solutions, as companies may be reluctant to compromise on safety and efficiency. the transition to new technologies involves substantial investment in training, infrastructure, and equipment. Companies must ensure that their workforce is adequately trained to handle these new materials and technologies, which can add to the overall costs and time required for implementation. Additionally, the initial resistance to change from established practices can slow down the adoption rate of alternative solutions. As organizations weigh the benefits of transitioning away from SF6 against the potential disruptions to their operations, the challenge remains to foster an environment that encourages innovation while ensuring that any new solutions can meet the stringent demands of the industry. This balancing act will be crucial for the future of the SF6 market as it confronts both regulatory pressures and the need for technological advancements.
Market Segmentation Analysis:
By Type
The sulfur hexafluoride market can be segmented based on the type of application. The most common types include electrical applications, semiconductor manufacturing, and other industrial uses. Electrical applications dominate the market, utilizing SF6 for its exceptional insulating properties in high-voltage equipment like circuit breakers and gas-insulated switchgear. This segment is critical for maintaining the reliability of electrical grids, especially as the demand for renewable energy sources increases. The semiconductor manufacturing segment is also significant, as SF6 is used as a plasma etching gas, essential for producing microchips and integrated circuits. Other industrial applications include use in medical technology and in tracer gas studies, which together contribute to the overall market but represent a smaller share compared to electrical and semiconductor applications.
By Technology
The technology segment of the sulfur hexafluoride market includes various methods of usage and management. This encompasses traditional SF6 technology, advanced monitoring systems, and emerging alternatives such as gas mixtures that combine SF6 with other gases. Traditional SF6 technology has been the mainstay due to its high performance in electrical insulation and arc interruption. However, as environmental concerns grow, the market is witnessing a shift toward advanced monitoring systems that enhance lifecycle management and reduce emissions. These systems enable real-time tracking of SF6 levels, ensuring compliance with environmental regulations. Additionally, ongoing research into alternative technologies aims to develop gas mixtures that can provide similar performance while reducing the overall SF6 footprint, reflecting the industry's commitment to sustainability and innovation.
By End-User
The end-user segmentation of the sulfur hexafluoride market primarily includes utilities, semiconductor manufacturers, and industrial sectors. Utilities represent the largest share, as they rely heavily on SF6 for the safe and efficient operation of electrical distribution systems. The semiconductor manufacturing sector is also a key end-user, driven by the increasing demand for electronic devices and the need for high-precision manufacturing processes. Other industrial sectors that utilize SF6 include research laboratories and various manufacturing entities that require specialized gas applications. As industries evolve and seek sustainable solutions, the end-user landscape may shift, with more emphasis on regulatory compliance and the adoption of environmentally friendly technologies, influencing overall demand for SF6 in the market.
Segmentation:
Based on Product Type:
- Electrical Applications
- Semiconductor Manufacturing
- Other Industrial Uses
Based on Technology:
- Traditional SF6 Technology
- Advanced Monitoring Systems
- Alternative Gas Mixtures
Based on End-User:
- Utilities
- Semiconductor Manufacturers
- Research Laboratories
- Other Industrial Sectors
Based on Region:
- North America
- United States
- Canada
- Europe
- Germany
- France
- United Kingdom
- Asia-Pacific
- China
- India
- Japan
- Latin America
- Brazil
- Mexico
- Middle East & Africa
- South Africa
- United Arab Emirates
Regional Analysis:
North America
North America is a key region in the sulfur hexafluoride (SF6) market, accounting for approximately 30% of the global market share. The United States is the primary driver of this market, largely due to its extensive electrical infrastructure and the growing emphasis on renewable energy sources. Regulatory bodies, such as the U.S. Environmental Protection Agency (EPA), have implemented stringent regulations regarding greenhouse gas emissions, which have prompted utilities to adopt SF6 for its superior insulating properties while also focusing on effective lifecycle management practices. the increasing investments in smart grid technologies and the modernization of existing power systems further bolster the demand for SF6 in the region. The rise in electrical equipment installation, especially in high-voltage applications, is expected to sustain this trend. Furthermore, significant R&D initiatives aimed at improving SF6 handling and recycling technologies are being undertaken by companies, enhancing operational efficiencies and reducing environmental impacts. As a result, the North American market is poised for steady growth, driven by regulatory compliance and technological advancements.
Europe
Europe represents another significant segment of the sulfur hexafluoride market, capturing around 25% of the global market share. The region is characterized by strict environmental regulations aimed at reducing greenhouse gas emissions, particularly through the European Union's F-Gas Regulation. This regulatory framework has led to increased scrutiny on the use of SF6, compelling industries to adopt best practices in monitoring and managing its use. Countries such as Germany, France, and the United Kingdom are at the forefront of this trend, implementing innovative technologies that promote sustainability while maintaining performance standards. The European market is also witnessing a growing shift toward alternative insulating gases and advanced monitoring systems that minimize SF6 emissions. With substantial investments in renewable energy infrastructure and energy efficiency initiatives, the demand for SF6 in electrical applications remains strong. Additionally, European companies are actively participating in research initiatives aimed at developing eco-friendly alternatives to SF6, further shaping the market dynamics in the region.
Asia-Pacific
The Asia-Pacific region is experiencing robust growth in the sulfur hexafluoride market, currently holding approximately 35% of the global market share. Countries such as China and India are driving this growth, fueled by rapid industrialization, urbanization, and an increasing demand for electricity. The surge in construction and infrastructure development projects in these countries necessitates the deployment of efficient electrical systems, where SF6 plays a critical role due to its superior insulating properties. China, in particular, is investing heavily in expanding its electrical grid and renewable energy sources, which is expected to significantly boost the demand for SF6 in high-voltage applications. Additionally, the semiconductor manufacturing sector in the Asia-Pacific region is also expanding, driven by the rising demand for electronic devices, further solidifying SF6's position in the market. However, challenges related to environmental regulations are emerging, pushing companies to explore alternatives and improve their SF6 management practices. The ongoing technological advancements and investments in sustainability will be crucial for the region's long-term growth in the sulfur hexafluoride market.
Key Player Analysis:
- Solvay (Belgium)
- SHOWA DENKO K.K. (Japan)
- Concorde Specialty Gases, Inc (US)
- The Linde Group (Ireland
- Advanced Specialty Gases (US)
- Matheson Tri-Gas, Inc (US)
- Air Products and Chemicals, Inc (US)
- Electronic Fluorocarbons, LLC (US)
- Praxair Technology, Inc (US)
- Bengal Gases (India)
- Ajay Air Products Pvt. Ltd (India)
- PURITYPLUS SPECIALTY GASES (US)
Competitive Analysis:
The competitive landscape of the sulfur hexafluoride (SF6) market is characterized by several key players, each striving to maintain or enhance their market position amid growing regulatory pressures and environmental concerns. Major companies such as Siemens, Schneider Electric, and Mitsubishi Electric dominate the market, leveraging their technological expertise and extensive distribution networks to offer innovative SF6 solutions and services. These companies are increasingly investing in research and development to create advanced monitoring systems and eco-friendly alternatives to SF6, aligning with global sustainability goals. Additionally, smaller players are emerging, focusing on niche markets and developing specialized applications for SF6, thereby intensifying competition. Strategic partnerships and collaborations are also becoming prevalent as companies seek to combine resources and expertise to tackle environmental challenges while expanding their market reach. Regulatory compliance is a critical factor influencing competitive strategies, prompting firms to adopt best practices in SF6 management and invest in technologies that reduce emissions. This landscape is further complicated by the growing interest in alternative insulating gases, which poses a potential threat to traditional SF6 applications. As the market evolves, companies must adapt to changing regulations, invest in innovation, and differentiate their offerings to stay competitive, ensuring that they meet the dual demands of operational efficiency and environmental responsibility in an increasingly scrutinized market.
Recent Developments:
- In 2022, DUAL-ADE, a leading provider of high-voltage equipment, partnered with Nuventura, a pioneer in sustainable switchgear technology, to introduce innovative SF6-free Gas Insulated Switchgear (GIS) solutions to the North American market. This collaboration seeks to revolutionize the electrical industry by providing environmentally friendly alternatives to traditional SF6-based GIS systems.
Market Concentration & Characteristics:
The sulfur hexafluoride (SF6) market exhibits a moderate level of concentration, dominated by a few major players while still accommodating smaller firms and emerging competitors. Leading companies such as Siemens, Schneider Electric, and Mitsubishi Electric command significant market shares due to their established reputations, technological advancements, and comprehensive service offerings. These firms are investing heavily in research and development to enhance their SF6 applications and to create alternatives that align with evolving environmental regulations. The market characteristics reflect a strong emphasis on innovation, driven by the need for efficient insulating solutions in high-voltage applications and semiconductor manufacturing. the competitive landscape is shaped by increasing regulatory scrutiny surrounding greenhouse gas emissions, prompting firms to adopt more sustainable practices. This has led to a growing interest in advanced monitoring systems and alternative insulating gases, fostering an environment of continuous improvement and adaptation. Furthermore, the market is characterized by strategic partnerships and collaborations among industry players, as companies seek to pool resources for research initiatives and to expand their geographic reach. While the market is concentrated among a few key players, the presence of smaller, niche firms contributes to diversity and innovation, enabling the industry to respond effectively to both regulatory challenges and market demands. Overall, the SF6 market reflects a dynamic interplay of competition, regulation, and technological advancement, driving continuous evolution in both products and practices.
Report Coverage:
This report provides a comprehensive analysis of the sulfur hexafluoride (SF6) market, covering key aspects such as market drivers, challenges, segmentation, regional dynamics, and competitive landscape. It examines the growing demand for SF6 in electrical applications and semiconductor manufacturing, while also highlighting the increasing regulatory pressures and environmental concerns that are shaping the market. The segmentation analysis categorizes the market by product type, technology, end-user, and region, offering insights into market share and growth potential across different segments. Regional analysis focuses on major markets, including North America, Europe, and Asia-Pacific, detailing the unique dynamics and trends in each region. Additionally, the report explores the competitive environment, identifying major players and their strategies, as well as emerging companies that contribute to market diversity. It also addresses market concentration and characteristics, emphasizing the interplay between established firms and innovative newcomers. The report aims to equip stakeholders, including industry professionals, investors, and policymakers, with valuable insights and actionable recommendations to navigate the evolving landscape of the SF6 market. Overall, this report serves as a vital resource for understanding current trends, future opportunities, and the implications of regulatory developments in the sulfur hexafluoride sector.
Future Outlook:
- Increased regulatory scrutiny will drive innovations in SF6 management and alternative technologies.
- Growing investments in renewable energy infrastructure will boost the demand for SF6 in electrical applications.
- Advancements in monitoring systems will enhance lifecycle management practices and reduce emissions.
- Companies will prioritize R&D for eco-friendly alternatives to SF6, aligning with sustainability goals.
- The semiconductor industry’s expansion will further elevate the need for SF6 in manufacturing processes.
- Strategic partnerships among industry players will facilitate resource sharing and accelerate innovation.
- Emerging markets in Asia-Pacific will present significant growth opportunities for SF6 applications.
- Industry players will focus on enhancing operational efficiency through technological upgrades and process optimizations.
- Environmental concerns will lead to increased adoption of alternative insulating gases in high-voltage applications.
- Market dynamics will increasingly reflect a balance between performance requirements and environmental responsibility.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Demand in Electrical Applications
The expansion of renewable energy and high-voltage electrical infrastructure is increasing the need for SF6 as an insulating gas in circuit breakers and switchgear, supporting grid reliability and efficiency.
Rising Adoption in the Semiconductor Industry
SF6 is essential for plasma etching in semiconductor manufacturing, and the global surge in electronics production is driving higher consumption of SF6 in this sector.
Regulatory Support and Environmental Initiatives
While SF6 is a potent greenhouse gas, regulatory frameworks are encouraging improved lifecycle management and emission reduction technologies, supporting continued use where alternatives are not yet viable.
Technological Advancements in SF6 Applications
Innovations in SF6 handling, monitoring, and recycling are making its use more sustainable, reducing leakage and emissions, and enabling compliance with stricter environmental standards.
Expansion of Renewable Energy Infrastructure
The global shift toward renewable energy sources requires advanced electrical systems, where SF6's superior insulating properties are critical for safe and efficient operation of high-voltage equipment.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size of the Sulfur Hexafluoride Market?
What is the projected growth rate of the Sulfur Hexafluoride Market?
What are the primary applications of sulfur hexafluoride?
Which regions are leading in the Sulfur Hexafluoride Market?
What factors are contributing to the growth of the Sulfur Hexafluoride Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Utilities
- 1.2.2 Semiconductor Manufacturers
- 1.2.3 Research Laboratories
- 1.2.4 Other Industrial Sectors
- 1.3 By Technology
- 1.3.1 Traditional SF6 Technology
- 1.3.2 Advanced Monitoring Systems
- 1.3.3 Alternative Gas Mixtures
- 1.4 By Product Type
- 1.4.1 Electrical Applications
- 1.4.2 Semiconductor Manufacturing
- 1.4.3 Other Industrial Uses
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2032: USD 488.72 million → Forecast year: USD 311.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2032
- 3.3 Forecast Market Size
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Sulfur Hexafluoride Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Sulfur Hexafluoride Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Sulfur Hexafluoride Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Sulfur Hexafluoride Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Sulfur Hexafluoride Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Sulfur Hexafluoride Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Sulfur Hexafluoride Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Sulfur Hexafluoride Market Outlook
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2032: USD 488.72 million → Forecast year: USD 311.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2032
- 11.2 Market Forecast
- 11.2.1 Revenue Forecast
- 11.2.2 Volume Forecast
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Sulfur Hexafluoride Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2032
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast
- 12.3.4 Volume Forecast
- 12.3.5 Base-Year Market Share, 2032
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Utilities
- 12.3.7.2 Semiconductor Manufacturers
- 12.3.7.3 Research Laboratories
- 12.3.7.4 Other Industrial Sectors
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast
- 12.4.4 Volume Forecast
- 12.4.5 Base-Year Market Share, 2032
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Traditional SF6 Technology
- 12.4.7.2 Advanced Monitoring Systems
- 12.4.7.3 Alternative Gas Mixtures
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast
- 12.5.4 Volume Forecast
- 12.5.5 Base-Year Market Share, 2032
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Electrical Applications
- 12.5.7.2 Semiconductor Manufacturing
- 12.5.7.3 Other Industrial Uses
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Sulfur Hexafluoride End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Sulfur Hexafluoride Geographic Market Outlook
- 14.1 Regional Market Size and Share, 2032
- 14.2 Regional Market Forecast
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Sulfur Hexafluoride Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Sulfur Hexafluoride Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2032
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Solvay
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 SHOWA DENKO K.K.
- 18.4 Concorde Specialty Gases, Inc
- 18.5 The Linde Group
- 18.6 Advanced Specialty Gases
- 18.7 Matheson Tri-Gas, Inc
- 18.8 Air Products and Chemicals, Inc
- 18.9 Electronic Fluorocarbons, LLC
- 18.10 Praxair Technology, Inc
- 18.11 Bengal Gases
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
