
Market Overview
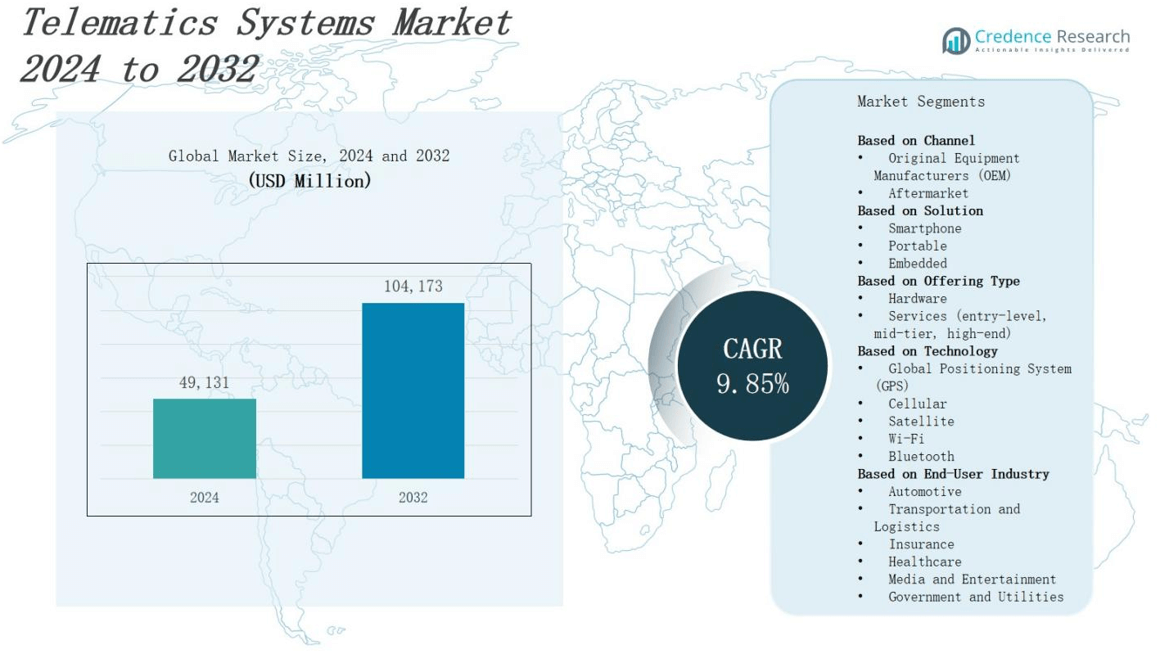
The telematics systems market is projected to grow from USD 49,131 million in 2024 to USD 104,173 million by 2032, registering a compound annual growth rate (CAGR) of 9.85%.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Telematics systems market Size 2024 | USD 49,131 million |
| Telematics systems market, CAGR | 9.85% |
| Telematics systems market Size 2032 | USD 104,173 million |
The telematics systems market grows steadily driven by increasing demand for vehicle tracking, fleet management, and insurance telematics solutions. Rising adoption of connected vehicles and the integration of IoT technologies enhance real-time data collection and analytics, improving operational efficiency and safety. Growing regulatory requirements for vehicle monitoring and emissions control further stimulate market growth. Additionally, advancements in AI and big data enable predictive maintenance and driver behavior analysis, creating new opportunities. The shift toward electric and autonomous vehicles also drives telematics innovation, while expanding applications in logistics, transportation, and insurance sectors sustain market momentum globally.
The telematics systems market spans key regions including North America, Europe, Asia-Pacific, and the Rest of the World, each contributing uniquely to market growth. North America leads with 35% market share, followed by Europe at 28%, Asia-Pacific at 22%, and the Rest of the World holding 15%. Leading players such as Geotab Inc., Fleet Complete, Octo Telematics, TomTom Telematics, Mix Telematics, Intel Corporation, Continental AG., Sierra Wireless, Verizon Connect, and Trimble Inc. drive innovation and regional expansion, leveraging advanced technologies and strategic partnerships to capitalize on diverse market opportunities globally.
Market Insights
- The telematics systems market is projected to grow from USD 49,131 million in 2024 to USD 104,173 million by 2032, with a CAGR of 9.85%.
- Increasing demand for vehicle tracking, fleet management, and insurance telematics drives steady market growth. Rising adoption of connected vehicles and IoT integration enhances real-time data collection, improving efficiency and safety.
- Regulatory requirements for vehicle monitoring and emissions control stimulate market expansion. AI and big data advancements enable predictive maintenance and driver behavior analysis, creating new opportunities.
- The rise of electric and autonomous vehicles drives telematics innovation, while logistics, transportation, and insurance sectors sustain global momentum.
- North America leads with 35% market share, followed by Europe at 28%, Asia-Pacific at 22%, and the Rest of the World at 15%. Key players include Geotab Inc., Fleet Complete, Octo Telematics, and Intel Corporation.
- Data privacy and cybersecurity concerns challenge market adoption, requiring strong encryption and secure protocols. High implementation costs and integration complexities limit growth, especially in developing regions.
- Market growth benefits from escalating demand for fleet management, IoT-enabled analytics, compliance with safety regulations, and expanding electric and autonomous vehicle segments driving specialized telematics solutions.
Market Drivers
Rising Demand for Fleet Management and Vehicle Tracking Solutions
The telematics systems market experiences strong growth due to escalating demand for efficient fleet management and vehicle tracking. Companies seek real-time monitoring to optimize routes, reduce fuel consumption, and improve asset utilization. It enables businesses to enhance driver safety and compliance with regulatory standards. The need for effective logistics management in transportation, delivery, and service industries further fuels adoption. Growing awareness of telematics benefits across small and large fleets drives widespread implementation globally.
- For instance, Verizon Connect enables real-time route optimization and fuel consumption monitoring, helping fleets reduce operational costs and improve efficiency.
Integration of IoT and Advanced Analytics
The integration of Internet of Things (IoT) technologies into telematics systems transforms data collection and analysis capabilities. It connects vehicles, infrastructure, and devices, providing comprehensive insights through real-time data streams. The telematics systems market benefits from this innovation by offering predictive maintenance, improved route planning, and driver behavior monitoring. AI-driven analytics convert vast datasets into actionable intelligence, enabling proactive decision-making. This technological evolution supports enhanced safety and operational efficiency. Industry players continuously invest in IoT-enabled telematics to differentiate their offerings and capture new opportunities.
Regulatory Compliance and Safety Enhancement Initiatives
Governments worldwide implement stringent regulations on vehicle emissions, driver hours, and safety standards, increasing the necessity for telematics adoption. The telematics systems market responds to these mandates by providing reliable tracking and reporting tools to ensure compliance. It supports accident reduction through monitoring driver behavior and encouraging safer driving practices. Organizations face penalties for non-compliance, making telematics a critical solution to mitigate risks. Insurance companies also leverage telematics data to incentivize safe driving and reduce claims. Compliance-driven demand creates a steady market expansion and fosters innovation in telematics features.
- For instance, the European Union mandates automakers to install telematics systems to track fuel efficiency and emission data, supporting adherence to CO2 reduction targets.
Growth of Electric and Autonomous Vehicles
The rise of electric and autonomous vehicles creates new avenues for telematics systems in vehicle monitoring and control. The telematics systems market adapts to support battery management, charging station integration, and autonomous navigation data needs. It plays a key role in vehicle-to-everything (V2X) communication, enhancing traffic management and road safety. Manufacturers and fleet operators rely on telematics to optimize electric vehicle performance and autonomous system efficiency. The expanding electric and self-driving vehicle segments drive the development of specialized telematics solutions tailored to emerging transportation technologies. This trend accelerates market diversification and growth prospects.
Market Trends
Expansion of Connected Vehicle Technologies Enhances Market Capabilities
The telematics systems market evolves with the rapid expansion of connected vehicle technologies that enable seamless communication between vehicles, infrastructure, and cloud platforms. It delivers real-time data exchange that improves traffic management, vehicle diagnostics, and safety features. Enhanced connectivity supports advanced driver assistance systems (ADAS) and paves the way for autonomous driving solutions. Automakers and technology providers invest heavily in vehicle-to-everything (V2X) communication protocols to improve system reliability and user experience. This trend broadens telematics applications beyond traditional fleet management to personal and commercial vehicles, fueling market growth.
- For instance, French startup Airnity provides a multi-cloud network platform that improves vehicle connectivity by optimizing cost and quality of service while meeting telecom and automotive compliance standards through a full-mobile virtual network operator model.
Adoption of Artificial Intelligence and Machine Learning for Advanced Insights
The market increasingly integrates artificial intelligence (AI) and machine learning (ML) to analyze telematics data more efficiently and accurately. It processes vast amounts of information to identify patterns, predict vehicle maintenance needs, and monitor driver behavior. These capabilities help reduce downtime and improve safety through early detection of potential issues. AI-driven analytics enable personalized services such as dynamic routing and insurance telematics. The telematics systems market benefits from continuous improvements in AI algorithms, driving smarter, more proactive fleet and vehicle management solutions.
- For instance, Motive uses AI-powered dashcams that detect driver distraction and fatigue in real time, enabling proactive safety interventions and reducing accidents.
Shift Toward Cloud-Based Telematics Platforms for Scalability
The telematics systems market adopts cloud-based platforms to enhance scalability, flexibility, and data accessibility for users. Cloud integration allows for centralized data storage, seamless software updates, and easier integration with third-party applications. It supports real-time monitoring and analytics from any location, improving decision-making for fleet managers and vehicle owners. The transition from on-premise solutions to cloud services reduces IT infrastructure costs and accelerates deployment. This trend encourages widespread adoption of telematics across diverse industries and supports rapid innovation in feature development.
Rising Demand for Usage-Based Insurance and Personalized Services
The increasing demand for usage-based insurance (UBI) models drives the telematics systems market to develop more accurate and customizable monitoring solutions. It enables insurers to assess risk based on real driving behavior, offering tailored premiums and incentives for safe driving. Consumers benefit from personalized feedback and coaching to improve driving habits. The telematics systems market capitalizes on this trend by collaborating with insurance companies and expanding offerings in telematics-based risk management. Growth in UBI adoption promotes wider use of telematics technology beyond fleet operations into individual vehicle owners.
Market Challenges Analysis
Data Privacy and Security Concerns Impede Market Adoption
The telematics systems market faces significant challenges related to data privacy and cybersecurity risks. It collects vast amounts of sensitive information, including location, driver behavior, and vehicle diagnostics, which raises concerns about unauthorized access and misuse. Companies must comply with stringent data protection regulations, increasing the complexity of system design and deployment. Cyberattacks targeting telematics platforms threaten operational integrity and customer trust. Addressing these vulnerabilities requires robust encryption, secure communication protocols, and continuous monitoring. Resistance from customers wary of surveillance further slows adoption. Overcoming privacy concerns remains critical for the market to expand sustainably.
High Implementation Costs and Integration Complexities Limit Growth
The telematics systems market encounters barriers due to the high costs associated with hardware installation, software licensing, and ongoing maintenance. It often demands significant upfront investment, which can deter small and medium-sized enterprises from adoption. Integration with existing fleet management or enterprise systems presents technical challenges, requiring customized solutions and skilled personnel. Compatibility issues across diverse vehicle types and brands add complexity to deployment. Furthermore, limited standardization in telematics protocols hampers seamless interoperability. These factors collectively restrict rapid market penetration, especially in developing regions where cost sensitivity remains high.
Market Opportunities
Growing Demand for Electric and Autonomous Vehicle Integration
The telematics systems market presents significant opportunities with the rapid adoption of electric and autonomous vehicles worldwide. It supports critical functions such as battery management, charging infrastructure coordination, and autonomous navigation data exchange. Manufacturers and fleet operators seek telematics solutions that optimize energy consumption and enhance vehicle safety. The expanding electric vehicle segment creates demand for specialized monitoring and diagnostic tools. Autonomous driving technologies rely heavily on telematics for real-time communication and control. Capitalizing on these trends enables market players to develop innovative products tailored to emerging transportation needs, driving revenue growth and technological advancement.
Expansion into Usage-Based Insurance and Personalized Mobility Services
The telematics systems market benefits from rising interest in usage-based insurance (UBI) and personalized mobility services, creating new revenue streams. It enables insurers to offer customized premium models based on accurate driver behavior data, reducing risk and encouraging safer driving. Telecommunication providers and mobility platforms integrate telematics to deliver tailored transportation solutions such as dynamic routing and car-sharing optimization. The growing urbanization and demand for smart city infrastructure further amplify opportunities for telematics in public transportation and logistics. Expanding collaborations across insurance, automotive, and technology sectors strengthen market penetration and promote innovative service offerings.
Market Segmentation Analysis:
By Channel
The telematics systems market divides into Original Equipment Manufacturers (OEM) and aftermarket channels, each contributing distinct growth dynamics. OEMs integrate telematics solutions directly into new vehicles, offering seamless connectivity and advanced features from the factory. It benefits from increasing automaker partnerships and rising demand for connected vehicles. The aftermarket segment caters to vehicle owners seeking retrofit solutions to upgrade older fleets or personal cars. Aftermarket growth gains momentum due to cost-effectiveness and flexibility. Both channels collectively expand telematics adoption across new and existing vehicle bases, enhancing overall market penetration.
- For instance, BMW integrates telematics directly into new vehicles, providing built-in connected services like remote diagnostics and advanced driver assistance, enhancing vehicle safety and user experience.
By Solution
The market segments telematics solutions into smartphone-based, portable, and embedded categories, providing varied deployment options. Smartphone telematics leverage mobile devices for affordable and accessible vehicle monitoring, appealing to individual users and small fleets. Portable devices offer plug-and-play functionality with ease of installation, serving fleets requiring quick setups. Embedded systems integrate directly into vehicle electronics, delivering advanced data accuracy and comprehensive features. It enables real-time diagnostics and continuous monitoring. These solution types address diverse user needs and use cases, driving widespread telematics system adoption.
- For instance, Verizon Connect’s smartphone telematics app enables fleet managers to monitor vehicle location and driver behavior affordably through mobile devices, appealing to small fleets and individual users.
By Offering Type
The telematics systems market categorizes offerings into hardware and services, including entry-level, mid-tier, and high-end service packages. Hardware includes devices such as GPS modules, sensors, and communication units critical for data collection and transmission. It supports service tiers that range from basic tracking to advanced analytics, predictive maintenance, and driver coaching. Service-based revenue grows with increasing demand for cloud platforms, software updates, and customer support. This segmentation allows providers to tailor solutions to varying customer budgets and technical requirements, fueling sustainable market expansion.
Segments:
Based on Channel
- Original Equipment Manufacturers (OEM)
- Aftermarket
Based on Solution
- Smartphone
- Portable
- Embedded
Based on Offering Type
- Hardware
- Services (entry-level, mid-tier, high-end)
Based on Technology
- Global Positioning System (GPS)
- Cellular
- Satellite
- Wi-Fi
- Bluetooth
Based on End-User Industry
- Automotive
- Transportation and Logistics
- Insurance
- Healthcare
- Media and Entertainment
- Government and Utilities
Based on Vehicle Type
- Passenger Cars
- Light Commercial Vehicles (LCVs)
- Heavy Commercial Vehicles (HCVs)
- Two-wheelers
- Off-highway Vehicles
Based on Application
- Fleet Management
- Vehicle Tracking
- Satellite Navigation
- Vehicle Safety Communication
- Insurance Telematics (Usage-Based Insurance)
- Infotainment
- Remote Diagnostics
- Others
Based on Deployment Model
- On-Premise
- Cloud-based
- Hybrid
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America commands the largest share of the telematics systems market, holding 35% of the global revenue. It benefits from advanced automotive infrastructure, widespread adoption of connected vehicles, and strong regulatory support for safety and emissions monitoring. The presence of major telematics solution providers and insurance companies investing in usage-based insurance models drives market growth. It also sees rapid integration of IoT and AI technologies in telematics platforms. High consumer awareness and well-established fleet management services contribute to sustained demand. Continuous innovation and government incentives for electric and autonomous vehicles further strengthen the region’s leadership.
Europe
Europe holds 28% of the telematics systems market share, driven by stringent government regulations on vehicle emissions and safety standards. It promotes telematics adoption through policies mandating real-time monitoring and compliance reporting for commercial fleets. The region benefits from a mature automotive industry focusing on connected and autonomous vehicle technologies. It leverages telematics for improving urban mobility and logistics efficiency across diverse countries. Investments in smart city projects and expanding electric vehicle infrastructure also support market expansion. Strong collaboration between automakers and technology providers accelerates product development and deployment.
Asia-Pacific
Asia-Pacific captures 22% of the telematics systems market and exhibits rapid growth fueled by increasing vehicle production and rising demand for fleet management solutions. It experiences growing adoption in countries such as China, India, Japan, and South Korea, supported by expanding logistics, e-commerce, and transportation sectors. Urbanization and infrastructure development drive the need for efficient traffic management and vehicle tracking. It faces challenges related to infrastructure and standardization but benefits from government initiatives promoting connected vehicle technologies. Market players focus on cost-effective solutions to cater to emerging economies, widening telematics accessibility.
Rest of the World
The Rest of the World accounts for 15% of the telematics systems market, with growing interest in Latin America, the Middle East, and Africa. It sees increasing investments in fleet optimization and vehicle safety across commercial transportation sectors. The region’s telematics adoption benefits from rising awareness of operational efficiency and regulatory encouragement. Infrastructure development and digital transformation efforts support gradual market penetration. Limited technological maturity and cost barriers slow growth, but strategic partnerships and government support aim to enhance market presence. Emerging demand for personalized mobility and insurance telematics also contribute to expansion opportunities.
Key Player Analysis
- Trimble Inc.
- Octo Telematics
- Verizon Connect
- Geotab Inc.
- Sierra Wireless
- Continental AG.
- Fleet Complete
- TomTom Telematics
- Intel Corporation
- Mix Telematics
Competitive Analysis
The telematics systems market features intense competition among key players striving to innovate and expand their global footprint. Leading companies such as Geotab Inc., Fleet Complete, Octo Telematics, TomTom Telematics, and Mix Telematics invest heavily in research and development to enhance product capabilities and differentiate their offerings. It also includes major technology and automotive firms like Intel Corporation, Continental AG., Sierra Wireless, Verizon Connect, and Trimble Inc., which leverage their broad industry expertise and extensive distribution networks. These players focus on strategic partnerships, acquisitions, and collaborations to strengthen market position and address evolving customer demands. The telematics systems market rewards companies that deliver integrated solutions combining hardware, software, and data analytics to improve fleet management, driver safety, and operational efficiency. Competitive pricing, scalability, and the ability to adapt to regional regulatory requirements remain critical success factors. Continuous innovation in AI, IoT integration, and cloud-based services further intensifies competition, prompting companies to accelerate product launches and expand service portfolios.
Recent Developments
- In May 2024, Ambarella unveiled next-generation AI System on Chips (SoCs), the CV75AX and CV72AX, designed for in-vehicle fleet telematics systems.
- In May 2024, Geotab partnered with Rivian to deliver an integrated data solution for Rivian's commercial vehicles in North America.
- In April 2024, Samsara partnered with United Natural Foods, Inc. (UNFI) to install its commercial vehicle telematics platform in UNFI trucks.
- On April 2, 2024, Powerfleet completed a merger with MiX Telematics, creating one of the largest mobile asset AIoT SaaS providers globally.
Market Concentration & Characteristics
The telematics systems market exhibits a moderately concentrated competitive landscape dominated by a mix of specialized telematics providers and major technology and automotive companies. Leading players such as Geotab Inc., Fleet Complete, Octo Telematics, TomTom Telematics, Intel Corporation, and Continental AG. hold significant market shares by offering comprehensive hardware, software, and analytics solutions. It favors companies that deliver integrated, scalable platforms combining real-time data monitoring, AI-driven insights, and cloud-based services. The market demands continuous innovation to address evolving regulatory requirements, data security challenges, and diverse customer needs across fleet management, insurance, and connected vehicle segments. Smaller players face challenges due to high entry barriers, including substantial R&D investment and complex system integration. The telematics systems market rewards agility, technological advancement, and strong strategic partnerships to expand regional presence and service offerings. Customer-centric approaches and compliance with data privacy standards remain critical to maintaining competitive advantage and driving sustainable growth.
Report Coverage
The research report offers an in-depth analysis based on Channel, Solution, Offering Type, Technology, End User Industry, Vehicle Type, Application, Deployment Model and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The telematics systems market will expand due to increasing adoption of connected and autonomous vehicles.
- Integration of AI and machine learning will enhance predictive maintenance and driver behavior analysis.
- Usage-based insurance models will drive demand for advanced telematics monitoring solutions.
- IoT-enabled telematics platforms will improve real-time data accuracy and operational efficiency.
- Growing regulatory requirements for emissions and safety will boost telematics implementation.
- Expansion of electric vehicle fleets will create new opportunities for specialized telematics services.
- Cloud-based telematics solutions will gain traction for their scalability and ease of integration.
- Data privacy and cybersecurity measures will become more critical to market growth.
- Increasing demand for fleet optimization in logistics and transportation sectors will sustain market momentum.
- Strategic collaborations and technology partnerships will accelerate innovation and regional market penetration.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Escalating Demand for Fleet Management and Vehicle Tracking
Businesses across logistics, transportation, and service industries are increasingly adopting telematics systems to optimize routes, reduce fuel consumption, and improve asset utilization, driving widespread market growth.
Integration of IoT and Advanced Analytics
The adoption of IoT technologies and AI-driven analytics in telematics enables real-time data collection, predictive maintenance, and driver behavior monitoring, enhancing operational efficiency and safety for fleets and individual vehicles.
Regulatory Compliance and Safety Requirements
Stringent government regulations on vehicle emissions, driver hours, and safety standards are compelling organizations to implement telematics solutions for compliance, risk mitigation, and improved reporting capabilities.
Growth of Electric and Autonomous Vehicles
The rise of electric and autonomous vehicles is creating new opportunities for telematics systems to support battery management, charging infrastructure, and autonomous navigation, expanding the market into emerging transportation technologies.
Expansion of Usage-Based Insurance Models
Insurance companies are leveraging telematics data to offer usage-based insurance, incentivizing safe driving and enabling personalized premiums, which is accelerating telematics adoption among both commercial fleets and individual vehicle owners.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for telematics systems market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the telematics systems market projected to grow between 2025 and 2032?
Which telematics systems market segment held the largest share in 2024?
What are the primary factors fueling the growth of the telematics systems market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Channel
- 1.2.1 Original Equipment Manufacturers (OEM)
- 1.2.2 Aftermarket
- 1.3 By Solution
- 1.3.1 Smartphone
- 1.3.2 Portable
- 1.3.3 Embedded
- 1.4 By Application
- 1.4.1 Fleet Management
- 1.4.2 Vehicle Tracking
- 1.4.3 Insurance Telematics (Usage-Based Insurance)
- 1.4.4 Remote Diagnostics
- 1.4.5 Infotainment
- 1.5 By Offering Type
- 1.5.1 Hardware
- 1.5.2 Services (entry-level, mid-tier, high-end)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 49,131 million → 2032: USD 104,173 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Telematics Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Telematics Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Telematics Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Telematics Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Telematics Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Telematics Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Telematics Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Telematics Systems Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 49,131 million → 2032: USD 104,173 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Telematics Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Channel - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Original Equipment Manufacturers (OEM)
- 12.3.7.2 Aftermarket
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Solution - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Smartphone
- 12.4.7.2 Portable
- 12.4.7.3 Embedded
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Fleet Management
- 12.5.7.2 Vehicle Tracking
- 12.5.7.3 Insurance Telematics (Usage-Based Insurance)
- 12.5.7.4 Remote Diagnostics
- 12.5.7.5 Infotainment
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Offering Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Hardware
- 12.6.7.2 Services (entry-level, mid-tier, high-end)
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Telematics Systems End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Telematics Systems Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Telematics Systems Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Telematics Systems Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Geotab Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Fleet Complete
- 18.4 Octo Telematics
- 18.5 TomTom Telematics
- 18.6 Mix Telematics
- 18.7 Intel Corporation
- 18.8 Continental AG
- 18.9 Sierra Wireless
- 18.10 Verizon Connect
- 18.11 Trimble Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

