
Market Overview
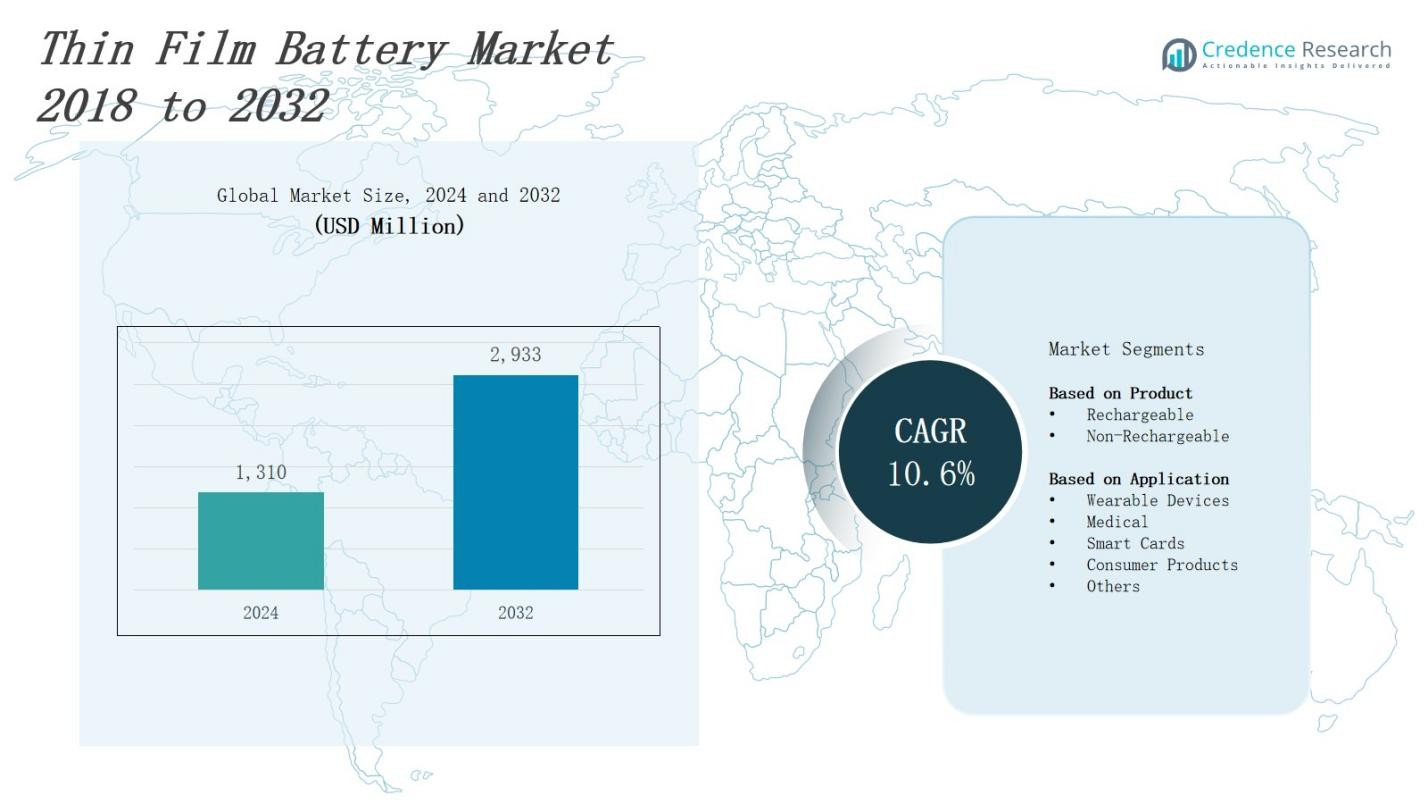
The Thin Film Battery Market is projected to grow from USD 1,310 million in 2024 to USD 2,933 million by 2032, expanding at a CAGR of 10.6%.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Thin Film Battery Market Size 2024 | USD 1,310 Million |
| Thin Film Battery Market, CAGR | 10.6% |
| Thin Film Battery Market Size 2032 | USD 2,933 Million |
The thin film battery market grows driven by rising demand for compact, lightweight, and flexible energy storage solutions across wearable devices, medical implants, and IoT applications. Advancements in thin film technology enhance battery performance, safety, and longevity, attracting adoption in consumer electronics and automotive sectors. Increasing focus on miniaturization and portability accelerates integration into next-generation devices. Additionally, growing environmental concerns push manufacturers to develop sustainable, solid-state thin film batteries with reduced toxic materials. Continuous innovation and collaborations among key players further stimulate market expansion, positioning thin film batteries as critical components in emerging high-tech and smart applications worldwide.
The thin film battery market spans North America, Europe, Asia-Pacific, and the Rest of the World, with North America leading at 35% market share due to advanced technology adoption and strong healthcare sectors. Europe holds 28%, driven by environmental regulations and sustainable initiatives. Asia-Pacific accounts for 27%, fueled by rapid urbanization and electronics manufacturing growth. The Rest of the World represents 10%, reflecting emerging demand in Latin America, the Middle East, and Africa. Key players include STMicroelectronics, BrightVolt, Johnson Energy Storage, ITEN, and Molex, focusing on innovation and regional expansion.
Market Insights
- The thin film battery market is projected to grow from USD 1,310 million in 2024 to USD 2,933 million by 2032, expanding at a CAGR of 10.6%.
- Rising demand for compact, lightweight, and flexible energy storage solutions in wearable devices, medical implants, and IoT applications drives market growth.
- Advancements in thin film technology improve battery performance, safety, and longevity, encouraging adoption in consumer electronics and automotive sectors.
- Miniaturization and portability trends accelerate integration into next-generation devices, expanding application scope.
- Environmental concerns push manufacturers to develop sustainable, solid-state thin film batteries with reduced toxic materials
- The market spans North America (35%), Europe (28%), Asia-Pacific (27%), and Rest of the World (10%), with each region showing unique growth drivers.
- Key players include STMicroelectronics, BrightVolt, Johnson Energy Storage, ITEN, and Molex, focusing on innovation and regional expansion.
Market Drivers
Growing Demand for Compact and Flexible Energy Storage Solutions
The thin film battery market benefits from increasing demand for compact, lightweight, and flexible energy storage devices. It meets the needs of wearable electronics, medical implants, and IoT applications that require small form factors without compromising power. The ability to integrate thin film batteries into flexible substrates drives adoption across consumer electronics and healthcare sectors. Manufacturers focus on optimizing energy density and charge cycles to enhance product performance, expanding its applicability in miniaturized devices worldwide.
- For instance, AGC Plasma Technology has developed roll-to-roll industrial coating processes for thin-film batteries, enabling mass production of silicon anodes that significantly boost energy density and durability, with pilot lines already producing bifacial silicon anodes for scalable manufacturing.
Advancements in Thin Film Battery Technology
Ongoing innovation improves the safety, efficiency, and longevity of thin film batteries. It offers enhanced thermal stability and reduced risk of leakage compared to conventional batteries. These technological developments encourage adoption in automotive electronics and smart devices where reliability is crucial. Key players invest heavily in research to develop solid-state thin film batteries with higher capacity and faster charging capabilities, which fuels market growth and positions it as a preferred energy storage option.
- For instance, Ilika Technologies has commercialized its solid-state thin film batteries for IoT devices and medical wearables, highlighting their long cycle life and stable performance in compact formats.
Increased Miniaturization and Portability in Electronics
The trend toward miniaturization in consumer and industrial electronics drives thin film battery demand. It supports the design of smaller, lighter devices without sacrificing battery life. Portable gadgets, smart sensors, and flexible displays incorporate thin film batteries to meet space and weight restrictions. This push for reduced device size encourages manufacturers to adopt innovative thin film solutions, fueling its integration across diverse sectors including healthcare, automotive, and wearable technology.
Focus on Sustainability and Environmental Compliance
Environmental regulations and consumer preference for eco-friendly products boost the thin film battery market. It reduces reliance on toxic materials commonly found in traditional batteries, promoting safer disposal and recycling. Companies develop solid-state thin film batteries with longer lifespans, minimizing waste and resource consumption. Sustainable manufacturing processes and regulatory compliance encourage widespread adoption, positioning it as a green alternative in the energy storage industry.
Market Trends
Rise of Solid-State Thin Film Batteries Driving Market Evolution
The thin film battery market experiences a significant shift toward solid-state technology, which offers enhanced safety and higher energy density than traditional lithium-ion batteries. It eliminates the risk of leakage and improves thermal stability, making it suitable for critical applications in medical devices and wearables. Manufacturers invest in developing solid electrolytes and scalable production methods. This trend accelerates adoption in sectors demanding reliable, compact power sources with long cycle life.
- For instance, BrightVolt specializes in solid-state thin and flexible lithium polymer batteries, having sold approx. 15 million primary solid-state batteries globally. Its patented Polymer Matrix Electrolyte (PME®) technology offers up to 25% more energy density than typical lithium-ion batteries, emphasizing safety and ecological benefits.
Integration with Flexible and Wearable Electronics Fuels Demand
Increasing incorporation of thin film batteries into flexible and wearable electronics drives market growth. It supports devices that require bendable, lightweight power sources without sacrificing performance. The market aligns with consumer preferences for compact gadgets such as smartwatches, fitness trackers, and health monitors. Collaboration between battery producers and electronics manufacturers enhances customization and miniaturization. This trend strengthens thin film batteries’ position in the expanding wearable technology landscape.
- For instance, Fraunhofer IFAM reports that thin-film batteries' solid-state design ensures high safety and adaptability, enabling integration into smartwatches, fitness trackers, and medical monitoring devices with enhanced customization and miniaturization.
Expansion in Internet of Things (IoT) Applications Broadens Market Scope
The thin film battery market benefits from the rapid growth of IoT devices requiring small, efficient, and long-lasting power solutions. It enables sensors, smart tags, and connected devices to operate autonomously for extended periods. Energy harvesting and low power consumption technologies complement thin film batteries to improve device longevity. This trend widens the market by driving demand in smart homes, industrial automation, and asset tracking industries that depend on reliable energy storage.
Emphasis on Sustainable and Environmentally Friendly Battery Solutions
Environmental awareness influences the thin film battery market toward eco-friendly materials and production processes. It reduces use of hazardous substances and supports recyclable, solid-state designs. Companies focus on developing batteries with longer service lives to decrease electronic waste. Regulatory frameworks encouraging green energy storage products stimulate innovation. This trend positions the thin film battery market to meet both consumer and governmental demands for sustainable energy technologies.
Market Challenges Analysis
High Production Costs and Complex Manufacturing Processes Limit Market Expansion
The thin film battery market faces challenges from expensive raw materials and intricate fabrication techniques. It requires advanced deposition methods and precise control over thin layers, which increase manufacturing costs and limit large-scale production. These factors hinder affordability and slow adoption in price-sensitive applications. Manufacturers invest heavily to improve yield and reduce expenses, but technological complexity remains a significant barrier. Cost competitiveness against conventional battery technologies continues to restrict market penetration in certain segments.
Performance Limitations and Integration Issues Affect Broader Adoption
Thin film batteries encounter constraints related to energy capacity and power output compared to larger conventional batteries. It struggles to meet demands of high-power devices, limiting its use to niche applications like wearables and low-energy IoT devices. Integration with existing electronic components also poses design challenges due to form factor and compatibility concerns. The market must overcome these technical limitations through continuous innovation to expand into broader industrial and automotive sectors. Meeting reliability and safety standards remains critical for wider acceptance.
Market Opportunities
Expanding Applications in Wearable and Medical Devices Present Significant Growth Potential
The thin film battery market holds substantial opportunities in the wearable technology and medical device sectors. It provides compact, lightweight, and reliable power solutions essential for smartwatches, fitness trackers, and implantable medical devices. Growing demand for continuous health monitoring and personalized healthcare supports integration of thin film batteries into innovative designs. Companies can capitalize on this trend by developing customized battery solutions that enhance device performance and user comfort. Increasing consumer awareness and adoption of health-focused electronics further propel market expansion in these areas.
Adoption in Internet of Things (IoT) and Flexible Electronics Drives Market Diversification
Rapid growth in IoT deployments and flexible electronics creates new avenues for the thin film battery market. It supports autonomous, low-power devices such as sensors, smart labels, and flexible displays, enabling longer operational life and miniaturization. The trend toward smart cities, industrial automation, and connected devices increases demand for reliable energy storage with small footprints. Manufacturers can leverage advancements in solid-state and printable battery technologies to address diverse application needs. This expanding ecosystem offers significant scope for product innovation and strategic partnerships within the thin film battery market.
Market Segmentation Analysis:
By Product Type
The thin film battery market segments into rechargeable and non-rechargeable products. Rechargeable batteries dominate due to their ability to support multiple charge cycles, making them suitable for applications requiring long-term use and reliability. It offers cost efficiency and sustainability benefits in wearable devices and medical implants. Non-rechargeable thin film batteries find usage in low-power, single-use applications like smart cards and some consumer products, where replacement frequency is low. Both segments drive market growth through tailored energy solutions for diverse needs.
- For instance, Molex and LG Chem produce rechargeable thin film batteries specifically designed for smartwatches and wearable health monitors, offering lightweight, flexible power solutions that enable continuous monitoring and enhanced battery life.
By Application
The thin film battery market serves a broad range of applications, including wearable devices, medical equipment, smart cards, consumer products, and other emerging uses. It supports wearable devices with lightweight, flexible power sources that enhance portability and user experience. Medical applications rely on its biocompatibility and reliability for implantable devices and health monitors. Smart cards benefit from thin film batteries through secure and compact power integration. Consumer products utilize it for compact electronics requiring efficient energy storage. The ‘Others’ category includes IoT sensors and flexible electronics, expanding market scope.
- For instance, Grepow manufactures ultra-thin rechargeable lithium-ion thin film batteries as slim as 0.5 millimeters, tailored for wearable technology such as fitness trackers and augmented reality glasses, providing seamless integration and lightweight power.
Segments:
Based on Product
- Rechargeable
- Non-Rechargeable
Based on Application
- Wearable Devices
- Medical
- Smart Cards
- Consumer Products
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds the largest share in the thin film battery market, accounting for 35%. It benefits from advanced technological infrastructure and strong presence of key electronics and healthcare companies driving demand for innovative energy storage solutions. The region leads in adopting wearable devices and medical implants, which heavily rely on thin film batteries for their compact and flexible design. Robust R&D activities and favorable regulatory policies encourage continuous innovation. North America’s emphasis on smart healthcare and IoT applications further strengthens market growth. It remains a critical hub for developing next-generation thin film battery technologies.
Europe
Europe commands 28% of the thin film battery market share, supported by stringent environmental regulations and increasing demand for sustainable energy storage solutions. It emphasizes reducing hazardous materials and promoting recyclable, solid-state battery technologies. Growing investments in medical technology and wearable electronics accelerate market adoption across the region. Europe’s well-established consumer electronics sector also drives demand. Government incentives for green technology development support market expansion. It continues to focus on integrating thin film batteries in smart devices and industrial IoT applications to enhance efficiency.
Asia-Pacific
Asia-Pacific accounts for 27% of the thin film battery market and exhibits rapid growth due to increasing urbanization, rising disposable incomes, and expanding electronics manufacturing hubs. It serves as a major production base for consumer electronics, wearables, and smart devices incorporating thin film batteries. Growing healthcare awareness and adoption of implantable medical devices fuel demand. The region benefits from supportive government policies and investments in advanced manufacturing technologies. It attracts key players focusing on capacity expansion and product innovation, contributing significantly to market development.
Rest of the World
The Rest of the World holds 10% of the thin film battery market share, driven by emerging markets in Latin America, the Middle East, and Africa. These regions gradually adopt wearable technologies and IoT devices, increasing the need for compact energy storage solutions. Market growth depends on expanding infrastructure, rising consumer awareness, and increasing healthcare investments. Manufacturers target these regions with cost-effective, scalable battery solutions. The market here offers long-term growth potential despite current lower penetration compared to established regions.
Key Player Analysis
- Johnson Energy Storage
- ITEN
- Prieto Battery
- Imprint Energy
- Molex
- STMicroelectronics
- Ilika
- Ion Storage Systems
- Enfucell
- Cymbet
- Jenax
- BrightVolt
Competitive Analysis
The thin film battery market features intense competition among key players focusing on innovation, capacity expansion, and strategic partnerships. Companies invest heavily in research to improve energy density, battery life, and safety, aiming to differentiate their products. It witnesses ongoing collaborations between battery manufacturers and electronics firms to develop customized solutions for wearable devices, medical implants, and IoT applications. Market leaders emphasize scaling production capabilities to meet rising demand while reducing costs. It experiences competition based on technology advancements, product quality, and geographic reach. Firms such as STMicroelectronics, BrightVolt, and Johnson Energy Storage lead through strong R&D and diverse product portfolios. The market’s dynamic nature drives continuous development and aggressive strategies to capture emerging opportunities and strengthen market position globally.
Recent Developments
- In 2024, ProLogium launched a new line of flexible, ultra-thin batteries with enhanced energy density targeting consumer electronics and medical devices.
- In 2023, Ilika plc announced the commercialization of solid-state thin film batteries designed for wearable devices and IoT applications, emphasizing safety and miniaturization.
- In February 2025, Elevated Materials, a spinout from Applied Materials, introduced ultra-thin, uniform lithium films designed to improve battery energy density and cycle life.
- In July 2025, Lyten acquired Northvolt’s battery manufacturing facility in San Leandro, California, to scale production of lithium-sulfur batteries for electric vehicles and aerospace sectors.
Market Concentration & Characteristics
The thin film battery market exhibits a moderately concentrated structure with a handful of key players dominating product innovation and manufacturing capacity. It features companies that invest heavily in research and development to improve energy density, safety, and battery longevity. The market emphasizes collaboration between battery manufacturers and electronics firms to create customized solutions for wearable devices, medical implants, and IoT applications. It faces high entry barriers due to complex manufacturing processes and significant capital requirements, which limit new entrants. Established firms leverage advanced technologies and economies of scale to maintain competitive advantages. The market’s characteristics include rapid technological evolution, stringent quality standards, and increasing focus on sustainability. It experiences continuous innovation to address performance limitations and integration challenges, positioning it for steady growth within niche high-tech applications.
Report Coverage
The research report offers an in-depth analysis based on Product, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The thin film battery market will expand due to growing demand in wearable and medical devices.
- Innovation in solid-state technology will enhance battery safety and performance.
- Manufacturers will focus on reducing production costs to increase market accessibility.
- Integration with flexible electronics will drive new application development.
- Environmental regulations will encourage development of sustainable battery materials.
- Increased adoption of IoT devices will boost demand for compact energy solutions.
- Strategic partnerships between battery makers and device manufacturers will accelerate growth.
- Advances in energy density will enable use in broader industrial and automotive sectors.
- Market players will invest in scalable manufacturing to meet rising global demand.
- Continuous R&D efforts will address existing limitations and improve battery lifespan.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Compact and Flexible Energy Storage
The proliferation of wearable devices, medical implants, and IoT applications requires batteries that are lightweight, thin, and flexible, driving adoption of thin film batteries that can be integrated into small and irregularly shaped devices.
Advancements in Thin Film and Solid-State Technology
Continuous innovation in thin film and solid-state battery technologies has improved energy density, safety, and longevity, making these batteries more attractive for high-performance and safety-critical applications in consumer electronics and automotive sectors.
Miniaturization and Portability Trends
The ongoing trend toward smaller, lighter, and more portable electronic devices accelerates the integration of thin film batteries, which enable manufacturers to design next-generation products without compromising on power or form factor.
Environmental and Regulatory Pressures
Increasing environmental concerns and stricter regulations are pushing manufacturers to develop sustainable, solid-state thin film batteries with reduced toxic materials, supporting market growth as companies and consumers seek greener energy storage solutions.
Expansion of IoT and Smart Applications
The rapid growth of IoT devices and smart applications, which require long-lasting, reliable, and compact power sources, is broadening the scope of thin film battery adoption across industries such as smart homes, industrial automation, and asset tracking.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Thin film battery market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Thin film battery market projected to grow between 2025 and 2032?
Which Thin film battery market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Thin film battery market?
Who are the leading companies in the Thin film battery market?
Which region commanded the largest share of the Thin film battery market market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Rechargeable
- 1.2.2 Non-Rechargeable
- 1.3 By Application
- 1.3.1 Wearable Devices
- 1.3.2 Medical
- 1.3.3 Smart Cards
- 1.3.4 Consumer Products
- 1.3.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,310 million → 2032: USD 2,933 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Thin Film Battery Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Thin Film Battery Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Thin Film Battery Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Thin Film Battery Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Thin Film Battery Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Thin Film Battery Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Thin Film Battery Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Thin Film Battery Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,310 million → 2032: USD 2,933 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Thin Film Battery Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Rechargeable
- 12.3.7.2 Non-Rechargeable
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Wearable Devices
- 12.4.7.2 Medical
- 12.4.7.3 Smart Cards
- 12.4.7.4 Consumer Products
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Thin Film Battery End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Thin Film Battery Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Thin Film Battery Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Thin Film Battery Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 STMicroelectronics
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 BrightVolt
- 18.4 Johnson Energy Storage
- 18.5 ITEN
- 18.6 Molex
- 18.7 Ilika
- 18.8 Prieto Battery
- 18.9 Imprint Energy
- 18.10 Cymbet
- 18.11 Enfucell
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

