
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Tire Derived Fuel Market Size 2024 | USD 327.36 million |
| Tire Derived Fuel Market, CAGR | 3.23% |
| Tire Derived Fuel Market Size 2032 | USD 408.12 million |
Market Overview
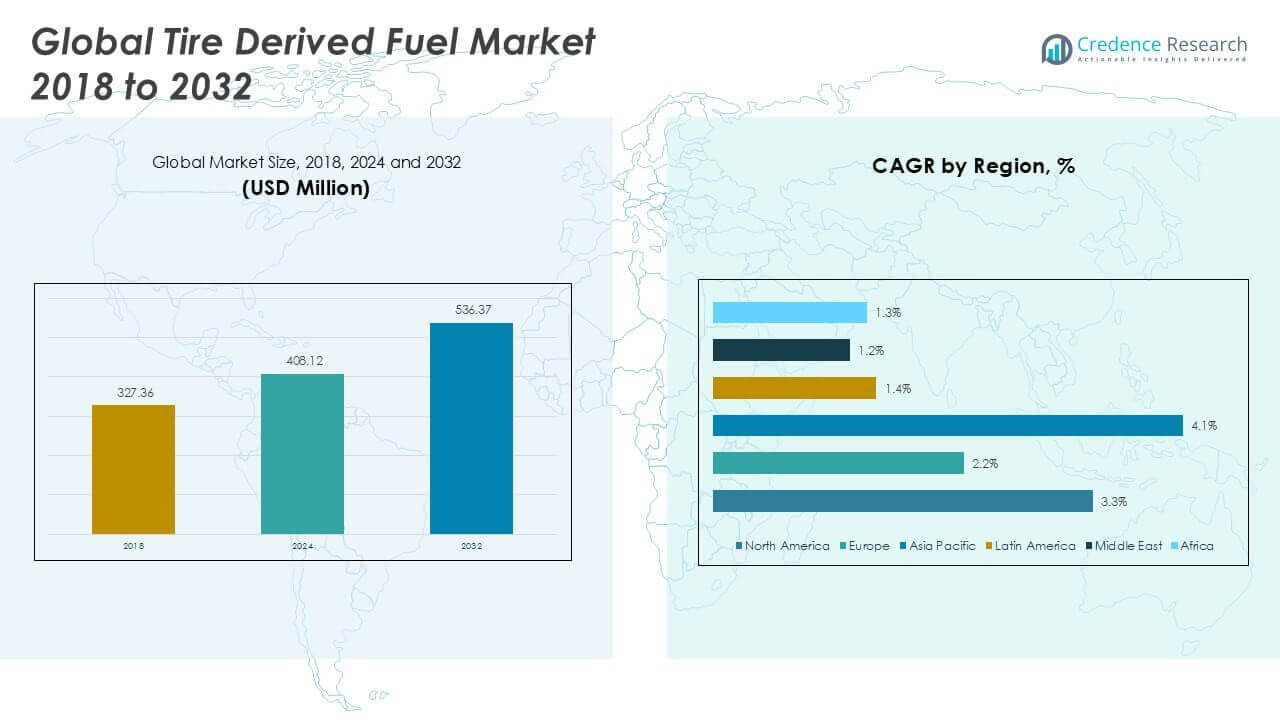
The Tire Derived Fuel Market size was valued at USD 327.36 million in 2018 to USD 408.12 million in 2024 and is anticipated to reach USD 536.37 million by 2032, at a CAGR of 3.23% during the forecast period.
The Tire Derived Fuel Market is driven by increasing environmental regulations that promote sustainable waste management and alternative fuel sources, encouraging industries to adopt tire-derived fuel as a cost-effective solution for energy generation. Rising concerns over landfill space and growing awareness about the environmental impact of discarded tires further support market expansion. The market benefits from advancements in processing technologies that enhance the efficiency and safety of tire-derived fuel, making it a viable substitute for conventional fossil fuels in cement kilns, power plants, and industrial boilers. Key trends shaping the market include the integration of circular economy practices, increased partnerships between tire recyclers and end-user industries, and ongoing investments in research to improve fuel quality and emissions performance. As industries seek sustainable energy alternatives, the demand for tire-derived fuel is expected to rise steadily, supported by regulatory incentives and evolving waste-to-energy initiatives worldwide.
The Tire Derived Fuel Market demonstrates robust growth across key regions, including North America, Europe, and Asia Pacific. North America benefits from advanced recycling infrastructure and supportive regulations, while Europe drives adoption through strict environmental standards and strong emphasis on circular economy principles. Asia Pacific leads in volume and growth rate, propelled by rapid industrialization, expanding manufacturing sectors, and government-backed waste management initiatives, with China, India, and Japan as major contributors. Prominent players in the Tire Derived Fuel Market include Liberty Tire Recycling, which offers comprehensive tire collection and processing solutions across North America, and Scandinavian Enviro Systems AB, a pioneer in tire recycling technologies in Europe. Genan Holding A/S also stands out for its large-scale tire recycling operations and innovative material recovery methods. These companies play a critical role in advancing sustainable practices, ensuring reliable supply, and fostering technological innovation in the global tire derived fuel industry.
Market Insights
- The Tire Derived Fuel Market was valued at USD 408.12 million in 2024 and is projected to reach USD 536.37 million by 2032, growing at a CAGR of 3.23% during the forecast period.
- The market is driven by stringent environmental regulations promoting sustainable waste management and increasing adoption of alternative fuels in energy-intensive industries.
- A significant trend includes the rising use of tire derived fuel in cement kilns and power plants, supported by advancements in processing and emissions control technologies.
- Leading companies such as Liberty Tire Recycling, Scandinavian Enviro Systems AB, and Genan Holding A/S are investing in innovative recycling methods and expanding their operational capacities.
- Market restraints include complex regulatory frameworks, public concerns about environmental and health impacts, and supply chain challenges affecting the consistent quality and availability of tire derived fuel.
- Asia Pacific leads in both market size and growth rate due to rapid industrialization and strong governmental support for waste-to-energy initiatives, while North America and Europe follow with steady demand driven by established infrastructure and strict policies.
- The competitive landscape is marked by collaborations, technological advancements, and regional expansions as key players seek to enhance efficiency, meet compliance standards, and capture emerging opportunities in global markets.
Market Drivers
Stringent Environmental Regulations Encourage Adoption of Alternative Fuels
Governments across the globe continue to enforce strict environmental regulations on waste management and emissions reduction, prompting industries to seek sustainable fuel alternatives. These policies discourage tire stockpiling and landfill disposal, incentivizing companies to adopt tire derived fuel (TDF) as an eco-friendly solution. The Tire Derived Fuel Market benefits from regulatory frameworks that support recycling and alternative energy initiatives, fostering widespread acceptance. Compliance requirements for cleaner production processes drive manufacturers, especially in the cement and energy sectors, to incorporate TDF into their fuel mix. Regulatory support includes tax benefits, subsidies, and mandatory recycling targets, all of which accelerate market growth. The focus on achieving national and international climate goals reinforces TDF adoption as part of broader environmental strategies.
- For instance, stringent environmental policies in the European Union and North America have accelerated the adoption of tire-derived fuel (TDF) as an alternative energy source.
Cost Efficiency and Fuel Performance Attract Industrial Users
Industries favor tire derived fuel for its cost-effectiveness and energy-rich composition compared to traditional fossil fuels. TDF offers a competitive calorific value, making it an attractive alternative for energy-intensive sectors such as cement manufacturing, paper mills, and industrial boilers. The affordability of TDF stems from abundant waste tire supplies and efficient collection networks. Reduced fuel costs help companies maintain profitability while adhering to sustainability goals. Many industrial users also value the consistent fuel performance and lower price volatility compared to conventional fuels. It allows organizations to optimize operational expenses without compromising energy output or environmental compliance.
- For instance, TDF provides a high calorific value comparable to coal, making it a preferred choice for cement kilns and industrial boilers.
Technological Advancements Improve Processing and Emissions Control
Continuous advancements in processing technology and emissions control systems support the efficient conversion of scrap tires into high-quality fuel. Innovations in shredding, de-wiring, and combustion technologies enable safer handling, better fuel uniformity, and reduced pollutants. These technological improvements help facilities meet stringent emission standards while maximizing energy recovery. Automated systems and digital monitoring further optimize the entire fuel supply chain, from collection to end-use. It enables plants to achieve higher combustion efficiency and minimize environmental impact, reinforcing industry confidence in TDF as a reliable energy source. Investment in R&D also promotes the development of cleaner and more sustainable TDF solutions.
Circular Economy and Sustainability Initiatives Drive Market Growth
The growing focus on circular economy principles and resource efficiency enhances the appeal of tire derived fuel among policymakers and businesses. By converting end-of-life tires into energy, TDF helps close the material loop and reduce dependence on virgin fossil resources. Industries participating in circular economy initiatives gain reputational benefits and often receive support from environmentally conscious investors and stakeholders. It enables organizations to align with global sustainability frameworks while addressing waste management challenges. Partnerships between tire recyclers, industrial fuel users, and government agencies further strengthen the supply chain. These collaborations create a robust ecosystem that supports long-term market expansion and promotes innovation in sustainable energy use.
Market Trends
Strategic Collaborations and Partnerships Across the Value Chain
Strategic partnerships between tire recyclers, energy producers, and government agencies are shaping the growth trajectory of the TDF market. Collaborative initiatives focus on securing consistent supply chains, improving collection infrastructure, and fostering innovation in TDF applications. Joint ventures and long-term contracts ensure reliable sourcing and help manage price volatility. It supports the creation of integrated business models that maximize resource utilization and minimize environmental impact. Stakeholders leverage these partnerships to expand their geographical reach and enhance market share, reflecting a move toward a more resilient and sustainable industry ecosystem.
- For instance, joint ventures between tire recyclers and cement manufacturers have strengthened supply chains and improved market accessibility.
Increasing Integration of Tire Derived Fuel in Cement and Power Industries
Cement manufacturing and power generation industries are integrating tire derived fuel (TDF) to diversify their energy sources and achieve sustainability targets. These sectors recognize the high calorific value of TDF, which enables efficient fuel substitution without major modifications to existing combustion systems. The trend aligns with the need for reducing carbon emissions and lowering fuel costs. Regulatory pressures and industry standards motivate manufacturers to adopt alternative fuels, driving steady growth in TDF usage. The Tire Derived Fuel Market reflects this shift, with cement kilns and power plants accounting for a significant share of overall demand. It allows energy-intensive industries to enhance operational efficiency while supporting environmental stewardship.
Advancements in TDF Processing and Quality Control Technologies
The market is experiencing a surge in technological advancements that improve the quality, safety, and usability of tire derived fuel. Innovations in shredding, wire removal, and emissions abatement ensure TDF meets rigorous performance and environmental standards. Automated processing systems streamline production and enhance the uniformity of the final product, encouraging broader adoption across end-user segments. Digital monitoring solutions facilitate real-time tracking of fuel composition and emissions, supporting compliance with evolving regulations. It enables manufacturers to offer premium-grade TDF that meets the specific requirements of different industrial processes. This trend elevates the reputation and competitiveness of the market on a global scale.
- For instance, digital monitoring and automated systems have optimized fuel processing, reducing emissions and improving combustion efficiency.
Growing Emphasis on Circular Economy and Sustainable Energy Solutions
The adoption of tire derived fuel is increasingly viewed through the lens of circular economy and sustainability. Industries and governments are prioritizing waste-to-energy solutions that transform end-of-life tires into valuable fuel, supporting global efforts to reduce landfill waste and carbon footprints. Market participants invest in new technologies and infrastructure to optimize energy recovery and minimize environmental harm. Public awareness campaigns and regulatory incentives drive greater acceptance of TDF as a mainstream fuel alternative. It reinforces the market’s position as a vital component of the sustainable energy transition, promoting long-term growth and innovation across the sector.
Market Challenges Analysis
Regulatory Hurdles and Public Perception Restrain Market Expansion
The Tire Derived Fuel Market faces significant challenges due to complex regulatory environments and lingering concerns about environmental and health impacts. Different regions enforce varying standards on emissions, permitting, and waste-to-energy operations, creating uncertainty for market participants. Strict regulations can limit the approval and expansion of TDF projects, especially in areas with heightened environmental scrutiny. Public perception also poses obstacles, with communities sometimes opposing TDF facilities due to fears of air pollution and toxic emissions. It requires ongoing efforts to educate stakeholders about technological advancements and environmental safeguards that reduce negative impacts. Market growth depends on clear regulatory guidelines and transparent communication to build trust and foster acceptance.
Supply Chain Complexity and Quality Control Issues Impact Market Growth
Complexities in the collection, transportation, and processing of waste tires create persistent supply chain challenges for the Tire Derived Fuel Market. Inconsistent supply quality and logistical inefficiencies can disrupt the production of reliable, high-grade TDF for industrial users. It becomes critical for market participants to establish robust collection networks and invest in quality control technologies to ensure a steady and uniform supply. Competition with other recycling and energy recovery options also impacts tire availability for TDF production. Managing these supply chain variables while maintaining cost efficiency requires strategic partnerships and operational flexibility. Sustained market expansion hinges on overcoming these logistical hurdles and consistently delivering high-quality fuel to end users.
- For instance, competition with other recycling and energy recovery options has influenced tire availability for TDF production, requiring strategic partnerships to maintain supply chain stability.
Market Opportunities
Expansion into Emerging Economies Presents Significant Growth Potential
Rapid industrialization and urban development in emerging economies create substantial opportunities for the Tire Derived Fuel Market. Many countries in Asia Pacific, Latin America, and Africa seek sustainable waste management solutions and alternative energy sources to support infrastructure growth. The market stands to benefit from supportive government policies that encourage recycling and clean energy adoption. Investment in new processing facilities and collection networks can help address the growing volume of scrap tires in these regions. It allows local industries to reduce reliance on conventional fossil fuels while improving waste diversion rates. Early market entrants can gain a competitive edge by establishing strong supply chains and forming partnerships with local stakeholders.
Technological Innovation and Circular Economy Initiatives Drive New Applications
Advancements in tire processing, emissions control, and digital monitoring technologies open new avenues for the Tire Derived Fuel Market. These innovations enable the production of cleaner, more efficient fuels that meet strict regulatory and performance standards. Embracing circular economy principles, industries and governments increasingly prioritize the conversion of end-of-life tires into valuable energy resources. It fosters the development of integrated business models and diversified product offerings, including tailored TDF solutions for specific industrial processes. Market participants can capitalize on growing demand for sustainable energy by investing in R&D and expanding their service portfolios. This dynamic landscape encourages continuous improvement and supports long-term market expansion.
Market Segmentation Analysis:
By Type:
The Tire Derived Fuel (TDF) market is segmented by type into whole tire and shredded tire, each catering to specific operational needs and infrastructure capacities across various end-use industries. Among these, shredded tire has emerged as the dominant segment, largely due to its superior combustion efficiency and easier handling. Shredded tires are typically processed into chips or crumb rubber, which allows for better control over particle size and enhances the consistency of fuel feed in high-temperature combustion systems. These characteristics make shredded tire a more efficient and cleaner-burning option, particularly suitable for energy-intensive industries such as cement kilns, pulp and paper mills, and utility boilers that require a steady and reliable fuel source. In contrast, whole tire TDF, although representing a smaller share of the market, is still used in facilities that possess the specialized equipment necessary to process bulkier materials. These facilities, often located in regions with limited shredding infrastructure or where cost-saving measures are prioritized, can burn whole tires directly in their furnaces or incinerators. Despite its lower prevalence, whole tire TDF remains relevant in select applications due to its lower initial processing requirements.
By End- Use:
Cement manufacturing leads market adoption, leveraging the high calorific value and cost benefits of tire derived fuel to support sustainable operations. Utility boilers and pulp and paper mills also contribute significantly to market demand, using tire derived fuel to supplement traditional energy sources and reduce operational costs. The “Others” category encompasses industries such as steel manufacturing and waste-to-energy plants, reflecting growing interest in alternative fuels. It is clear that versatility in both fuel type and end-use application strengthens the market’s position and drives ongoing growth.
Segments:
Based on Type:
- Whole Tire
- Shredded Tire
Based on End- Use:
- Pulp and Paper Mills
- Utility Boilers
- Cement Manufacturing
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Tire Derived Fuel Market
North America Tire Derived Fuel Market grew from USD 96.77 million in 2018 to USD 118.79 million in 2024 and is projected to reach USD 156.76 million by 2032, reflecting a compound annual growth rate (CAGR) of 3.3%. North America is holding a 29% market share. The United States and Canada lead the region, driven by established recycling infrastructure, stringent waste management regulations, and the high adoption of sustainable fuel alternatives by the cement and energy sectors. Supportive policies and public-private partnerships further strengthen the market, making North America a prominent player in global tire-derived fuel initiatives.
Europe Tire Derived Fuel Market
Europe Tire Derived Fuel Market grew from USD 69.51 million in 2018 to USD 82.49 million in 2024 and is projected to reach USD 99.82 million by 2032, at a CAGR of 2.2%. Europe accounts for 19% of the total market share. Key countries such as Germany, the United Kingdom, and France prioritize circular economy principles and enforce strict environmental regulations, encouraging the use of tire-derived fuel in cement kilns and power plants. Investment in advanced processing technologies and a growing emphasis on reducing landfill waste support regional market growth.
Asia Pacific Tire Derived Fuel Market
Asia Pacific Tire Derived Fuel Market expanded from USD 130.08 million in 2018 to USD 168.75 million in 2024 and is anticipated to reach USD 236.60 million by 2032, registering the fastest CAGR of 4.1%. Asia Pacific captures the largest market share at 41%. China, Japan, and India drive regional demand with rapid industrialization, growing energy needs, and government-backed waste management initiatives. Expansion of the manufacturing sector and increasing investment in alternative fuels further solidify the region’s leadership in the global market.
Latin America Tire Derived Fuel Market
Latin America Tire Derived Fuel Market increased from USD 13.53 million in 2018 to USD 16.63 million in 2024 and is expected to reach USD 18.98 million by 2032, growing at a CAGR of 1.4%. Latin America represents a 3% market share. Brazil and Mexico serve as primary markets, benefitting from evolving environmental regulations and initiatives to promote alternative fuels. Infrastructure development and gradual policy improvements create opportunities, although market growth remains moderate compared to other regions.
Middle East Tire Derived Fuel Market
Middle East Tire Derived Fuel Market advanced from USD 9.69 million in 2018 to USD 11.10 million in 2024 and is forecasted to reach USD 12.44 million by 2032, reflecting a CAGR of 1.2%. The Middle East holds a 2% share of the global market. Saudi Arabia and the United Arab Emirates spearhead regional adoption, focusing on integrating sustainable waste-to-energy solutions within national development agendas. Despite smaller market size, policy-driven projects and rising awareness of environmental impacts are expected to support future growth.
Africa Tire Derived Fuel Market
Africa Tire Derived Fuel Market moved from USD 7.78 million in 2018 to USD 10.36 million in 2024 and is set to reach USD 11.76 million by 2032, at a CAGR of 1.3%. Africa accounts for 2% of the global market share. South Africa and Egypt stand out for implementing government-backed recycling programs and increasing industrial use of alternative fuels. Market expansion in Africa is gradual, limited by infrastructure gaps, yet steady progress in policy frameworks and awareness initiatives positions the region for long-term development.
Key Player Analysis
- Liberty Tire Recycling
- Lakin Tire
- Emanuel Tire
- Renelux Cyprus Ltd.
- Scandinavian Enviro Systems AB
- ResourceCo Pty Ltd
- Eco Green Equipment
- Genan Holding A/S
- Tire Disposal & Recycling Inc.
- Globarket Tire Recycling
Competitive Analysis
The Tire Derived Fuel Market features a dynamic competitive landscape shaped by leading players such as Liberty Tire Recycling, Lakin Tire, Emanuel Tire, Renelux Cyprus Ltd., Scandinavian Enviro Systems AB, ResourceCo Pty Ltd, Eco Green Equipment, Genan Holding A/S, Tire Disposal & Recycling Inc., and Globarket Tire Recycling. These companies drive market development through robust tire collection networks, advanced processing facilities, and continuous investment in technology to enhance fuel quality and environmental performance. Continuous research and development efforts drive the adoption of new techniques for shredding, emissions control, and material recovery, enabling suppliers to meet evolving regulatory requirements and the specific needs of industrial end-users. Market participants prioritize forming long-term partnerships with manufacturing and energy sectors to ensure reliable supply and expand their geographical presence. Differentiation is achieved through the delivery of consistent product quality, tailored fuel solutions, and integrated waste management services. The ability to navigate complex regulations, adapt to local market conditions, and provide sustainable alternatives positions top competitors for ongoing growth in the global tire derived fuel industry.
Recent Developments
- In June 2024, Golden Bay announced through a press release that it utilizes old tires and reprocessed timber in its production process to replace 55 to 60 per cent of the coal it consumed in the Portland factory. The organisation is targeting 2030 to completely become coal-free.
- In May 2024, BP p.l.c. entered an 8-year offtake deal with Circtec to annually acquire 60,000 tons of HUPATM renewable marine fuel and up to 15,000 tons of circular naphtha petrochemical feedstock. These products will come from Circtec's newly built large-scale facility. The agreement also binds BP for eight years under a take-or-pay commitment once factory operations commence.
- In May 2024, the U.S. Tire Manufacturers Association (USTMA) in collaboration with the Tire Industry Association (TIA) announced the constitution of the Tire Recycling Foundation during its ninth Tire Recycling Conference. The aim is to reprocess 100 per cent of end-of-life tires into circular, durable and tenable markets. This new program will obtain financing and distribute grants for research, intervention, education and demonstration projects.
Market Concentration & Characteristics
The Tire Derived Fuel Market exhibits moderate concentration, with a mix of established multinational recyclers and specialized regional players shaping the competitive landscape. It is characterized by a strong emphasis on technological advancement, regulatory compliance, and integrated supply chain management. The market relies on efficient tire collection, advanced shredding, and quality control systems to deliver consistent fuel performance for industrial end users. Strategic partnerships, innovation in processing methods, and investments in emission reduction technologies define market leadership. It demonstrates significant geographic diversity, with demand concentrated in regions that enforce strict environmental policies and support alternative fuel adoption. The market’s ability to adapt to evolving regulatory frameworks and sustainability goals further strengthens its resilience and long-term growth prospects.
Report Coverage
The research report offers an in-depth analysis based on Type, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Tire Derived Fuel Market will see steady demand from energy-intensive industries seeking cost-effective alternative fuels.
- Environmental regulations will continue to drive adoption of tire derived fuel in developed and emerging markets.
- Technological advancements will improve fuel quality, processing efficiency, and emissions control.
- Circular economy initiatives will increase the use of tire derived fuel in sustainable energy strategies.
- Expanding industrialization in Asia Pacific will create new growth opportunities for market participants.
- Partnerships between recyclers, manufacturers, and energy providers will strengthen supply chains and market reach.
- Investment in advanced collection and processing infrastructure will address supply consistency and quality issues.
- Growing public awareness and policy support will boost market acceptance and industry collaboration.
- Customization of fuel solutions for specific industrial applications will become more prominent.
- The market will remain competitive, with leading players focusing on innovation, regional expansion, and compliance with evolving standards.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Environmental Regulations
Governments worldwide are enforcing stricter environmental regulations on waste management and emissions, incentivizing industries to adopt tire derived fuel as an alternative to landfilling and traditional fossil fuels. These policies support recycling initiatives and provide regulatory and financial incentives for TDF adoption.
Cost Efficiency and High Calorific Value
Tire derived fuel offers a competitive calorific value and is often more cost-effective than conventional fossil fuels, making it attractive for energy-intensive industries such as cement manufacturing and power generation. The abundance of waste tires and efficient collection networks further reduce fuel costs for industrial users.
Technological Advancements in Processing and Emissions Control
Continuous improvements in shredding, de-wiring, and combustion technologies have enhanced the efficiency, safety, and environmental performance of tire derived fuel. These advancements enable facilities to meet stringent emission standards and maximize energy recovery, supporting broader market adoption.
Circular Economy and Sustainability Initiatives
The integration of circular economy principles encourages the conversion of end-of-life tires into valuable energy resources, reducing landfill waste and reliance on virgin fossil fuels. This aligns with global sustainability goals and attracts support from policymakers, investors, and environmentally conscious stakeholders.
Industrial Partnerships and Supply Chain Development
Strategic collaborations between tire recyclers, industrial fuel users, and government agencies are strengthening supply chains, improving collection infrastructure, and ensuring consistent quality and availability of tire derived fuel. These partnerships foster innovation and expand market reach.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Tire Derived Fuel Market?
What factors are driving the growth of the Tire Derived Fuel Market?
What are the key segments within the Tire Derived Fuel Market?
Who are the major players in the Tire Derived Fuel Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Whole Tire
- 1.2.2 Shredded Tire
- 1.3 By End-Use
- 1.3.1 Cement Manufacturing
- 1.3.2 Utility Boilers
- 1.3.3 Pulp and Paper Mills
- 1.3.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 408.12 million → 2032: USD 536.37 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Tire Derived Fuel Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Tire Derived Fuel Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Tire Derived Fuel Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Tire Derived Fuel Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Tire Derived Fuel Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Tire Derived Fuel Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Tire Derived Fuel Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Tire Derived Fuel Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 408.12 million → 2032: USD 536.37 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Tire Derived Fuel Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Whole Tire
- 12.3.7.2 Shredded Tire
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-Use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cement Manufacturing
- 12.4.7.2 Utility Boilers
- 12.4.7.3 Pulp and Paper Mills
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Tire Derived Fuel End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Tire Derived Fuel Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Tire Derived Fuel Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Tire Derived Fuel Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Liberty Tire Recycling
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Lakin Tire
- 18.4 Emanuel Tire
- 18.5 Renelux Cyprus Ltd.
- 18.6 Scandinavian Enviro Systems AB
- 18.7 ResourceCo Pty Ltd
- 18.8 Eco Green Equipment
- 18.9 Genan Holding A/S
- 18.10 Tire Disposal & Recycling Inc.
- 18.11 Globarket Tire Recycling
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

