
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year41,937.14 | 2023 |
| Forecast Period | 2024-2032 |
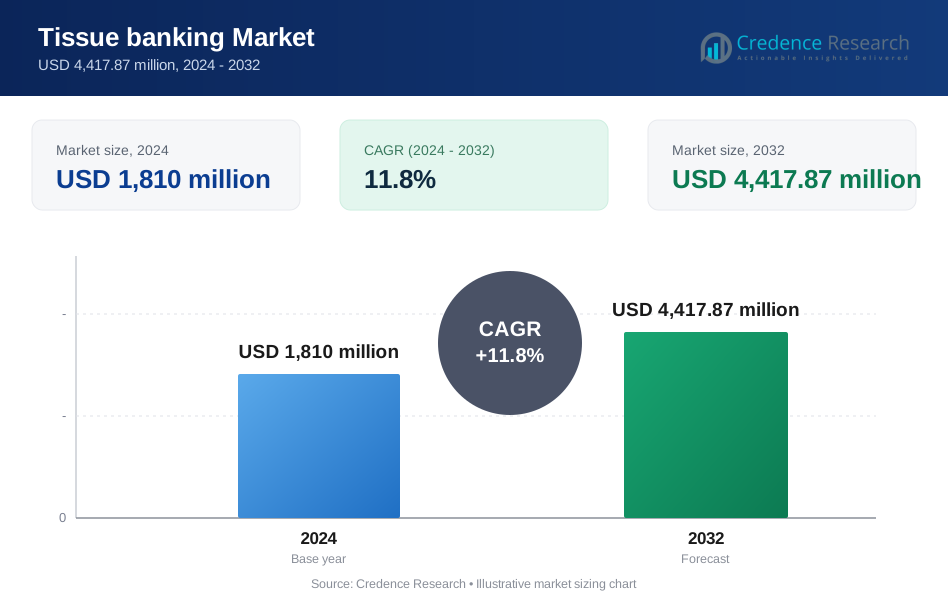
| Tissue Banking Market Size 2024 | USD 1,810 Million |
| Tissue Banking Market, CAGR | 11.8% |
| Tissue Banking Market Size 2032 | USD 4,417.87 Million |
Market Overview
The Tissue Banking Market is projected to grow significantly from USD 1,810 million in 2024 to USD 4,417.87 million by 2032, achieving a compound annual growth rate (CAGR) of 11.8%.
The Tissue Banking market is driven by the increasing demand for organ transplantation and regenerative medicine, as well as advancements in biobanking technologies that enhance storage and retrieval processes. Growing awareness of the benefits of stem cell therapy and the rising prevalence of chronic diseases further contribute to market expansion. Additionally, collaborations between research institutions and biobanks are fostering innovation in tissue preservation techniques. The regulatory environment is also evolving to support tissue banking practices, ensuring safety and efficacy. Together, these trends are positioning tissue banking as a critical component of modern healthcare and medical research.
The tissue banking market is characterized by significant geographical diversity, with North America leading in advancements due to its robust healthcare infrastructure and high research investment. Key players in this region include Thermo Fisher Scientific Inc., BioLifeSolutions, and Sigma-Aldrich Co., which drive innovation and quality standards. Europe follows closely, with Germany and the UK emerging as vital hubs, supported by companies like QIAGEN and Core Dynamics GmbH, focusing on stringent regulations and enhanced tissue preservation technologies. Asia Pacific is rapidly growing, fueled by increasing healthcare expenditures and a rising awareness of tissue donation and transplantation.
Market Drivers
Increasing Demand for Transplantation
The tissue banking market is significantly driven by the rising demand for organ and tissue transplants. An increasing number of patients requiring transplants due to accidents, chronic diseases, and congenital conditions highlights the urgent need for accessible tissue banks. For instance, a report by the Global Observatory on Donation and Transplantation (GODT) indicated that the global activity in organ transplantation saw an 11.3% increase in 2021 compared to the previous year, reflecting the growing need for transplants. As the prevalence of conditions necessitating transplantation grows, the healthcare system is compelled to enhance its capabilities in sourcing, preserving, and distributing tissues. This surge in demand creates a robust market environment where tissue banks play a crucial role in meeting the needs of patients and healthcare providers alike.
Advancements in Tissue Banking Technologies
Innovations in tissue banking technologies are transforming the landscape of tissue preservation, storage, and processing. Cutting-edge techniques, such as cryopreservation and advanced bioprocessing, have improved the quality and availability of tissues for transplantation. For instance, an international survey on tissue banking by the International Atomic Energy Agency (IAEA) highlighted the use of radiation technology to sterilize tissues, significantly enhancing the safety and viability of stored tissues. These advancements not only ensure the viability of stored tissues but also facilitate the efficient matching of donors and recipients. As technologies continue to evolve, tissue banks can provide safer, more effective, and higher-quality tissues, ultimately supporting better patient outcomes and enhancing the overall efficiency of transplantation procedures.
Rising Healthcare Expenditure
Global increases in healthcare expenditure are paving the way for enhanced investment in tissue banking infrastructure and research. As governments and private sectors allocate more resources to healthcare initiatives, the tissue banking market benefits from improved facilities, state-of-the-art equipment, and robust research funding. This financial backing enables tissue banks to expand their operations, explore new methodologies, and contribute to advancements in regenerative medicine and transplantation. Consequently, the growth in healthcare spending is a vital enabler of tissue banking market development.
Government Initiatives and Emerging Applications
Government support through initiatives and regulatory frameworks promotes the growth of the tissue banking market. Funding for research and development, as well as streamlined regulations, encourages innovation and compliance within the industry. Additionally, the emergence of applications in tissue engineering and regenerative medicine is driving demand for tissue banks. As these fields continue to evolve, they offer promising solutions for various medical conditions, further solidifying the importance of tissue banks in modern healthcare. Together, these factors create a thriving ecosystem for tissue banking, fostering advancements that benefit patients and the medical community.
Market Trends
Growing Demand for Tissue Transplants
The tissue banking market is experiencing a notable trend driven by the increasing demand for tissue transplants. This surge is largely attributed to the aging global population, which significantly raises the need for transplants, especially in orthopedic and cardiovascular procedures. As individuals age, they are more prone to conditions that require tissue replacement, thus amplifying the market's growth. Moreover, accidents and traumatic injuries are major contributors to this demand, as these incidents often necessitate tissue grafts to aid recovery. Chronic diseases, including diabetes, arthritis, and cancer, further drive the need for tissue repair and replacement, highlighting the critical role of tissue banks in providing essential grafts. This growing demand not only underscores the importance of tissue banking in modern healthcare but also creates opportunities for expansion and innovation within the industry.
Advancements in Tissue Banking Technologies
Another significant trend influencing the tissue banking market is the rapid advancement of technologies in tissue preservation and processing. Improved preservation techniques, such as enhanced cryopreservation, allow for longer-term storage of tissues, increasing their availability for transplantation. For instance, the International Atomic Energy Agency (IAEA) has been actively supporting the development of tissue banking by providing financial and technical assistance to establish tissue banks, particularly in developing countries. This innovation ensures that high-quality tissues can be stored effectively until they are needed, thus addressing the challenges of supply and demand. Additionally, advanced processing methods are enhancing the safety and quality of tissues, further encouraging their use in transplantation. Coupled with these advancements is the rise of regenerative medicine and tissue engineering, which holds the potential to grow and repair tissues in situ, thereby reducing dependence on traditional tissue banking. These fields not only represent the forefront of medical science but also promise to revolutionize how tissues are sourced and utilized, providing new solutions for patients and healthcare providers alike.
Market Challenges Analysis
Ethical Considerations and Regulatory Hurdles
The tissue banking industry faces significant ethical challenges that must be navigated to ensure the integrity and efficacy of the sector. Obtaining informed consent from donors is paramount, requiring clear communication about the donation process and its implications. For instance, a review by the International Atomic Energy Agency (IAEA) emphasized the importance of transparent communication and informed consent in tissue banking to maintain donor trust and ethical standards. Additionally, strict privacy protocols must be enforced to protect donor information and maintain public trust. A critical aspect of these ethical considerations is equitable access to tissue donations and transplants. It is essential to address disparities in access, particularly in underserved communities where patients may face barriers to receiving timely and appropriate care. Furthermore, the industry is burdened by complex regulatory hurdles. Compliance with stringent regulations governing tissue collection, processing, storage, and distribution can be resource-intensive and challenging for tissue banks. This complexity is exacerbated by the need for international harmonization of standards, which would facilitate cross-border tissue exchange and promote collaboration among global tissue banking entities.
Supply and Demand Imbalance and Technical Challenges
The tissue banking market is also grappling with a notable supply and demand imbalance, leading to significant challenges in patient care. The growing demand for tissue transplants often outstrips the available supply, resulting in waiting lists that can delay critical procedures for patients in need. Compounding this issue is the scarcity of donors, which requires ongoing efforts to encourage tissue donation while addressing societal and cultural barriers that may discourage participation. Technical challenges in tissue preservation further complicate the situation; developing advanced techniques to maintain tissue quality over extended periods is vital for ensuring that tissues remain viable for transplantation. Additionally, implementing robust quality control measures is essential to guarantee the safety and efficacy of stored tissues, as any lapse in quality can have dire consequences for recipients. The high costs associated with tissue banking and transplantation represent another significant barrier, making it prohibitively expensive for many patients. Securing adequate insurance coverage for tissue-related procedures is critical to improving accessibility and ensuring that all patients can benefit from these life-saving interventions. Addressing these multifaceted challenges is essential for the continued growth and success of the tissue banking sector, ultimately enhancing patient outcomes and fostering greater public trust in the system.
Market Segmentation Analysis:
By Product:
The tissue banking market is segmented by product, including various equipment essential for the preservation and processing of tissues. Key equipment segments comprise cryopreservation equipment, which plays a critical role in the long-term storage of tissues by utilizing low temperatures to maintain cellular integrity. Thawing equipment is also vital, as it ensures safe and effective re-warming of preserved tissues prior to transplantation. Quality control equipment is crucial for maintaining safety and efficacy standards, allowing tissue banks to adhere to stringent regulatory requirements. Additionally, media and consumables, such as preservation solutions and culture media, support the overall functionality of tissue banking operations. The effective integration of these products enhances tissue viability and optimizes processing protocols, ultimately contributing to successful transplantation outcomes.
By Tissue Type:
Tissue banking also categorizes itself based on tissue types, which include heart valves, corneas, brain and spinal cord tissues, as well as bone and skin. The demand for heart valves is driven by the increasing prevalence of cardiovascular diseases, necessitating reliable access to quality grafts for transplantation. Corneal banking is essential for addressing vision-related ailments, as corneal transplants are common procedures. Moreover, tissues derived from the brain and spinal cord are gaining traction in regenerative medicine and neurological therapies. Bone and skin tissues are frequently utilized in orthopedic and reconstructive surgeries, highlighting the diverse applications of tissue banking across medical disciplines. By understanding these segments, stakeholders can better align their offerings with market demands, ensuring the availability of critical resources for healthcare providers and patients alike.
Segments:
Based on Product
- Equipment
- Cryopreservation Equipment
- Thawing Equipment
- Quality Control Equipment
- Others
- Media and Consumables
Based on Tissue Type
- Heart Valves
- Cornea
- Brain and Spinal Cord
- Bone and Skin
Based on Application
- Therapeutic
- Cosmetic
- Research and Development
- Drug Discovery
Based on End-User
- Biobanks
- Hospitals and Clinics
- Research and Academic Institutes
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the global tissue banking market, accounting for approximately 40% of the total market revenue in 2024. This dominance can be attributed to advanced healthcare infrastructure, a high prevalence of chronic diseases, and substantial investment in research and development. The region's robust regulatory framework also supports tissue banking operations, ensuring high safety and quality standards. Moreover, growing public awareness about the importance of tissue donation, coupled with governmental initiatives promoting organ and tissue donation, has further fueled market growth. The increasing demand for tissue transplants, driven by an aging population and rising rates of accidents, reinforces North America's leading position in the tissue banking sector.
Asia-Pacific
In contrast, the Asia-Pacific region is emerging as a vital market for tissue banking, projected to capture approximately 25% of the global market share by 2032. This growth is primarily driven by the increasing healthcare expenditure, rapid advancements in medical technologies, and a rising population with diverse healthcare needs. Countries like Japan, China, and India are investing heavily in improving their healthcare infrastructure, which includes enhancing tissue banking facilities. Additionally, the rising prevalence of chronic diseases and a growing understanding of regenerative medicine and tissue engineering are creating new opportunities for tissue banks in this region. As the Asia-Pacific region continues to expand its capabilities and increase awareness of tissue donation, it is poised for significant growth in the coming years.
Key Player Analysis
- BioLifeSolutions (U.S.)
- Thermo Fisher Scientific Inc. (U.S.)
- Lifeline Scientific (U.S.)
- Sigma-Aldrich Co. (U.S.)
- BioCision, Cesca Therapeutics, Inc. (U.S.)
- Atlanta Biologics Pvt. Ltd. (U.S.)
- Core Dynamics GmbH (Germany)
- QIAGEN (Germany)
- Panasonic Holdings Corporation (Japan)
- Taylor-Wharton (U.S.)
- Custom Biogenic Systems (U.S.)
Competitive Analysis
The tissue banking market is highly competitive, with leading players focusing on innovation and quality to enhance their market positions. Thermo Fisher Scientific Inc., Sigma-Aldrich Co., BioLifeSolutions, Lifeline Scientific, and QIAGEN are at the forefront, offering advanced products and services. These companies leverage cutting-edge technologies, such as cryopreservation and quality control equipment, to meet the growing demand for tissue transplants. This commitment to technological advancement allows firms to improve tissue preservation techniques and ensure the safety and efficacy of their products. Additionally, collaborations and strategic partnerships are becoming increasingly common, enabling companies to leverage complementary strengths and expand their market reach. Furthermore, the increasing support from government initiatives for tissue banking infrastructure and public awareness campaigns enhances the growth potential of the market, driving competition among players to meet the rising demand for tissue transplants. As a result, firms are constantly adapting to changing market dynamics to secure their competitive edge in this evolving landscape.
Recent Developments
- In November 2022, the Department of Health (DoH), Abu Dhabi, the regulator of the healthcare sector in the United Arab Emirate, and United States-based Eversight, one of the non-profit eye banks in the world, partnered to establish the country's first Eye and Tissue Bank.
- In June 2022, LifeLink Tissue Bank launched the Birth Tissue Donation Program, the first of its kind in the Tampa Bay area, in partnership with Tampa General Hospital (TGH).
- In February 2022, Merck announced the Organizational Transformation of the Life Science Business Sector to strengthen CDMO offering and accelerate future growth.
- In April 2022, Avantor Korea signed a collaboration agreement with Kyung Hee University Medical Center (KHMC) Medical Science Research Institute.
Market Concentration & Characteristics
The tissue banking market exhibits a moderate level of concentration, with a mix of established players and emerging companies competing for market share. The market is characterized by significant investments in research and development, aimed at enhancing tissue preservation technologies and expanding product offerings. Leading organizations often leverage strategic partnerships and collaborations to strengthen their market presence and improve operational efficiencies. Furthermore, the industry is marked by stringent regulatory requirements, which necessitate compliance with quality and safety standards, influencing operational practices among players. Innovations in cryopreservation and quality control technologies play a crucial role in shaping competitive dynamics, as companies strive to differentiate themselves through advanced solutions. The increasing demand for tissue transplants, driven by an aging population and rising incidence of chronic diseases, further intensifies competition. Overall, the market's characteristics reflect a focus on quality, technological advancement, and regulatory compliance, essential for sustaining growth in this vital sector.
Report Coverage
The research report offers an in-depth analysis based on Product, Tissue Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The tissue banking market is expected to continue growing significantly, driven by increasing demand for transplants and advancements in medical technologies.
- Innovations in preservation and processing techniques will enhance tissue quality and availability, contributing to improved patient outcomes.
- The rising incidence of chronic diseases and an aging population will further fuel the need for tissue grafts and transplants.
- Government initiatives and funding for tissue banking research will bolster infrastructure development and innovation in the field.
- Collaborations between research institutions and tissue banks will lead to breakthroughs in regenerative medicine and tissue engineering.
- Ethical considerations surrounding tissue donation will drive the establishment of clearer guidelines and consent processes.
- Public awareness campaigns will promote tissue donation, addressing misconceptions and encouraging donor participation.
- Regulatory frameworks will evolve to ensure stringent safety and quality standards, fostering public trust in tissue banking.
- The integration of advanced technologies, such as AI and automation, will streamline operations and enhance data management in tissue banks.
- The growing market for personalized medicine will create new opportunities for tissue banking in drug development and research applications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Tissue Banking market?
What factors are driving the growth of the Tissue Banking market?
What are the key segments within the Tissue Banking market?
What are some challenges faced by the Tissue Banking market?
Who are the major players in the Tissue Banking market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Tissue banking Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Tissue banking Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,810 million → 2032: USD 4,417.87 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Tissue banking Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Tissue banking Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Tissue banking Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Tissue banking Market Drivers
- 3.3 Tissue banking Market Restraints & Challenges
- 3.4 Tissue banking Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Tissue banking Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Tissue banking Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Tissue banking category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Tissue banking Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Tissue banking Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Tissue banking market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Tissue banking Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Tissue banking Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Tissue banking Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Tissue banking (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Tissue banking Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Tissue banking Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Tissue banking Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Tissue banking Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Tissue banking Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Tissue banking Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Tissue banking Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Tissue banking Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Tissue banking Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
