
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Science, Technology, Engineering, and Mathematics (STEM) Toys Market Size 2024 | USD 6,464.86 million |
| Science, Technology, Engineering, and Mathematics (STEM) Toys Market, CAGR | 7.10% |
| Science, Technology, Engineering, and Mathematics (STEM) Toys Market Size 2032 | USD 11,190.94 million |
Market Overview
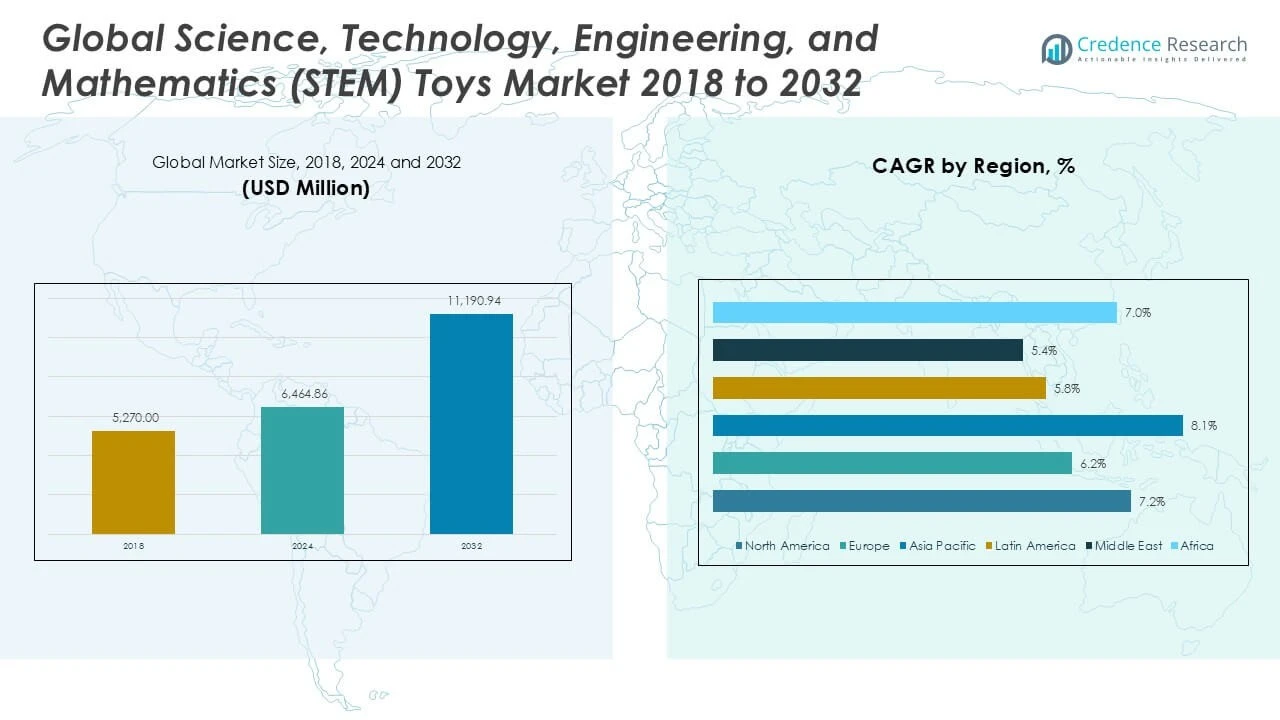
The Global Science, Technology, Engineering, and Mathematics (STEM) Toys Market is projected to grow from USD 6,464.86 million in 2024 to an estimated USD 11,190.94 million by 2032, with a compound annual growth rate (CAGR) of 7.10% from 2025 to 2032.
Market drivers include the growing emphasis on early childhood education, government initiatives supporting STEM curricula, and the integration of technology in learning environments. Trends shaping the market involve the adoption of AI and augmented reality (AR) in toy designs, enhancing engagement and experiential learning. Additionally, the increasing availability of affordable STEM toys in emerging economies is expanding market penetration. Manufacturers focus on product diversification, incorporating robotics, coding kits, and science experiment sets that appeal to a broad age range, fueling sustained market momentum.
Regionally, North America dominates the STEM toys market, supported by strong educational frameworks and high consumer spending on educational products. Europe follows closely, driven by government policies promoting STEM learning. The Asia-Pacific region exhibits the fastest growth due to rising disposable incomes, expanding middle-class populations, and increasing awareness of STEM education benefits. Key players in this market include LEGO Group, Mattel, Inc., Hasbro, Inc., Spin Master Corp., and Thames & Kosmos, who continuously innovate to capture evolving consumer demands globally.
Market Insights
- The Global STEM Toys Market is projected to grow from USD 6,464.86 million in 2024 to USD 11,190.94 million by 2032, registering a CAGR of 7.10% during 2025-2032.
- Rising emphasis on early childhood education and development of critical thinking skills significantly drives market demand worldwide.
- Government initiatives promoting STEM curricula and integration of technology in education reinforce growth opportunities for STEM toys.
- High production costs and complex educational content pose challenges, limiting affordability and adoption in some regions.
- North America holds the largest market share, supported by advanced educational infrastructure and strong consumer spending.
- Asia-Pacific exhibits the fastest growth, fueled by rising disposable incomes, expanding middle-class populations, and increasing STEM awareness.
- Market players focus on innovation through AI, augmented reality, and product diversification to maintain competitiveness and capture emerging markets.
Market Drivers
Increasing Focus on Early Childhood Education and Skill Development
Governments and educational institutions worldwide prioritize early childhood education to build foundational skills for future academic success. The Science, Technology, Engineering, and Mathematics (STEM) Toys Market benefits from growing awareness among parents and educators about the importance of developing problem-solving, critical thinking, and creativity in children. These toys provide hands-on learning experiences that reinforce STEM concepts, making education engaging and effective. Demand rises because parents seek tools that prepare children for competitive academic and career environments. It also supports interactive learning, helping children grasp complex subjects at an early stage. This focus drives manufacturers to innovate products that cater to various age groups and learning levels.
- For instance, according to a 2023 survey by the Toy Association, 94% of parents acknowledged the significant role of toys in their child's development, with 91% emphasizing the importance of educational toys in fostering learning and overall growth
Government Initiatives and Support for STEM Education Worldwide
Governments implement programs and policies encouraging STEM education to address skill gaps in science and technology sectors. It creates a favorable environment for the growth of the STEM toys market by integrating educational toys into formal and informal learning systems. Funding for schools and community programs often includes resources for STEM toys and kits, expanding access to quality educational materials. The push toward digital literacy and scientific competence fuels demand for toys that teach coding, robotics, and engineering concepts. These initiatives raise public interest and increase adoption rates, accelerating market expansion. Industry players respond by aligning product portfolios with government standards and curricula.
- For instance, India produces 31.7% of all STEM graduates worldwide, with government initiatives such as the STEM India Foundation providing educators with resources to enhance STEM learning
Technological Advancements Driving Innovation in Educational Toys
Rapid advancements in technology enable the development of sophisticated STEM toys featuring artificial intelligence, augmented reality, and interactive components. It enriches the learning experience by combining play with real-world applications, increasing engagement and knowledge retention. Manufacturers incorporate smart features and app integration to appeal to tech-savvy children and parents. The market experiences continuous product evolution, keeping it relevant to changing educational trends and consumer expectations. Such innovation attracts a broader audience, including schools and homeschooling families. This drive for advanced features strengthens competitive positioning for leading companies.
Expanding Market Reach through Increased Affordability and Availability
Growing disposable incomes and e-commerce penetration allow STEM toys to reach a wider audience, especially in emerging markets. It enables families from diverse economic backgrounds to invest in quality educational products. Retailers and manufacturers focus on cost-effective production and distribution strategies to make STEM toys more accessible. Localization of products to suit regional preferences and curricula further supports market penetration. The rise of online platforms facilitates easier discovery and purchase, increasing consumer convenience. This wider reach fuels demand and sustains steady market growth globally.
Market Trends
Integration of Artificial Intelligence and Augmented Reality to Enhance Learning Experiences
The Science, Technology, Engineering, and Mathematics (STEM) Toys Market increasingly incorporates artificial intelligence (AI) and augmented reality (AR) technologies to create immersive and interactive learning environments. It allows children to engage with educational content in a more dynamic and personalized way, fostering deeper understanding of complex concepts. AI-powered toys adapt to a child’s learning pace, offering customized challenges that improve skill development. AR applications bring abstract STEM principles to life, bridging the gap between theoretical knowledge and practical application. These technological enhancements attract both parents and educators seeking innovative tools that make learning enjoyable. The adoption of such advanced features strengthens market competitiveness and encourages continuous product innovation.
- For instance, the number of AI-powered STEM toys introduced annually has exceeded 1,300 unique models globally, reflecting the growing demand for interactive learning solutions
Rise in Demand for Coding and Robotics Kits Supporting Future Career Skills
Demand for coding and robotics kits surges within the STEM toys market, driven by increasing awareness of digital literacy’s role in career readiness. It empowers children to develop programming skills and logical thinking, which align with workforce requirements in technology-driven industries. These kits often provide modular components that encourage experimentation and creativity. Schools and homeschooling communities adopt such products to supplement formal education, expanding market reach. Manufacturers respond by offering diverse product lines that cater to different age groups and proficiency levels. This trend reinforces the importance of hands-on learning tools in preparing the next generation for evolving job markets.
- For instance, the number of coding and robotics kits available for educational purposes has grown to 1,100+ distinct models, as institutions and parents prioritize STEM-based learnin
Growing Preference for Eco-Friendly and Sustainable Materials in Toy Manufacturing
Consumers demonstrate rising interest in environmentally responsible products, influencing manufacturers in the Science, Technology, Engineering, and Mathematics (STEM) Toys Market to adopt sustainable materials. It drives the use of biodegradable plastics, recycled components, and non-toxic paints in toy production. This shift not only addresses environmental concerns but also appeals to socially conscious buyers. Companies increasingly highlight sustainability in their branding and product development strategies. Regulatory pressures and consumer demand push the market toward greener practices. Incorporating eco-friendly materials supports long-term market viability and enhances corporate reputation.
Expansion of E-commerce Channels Accelerating Global Market Penetration
The growth of e-commerce platforms plays a significant role in broadening access to STEM toys across international markets. It offers consumers convenient purchasing options and a wider variety of products than traditional retail outlets. Online reviews and detailed product descriptions help buyers make informed decisions. The Science, Technology, Engineering, and Mathematics (STEM) Toys Market leverages digital marketing strategies to target niche customer segments effectively. Efficient logistics and delivery systems ensure timely product availability, enhancing customer satisfaction. This trend facilitates faster market growth and strengthens brand presence worldwide.
Market Challenges
High Production Costs and Pricing Barriers Limiting Market Accessibility
The Science, Technology, Engineering, and Mathematics (STEM) Toys Market faces challenges due to the high costs involved in designing and manufacturing advanced educational toys. It requires investments in research, development, and integration of sophisticated technologies like AI and robotics. These costs often translate into higher retail prices, which may restrict affordability for some consumer segments, especially in emerging economies. Limited purchasing power in certain regions reduces market penetration potential. Manufacturers must balance innovation with cost-efficiency to expand accessibility. Pricing barriers can also impact adoption in educational institutions with tight budgets. Overcoming this challenge demands strategic sourcing and streamlined production processes.
- For instance, over 1,200 new STEM toy models were introduced globally in 2024, reflecting the industry's commitment to innovation and educational development
Complexity of Educational Content and Consumer Awareness Affecting Adoption Rates
STEM toys often involve complex concepts that require clear communication to ensure user engagement and learning effectiveness. It creates difficulties for parents and educators who may lack familiarity with STEM principles, leading to hesitation in purchasing these products. Limited consumer awareness about the benefits and usability of STEM toys slows market growth. Furthermore, inadequate instructional support or complicated interfaces may discourage prolonged use by children. The market needs to address these issues through effective educational marketing and simplified product designs. Improving user experience and increasing awareness will boost acceptance and sustained demand.
Market Opportunities
Expansion into Emerging Economies with Rising Educational Investments and Digital Adoption
The Science, Technology, Engineering, and Mathematics (STEM) Toys Market holds significant growth potential in emerging economies where increasing investments in education drive demand for innovative learning tools. It can capitalize on rising disposable incomes and expanding middle-class populations in regions such as Asia-Pacific, Latin America, and Africa. Governments in these areas emphasize improving STEM education infrastructure, creating favorable conditions for market entry. Expanding internet penetration and smartphone usage enable access to tech-enabled toys through e-commerce platforms. Tailoring products to local curricula and cultural preferences further enhances market acceptance. This opportunity allows companies to broaden their customer base and establish strong regional footprints.
Development of Customized and Subscription-Based Learning Solutions to Enhance Engagement
The demand for personalized learning experiences opens new avenues for the Science, Technology, Engineering, and Mathematics (STEM) Toys Market to innovate beyond traditional products. It can leverage subscription-based models offering curated kits and digital content that evolve with a child’s skill level. Customization enhances user engagement by aligning with individual interests and educational goals. Integration with online platforms allows continuous learning and community interaction, fostering deeper brand loyalty. Companies adopting this approach differentiate themselves by providing flexible and scalable educational solutions. This trend supports long-term customer retention and recurring revenue streams.
Market Segmentation Analysis
By Type
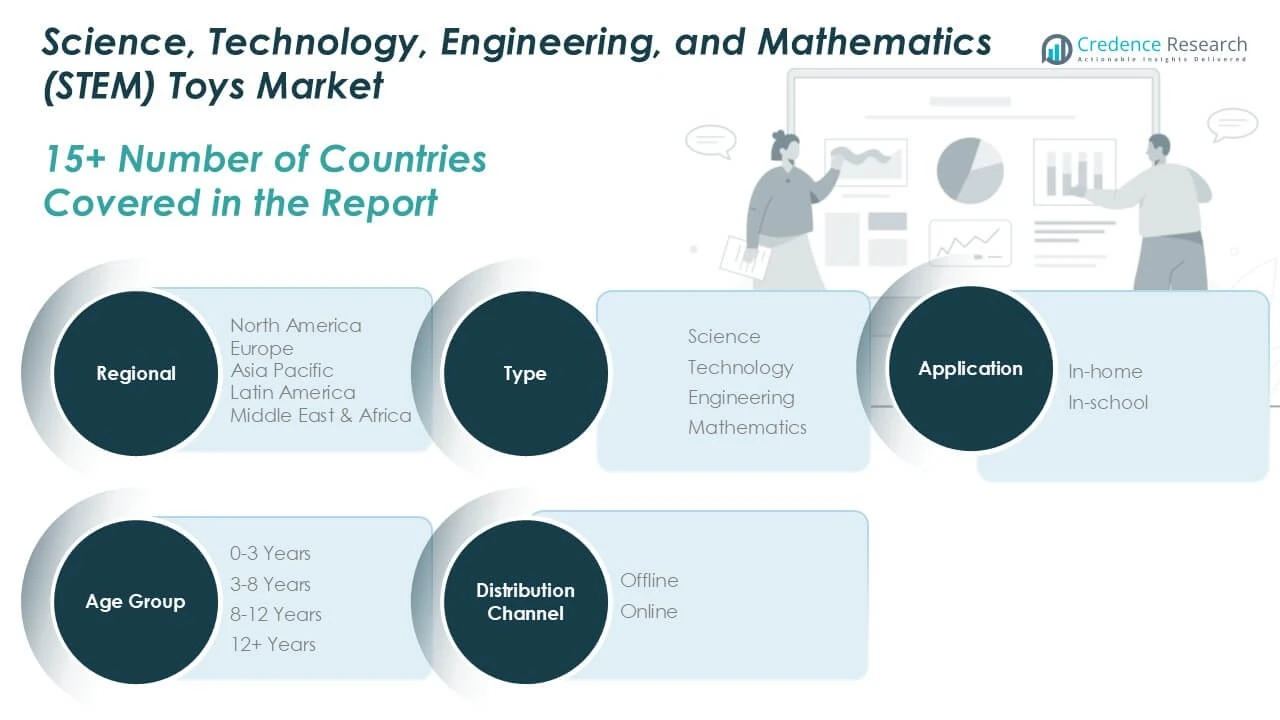
The Science, Technology, Engineering, and Mathematics (STEM) Toys Market segments by type include Science, Technology, Engineering, and Mathematics toys. The Science segment leads due to high demand for experimental kits and discovery-based products that foster scientific curiosity. Technology toys, featuring coding and robotics kits, gain traction with growing emphasis on digital skills. Engineering toys appeal through construction and mechanical building sets, encouraging problem-solving abilities. Mathematics toys support numeracy and logical thinking, though they represent a smaller share compared to other segments. Each type caters to different learning needs, contributing to diversified market growth.
By Application
By application, the market divides into In-home and In-school usage. In-home applications dominate as parents increasingly invest in educational toys to supplement formal learning. In-school adoption grows through integration into curricula and after-school programs, supported by government initiatives. Both settings drive demand but require tailored product designs to suit user environments and educational goals.
By Age Group
The age group segmentation covers 0-3 years, 3-8 years, 8-12 years, and 12+ years. The 3-8 years segment accounts for the largest revenue share, driven by products designed to develop foundational STEM skills in early learners. The 8-12 years group also shows strong growth with advanced kits. Age-appropriate design and cognitive development stages influence product offerings and market penetration.
By Distribution Channel
Distribution channels split into Online and Offline. Online sales expand rapidly due to convenience, broader selection, and digital marketing efforts. Offline channels, including specialty stores and toy retailers, maintain relevance for hands-on shopping experiences. The Science, Technology, Engineering, and Mathematics (STEM) Toys Market benefits from the complementary roles of both channels in reaching diverse consumer segments.
Segments
Based on Type
- Science
- Technology
- Engineering
- Mathematics
Based on Application
- In-home
- In-school
Based on Age Group
- 0-3 Years
- 3-8 Years
- 8-12 Years
- 12+ Years
Based on Distribution Channel
- Online
- Offline
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Science, Technology, Engineering, and Mathematics (STEM) Toys Market
The North America Science, Technology, Engineering, and Mathematics (STEM) Toys Market held a value of USD 2,139.38 million in 2024 and is projected to reach USD 3,723.84 million by 2032, growing at a CAGR of 7.2%. It accounts for approximately 30.3% of the global market share in 2024, making it one of the largest regional markets. The region benefits from strong consumer awareness, high disposable income, and well-established educational frameworks that emphasize STEM learning. Government support and private sector investments further drive adoption across homes and schools. The presence of leading market players and advanced retail infrastructure strengthens its market position. Innovation in product development caters to evolving consumer preferences.
Europe Science, Technology, Engineering, and Mathematics (STEM) Toys Market
Europe’s STEM toys market reached USD 1,530.70 million in 2024 and is expected to grow to USD 2,470.65 million by 2032, with a CAGR of 6.2%. The region represents roughly 21.7% of the global market share in 2024. Growing emphasis on STEM education and sustainability supports demand across Western and Northern Europe. It faces moderate growth driven by stringent regulatory frameworks and high consumer standards. Educational reforms incorporating STEM curricula enhance in-school adoption rates. Manufacturers focus on localized product offerings tailored to diverse linguistic and cultural requirements. The region’s mature market encourages steady innovation and quality enhancement.
Asia Pacific Science, Technology, Engineering, and Mathematics (STEM) Toys Market
Asia Pacific commands a significant share of about 28.8% of the global STEM toys market with a valuation of USD 2,035.43 million in 2024. It is forecasted to expand to USD 3,795.33 million by 2032, registering the highest CAGR of 8.1%. Rapid urbanization, increasing disposable incomes, and rising awareness of STEM education in countries like China, India, and Japan drive this growth. Expanding e-commerce penetration facilitates wider accessibility of STEM toys in urban and semi-urban regions. Governments invest heavily in educational infrastructure to bridge skill gaps in science and technology. Market players actively adapt products to local needs and language preferences to capture emerging consumer segments.
Latin America Science, Technology, Engineering, and Mathematics (STEM) Toys Market
The Latin America STEM toys market stood at USD 349.68 million in 2024 and is projected to reach USD 545.33 million by 2032, growing at a CAGR of 5.8%. It represents approximately 4.9% of the global market share. Growing educational reforms and increased focus on improving science and technology skills among youth drive demand. Brazil and Mexico dominate the regional market due to population size and investment in education. Limited awareness and affordability challenges restrict rapid expansion in certain areas. Market players explore partnerships with educational institutions to enhance reach and penetration. The region holds long-term growth potential with gradual infrastructure improvements.
Middle East Science, Technology, Engineering, and Mathematics (STEM) Toys Market
The Middle East market valued USD 207.48 million in 2024 and is forecast to reach USD 314.39 million by 2032, exhibiting a CAGR of 5.4%. It contributes around 2.9% of the global market share. Increased government initiatives to diversify economies and enhance education systems stimulate demand for STEM toys. Countries such as the UAE and Saudi Arabia lead regional adoption due to strong educational investments. The market faces challenges including limited product availability and high costs. Efforts to promote digital literacy and science education in schools support moderate growth. Companies target niche consumer segments through localized marketing strategies.
Africa Science, Technology, Engineering, and Mathematics (STEM) Toys Market
Africa’s STEM toys market accounts for approximately 2.9% of the global share, with a market size of USD 202.18 million in 2024. It is expected to grow to USD 341.39 million by 2032, registering a CAGR of 7.0%. Growth drivers include rising awareness of STEM education benefits and expanding urban middle-class populations in countries like South Africa and Nigeria. Limited infrastructure and affordability challenges constrain market size but gradual improvements create emerging opportunities. E-commerce platforms facilitate wider product availability. The market encourages collaboration between governments and private sectors to improve STEM literacy. Increased investment in educational technology will further boost market development.
Key players
- LEGO Group
- Hasbro, Inc.
- Hasbro India LLP
- Bandai Namco Holdings Inc.
- TAKARA TOMY Co., Ltd.
- Gigotoys
- Melissa & Doug, LLC
- VTech Holdings Ltd.
- Spin Master Corp
- BanBao Co., Ltd.
- Goldlok Toys Holdings Co., Ltd.
- Ravensburger AG
- MindWare, Inc.
- Smartivity Labs Pvt. Ltd.
Competitive Analysis
The Science, Technology, Engineering, and Mathematics (STEM) Toys Market remains highly competitive, driven by innovation and diverse product portfolios from leading players. Companies like LEGO Group and Hasbro, Inc. dominate through strong brand recognition and extensive distribution networks. They continuously invest in research and development to introduce interactive and tech-enabled toys that meet evolving educational needs. Regional players such as Smartivity Labs Pvt. Ltd. leverage localized content to capture niche markets. Market leaders focus on strategic partnerships, acquisitions, and product diversification to enhance market share. Competitive pricing and expanding e-commerce channels intensify rivalry among manufacturers. Innovation speed and ability to align products with educational trends determine market positioning. This dynamic competitive landscape encourages continuous improvement and consumer-centric offerings across the industry.
Recent Developments
- In 2025, LEGO Group continued to expand its STEM offerings with a range of sets designed to inspire young minds in science, technology, engineering, and mathematics.
- In 2025, Hasbro, Inc. launched the "Girl Innovators of Play" initiative, which includes a robust STEM-based bootcamp and invites girls between the ages of 13-24 to submit a social impact project idea.
- In 2025, Spin Master Corp revealed its top toy trends and a portfolio of new launches, emphasizing the integration of technology and creativity in play.
- In 2025, BanBao Co., Ltd. launched the "PowerBuild Pro," an electric engineering kit with over 500 pieces, designed to teach children about energy and mechanics through building and play
Market Concentration and Characteristics
The Science, Technology, Engineering, and Mathematics (STEM) Toys Market exhibits a moderately concentrated structure with a few key players such as LEGO Group, Hasbro, and Spin Master holding significant market shares. It features intense competition driven by continuous innovation, technological integration, and product differentiation. The market is characterized by rapid adoption of advanced educational technologies including robotics, coding kits, and augmented reality, which require substantial R&D investments. Smaller and regional players focus on niche segments and localized offerings to maintain relevance. Distribution channels diversify between online and offline platforms, expanding consumer reach globally. The market’s growth depends on manufacturers’ ability to quickly adapt to changing educational trends and consumer preferences while maintaining quality and affordability. This competitive yet evolving landscape fosters ongoing development of interactive and engaging STEM learning solutions.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Age Group, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The STEM toys market will experience sustained growth driven by increasing global emphasis on early childhood education and digital literacy development.
- Advancements in AI and augmented reality will further enhance the interactivity and educational value of STEM toys, attracting wider consumer interest.
- Expansion into emerging markets with rising disposable incomes will create new revenue streams and broaden the customer base globally.
- Manufacturers will invest more in customizable and subscription-based STEM learning kits to offer personalized and scalable educational experiences.
- Collaboration with educational institutions will intensify, promoting formal integration of STEM toys into school curricula and after-school programs.
- Sustainable and eco-friendly materials will gain prominence in product development, aligning with consumer demand for responsible manufacturing.
- Increasing e-commerce penetration will simplify access to STEM toys, boosting sales through online platforms and direct-to-consumer models.
- The rise of homeschooling and remote learning will increase demand for STEM toys that support self-directed and technology-driven education.
- Continuous innovation in coding, robotics, and engineering kits will cater to older children, addressing the need for advanced skill development.
- Regulatory frameworks supporting STEM education and digital skills training will encourage market expansion and attract more investments.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Emphasis on Early Childhood Education and Skill Development
Governments and parents are increasingly prioritizing early childhood education, recognizing the importance of foundational STEM skills for future academic and career success. This drives demand for STEM toys that foster problem-solving, critical thinking, and creativity in children.
Government Initiatives Supporting STEM Curricula
Many countries are implementing policies and funding programs to integrate STEM education into formal and informal learning environments. These initiatives often include resources for STEM toys, boosting adoption in both schools and homes.
Technological Advancements in Toy Design
Rapid innovation in AI, robotics, and augmented reality is enabling the creation of highly interactive and engaging STEM toys. These technologies enhance experiential learning, making STEM subjects more accessible and appealing to children.
Expansion of E-commerce and Affordability in Emerging Markets
Growing disposable incomes and the rise of online retail platforms are making STEM toys more accessible to a broader audience, especially in emerging economies. Manufacturers are focusing on cost-effective production and localized products to penetrate new markets.
Rising Demand for Coding and Robotics Kits
As digital literacy becomes essential for future careers, there is a surge in demand for toys that teach coding, robotics, and engineering concepts. These kits are increasingly adopted by both schools and parents to prepare children for technology-driven job markets.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the market size of the Global STEM Toys Market in 2023, and what is its expected size by 2032? What is the CAGR during this period?
What are the primary factors driving the growth of the STEM toys market?
Which regions dominate the STEM toys market, and why?
Who are the key players in the Global STEM Toys Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Science
- 1.2.2 Technology
- 1.2.3 Engineering
- 1.2.4 Mathematics
- 1.3 By Age Group
- 1.3.1 0-3 Years
- 1.3.2 3-8 Years
- 1.3.3 8-12 Years
- 1.3.4 12+ Years
- 1.4 By Application
- 1.4.1 In-home
- 1.4.2 In-school
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6,464.86 million → 2032: USD 11,190.94 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global STEM Toys Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global STEM Toys Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global STEM Toys Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global STEM Toys Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global STEM Toys Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global STEM Toys Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global STEM Toys Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global STEM Toys Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6,464.86 million → 2032: USD 11,190.94 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global STEM Toys Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Science
- 12.3.7.2 Technology
- 12.3.7.3 Engineering
- 12.3.7.4 Mathematics
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Age Group - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 0-3 Years
- 12.4.7.2 3-8 Years
- 12.4.7.3 8-12 Years
- 12.4.7.4 12+ Years
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 In-home
- 12.5.7.2 In-school
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global STEM Toys End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global STEM Toys Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global STEM Toys Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global STEM Toys Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 LEGO Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Hasbro, Inc.
- 18.4 Spin Master Corp.
- 18.5 Thames & Kosmos
- 18.6 VTech Holdings Ltd.
- 18.7 Melissa & Doug, LLC
- 18.8 Bandai Namco Holdings Inc.
- 18.9 Smartivity Labs Pvt. Ltd.
- 18.10 BanBao Co., Ltd.
- 18.11 Ravensburger AG
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

