
Market Overview
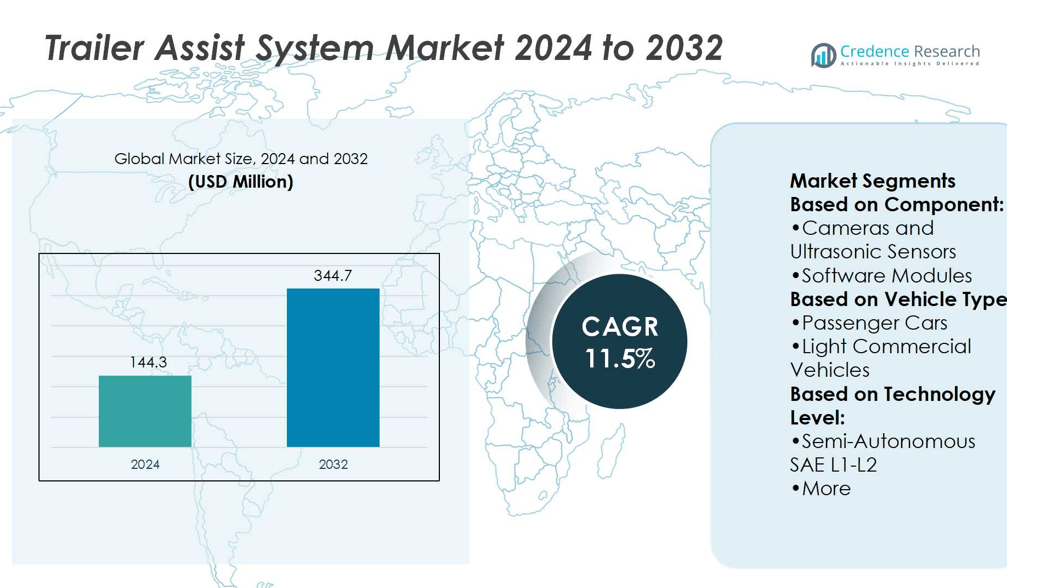
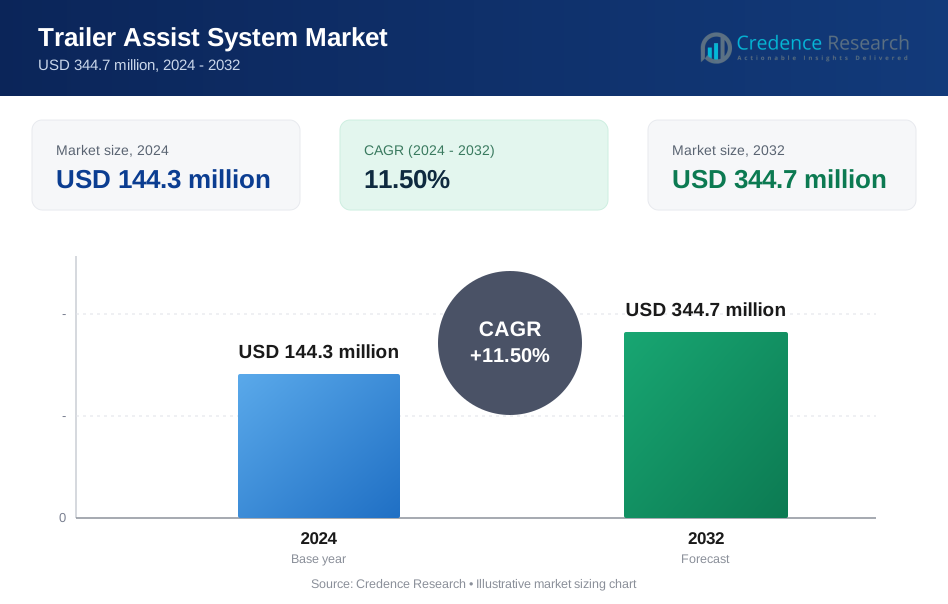
Trailer Assist System Market size was valued at USD 144.3 million in 2024 and is anticipated to reach USD 344.7 million by 2032, at a CAGR of 11.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Trailer Assist System Market Size 2024 | USD 144.3 million |
| Trailer Assist System Market, CAGR | 11.5% |
| Trailer Assist System Market Size 2032 | USD 344.7 million |
The Trailer Assist System Market grows through rising demand for safer and more convenient towing solutions. Increasing adoption of advanced driver assistance systems enhances vehicle safety standards and drives integration of trailer assist features. Automakers focus on embedding these systems into SUVs, pickup trucks, and commercial vehicles to meet consumer expectations. Advancements in cameras, ultrasonic sensors, and control algorithms improve maneuvering accuracy and user experience. Regulatory pressure for road safety and heightened awareness of towing risks further accelerate adoption. Growing use of smart and connected vehicles strengthens the market’s expansion, making trailer assist systems a mainstream automotive feature.
North America leads the Trailer Assist System Market with strong adoption in the U.S., while Europe follows with high integration driven by strict safety regulations and advanced OEM participation. Asia-Pacific records the fastest growth, fueled by rising vehicle ownership and infrastructure development. Latin America and the Middle East & Africa show gradual uptake supported by fleet modernization and logistics demand. Key players such as Bosch, Continental AG, Volkswagen, Magna, Garmin, and Hella drive innovation and expand system adoption across regions.
Market Insights
- Trailer Assist System Market size was valued at USD 144.3 million in 2024 and is projected to reach USD 344.7 million by 2032, growing at a CAGR of 11.5%.
- Rising demand for safer and more convenient towing solutions drives steady market expansion.
- Growing adoption of advanced driver assistance systems enhances safety standards and integration levels.
- Competition intensifies as automakers and technology suppliers focus on innovation and cost efficiency.
- High system costs and limited awareness in emerging regions act as restraints to wider adoption.
- North America leads the market, Europe follows with strong OEM participation, while Asia-Pacific shows the fastest growth.
- Latin America and the Middle East & Africa expand gradually, supported by fleet modernization and logistics development.
Market Drivers
Rising Demand for Vehicle Safety and Driver Assistance Features
The Trailer Assist System Market benefits from growing demand for advanced driver assistance features. Rising accident rates involving towing vehicles increase interest in technologies that reduce risks. Governments emphasize safety regulations that require enhanced stability and maneuverability systems. It strengthens the role of trailer assist in minimizing human errors during reversing or lane changing. Drivers recognize the advantage of improved precision and convenience while handling trailers. Growing adoption of ADAS packages supports the integration of trailer assist systems across vehicle segments.
- For instance, Garmin's BC 50 wireless backup camera is designed for longer vehicles like trucks and RVs and features a 50-foot transmission range. An optional extension cable can increase the range to 100 feet for even larger vehicle-trailer combinations.
Integration of Advanced Sensor and Camera Technologies
The market grows through innovations in sensors, cameras, and machine learning algorithms. It combines real-time monitoring with automated steering support to optimize trailer handling. Enhanced imaging systems improve accuracy in confined spaces, supporting safer operations for drivers. Automotive OEMs integrate trailer assist functions within broader infotainment and digital platforms. It ensures seamless connectivity with driver interfaces and vehicle telematics. Continuous improvements in hardware and software advance reliability and usability, driving higher adoption rates.
- For instance, Bosch’s Trailer Tow Assist employs a near-range camera that enables reversing with up to 1° steering accuracy, and supports 90° maneuvering in tight spaces—automating trailer alignment with minimal driver input.
Expansion of Towing Activities Across Commercial and Recreational Sectors
The Trailer Assist System Market sees growth from rising demand in logistics, construction, and leisure travel. Expanding e-commerce and freight activities increase the need for safe and efficient trailer operations. It enhances operational efficiency for fleets by reducing damages during loading and unloading processes. Recreational users adopt trailer assist systems to improve driving comfort when towing boats, campers, or caravans. Rising consumer preference for hassle-free towing supports adoption in pickup trucks and SUVs. The combination of efficiency and convenience reinforces the market’s appeal across diverse end-users.
Regulatory Push and Industry Collaborations Driving Standardization
Strong regulatory support influences adoption, as authorities encourage safety systems in heavy and light vehicles. The market gains momentum from industry collaborations between OEMs, suppliers, and technology providers. It leads to standardization of features across platforms, making trailer assist more accessible. Partnerships accelerate innovation in autonomous towing and integration with electric vehicles. Manufacturers position trailer assist as part of next-generation mobility ecosystems. Rising awareness of its value in reducing accidents supports regulatory acceptance and customer trust.
Market Trends
Growing Adoption of Advanced Driver Assistance Integration
The Trailer Assist System Market gains momentum through integration with broader driver assistance platforms. Automakers embed trailer assist functions with adaptive cruise control, lane-keeping, and parking sensors. This trend creates seamless vehicle management for users handling complex towing operations. It also improves maneuverability in tight spaces, boosting demand among recreational and commercial users. Automakers develop user-friendly dashboards that align with connected vehicle strategies. It signals an industry-wide shift toward integrated mobility ecosystems that support safer and smarter towing experiences.
- For instance, Hella’s SL | HD digital headlamp system—developed jointly with Porsche—features over 32,000 individually controllable LEDs per headlamp. This system enables real-time projection of lane guidance and precise light distribution based on steering data.
Rising Demand for Automation and Safety in Towing Operations
Automation stands as a major trend in the Trailer Assist System Market, reflecting a growing focus on safety. Drivers seek systems that reduce stress in reversing and parking scenarios with trailers. Commercial fleet operators value efficiency gains from automated maneuvering features. The technology reduces collision risks, making it attractive in logistics and utility applications. Regulatory focus on road safety also accelerates adoption in developed regions. It highlights how automation continues to transform towing into a safer and more reliable process.
- For instance, Westfalia’s Removable Tow Hook system delivers precise towing capacity of 2,200 kg and supports a vertical load of 100 kg. The design allows for an invisible bumper cutout when detached, and includes a detachable ball bar that weighs just 19.5 kg and measures 95 × 20 × 15 cm.
Expansion of Connectivity and Sensor-Based Technologies
The market advances through connectivity, sensors, and camera-based innovations that refine trailer assistance. Radar and ultrasonic sensors increase precision while camera systems improve visibility. Cloud-enabled solutions link towing performance data to driver applications and fleet platforms. It strengthens predictive maintenance, reduces errors, and improves vehicle-trailer coordination. Manufacturers promote real-time monitoring, which aligns with IoT and smart mobility initiatives. These advancements underscore the role of connected technologies in shaping the future of towing assistance.
Growing Penetration Across Recreational and Commercial Segments
The Trailer Assist System Market diversifies across recreational vehicles, caravans, and heavy-duty fleets. Recreational users adopt it for enhanced convenience in outdoor and lifestyle applications. Logistics firms embrace the systems to reduce training time for new drivers. Rental operators also integrate trailer assist to improve customer safety and experience. Growing trailer usage in agriculture and construction sectors further broadens adoption. The trend highlights its steady expansion from niche recreational use to mainstream commercial deployment.
Market Challenges Analysis
High Cost of Integration and Limited Consumer Awareness
The Trailer Assist System Market faces challenges linked to high integration costs across vehicle models. Premium systems demand advanced sensors, software, and calibration, raising overall vehicle prices. Mass adoption slows when customers perceive limited value compared to traditional driving skills. Consumer awareness also remains low in regions where towing is less frequent. It restricts demand among cost-sensitive buyers and smaller fleet operators. Manufacturers must balance affordability with advanced technology to achieve wider acceptance.
Technical Complexity and Regulatory Variations Across Regions
Technical challenges emerge from the complexity of integrating trailer assist with diverse vehicle platforms. Systems require compatibility with multiple trailer sizes, weight categories, and coupling types. Any mismatch impacts performance, raising concerns about reliability in real-world use. Regulatory variations across regions further complicate standardization and product rollout. It forces manufacturers to redesign features to meet local safety rules and certification demands. These obstacles hinder rapid expansion despite growing interest in automated towing solutions.
Market Opportunities
Expansion in Commercial and Fleet Applications
The Trailer Assist System Market presents opportunities in commercial transportation and fleet management. Logistics companies seek solutions that reduce driver fatigue and improve maneuvering efficiency with trailers. It enables safer operations in urban and congested environments, increasing operational productivity. Fleet operators benefit from shorter training periods and fewer accident-related costs. Manufacturers can offer tailored solutions for heavy-duty trucks, delivery vehicles, and utility fleets. Growing demand in construction, agriculture, and rental sectors further supports market expansion.
Advancements in Connected and Autonomous Vehicle Technologies
Technological progress in connectivity and semi-autonomous driving opens new opportunities for the Trailer Assist System Market. It can integrate with IoT platforms, telematics, and AI-driven navigation to enhance trailer control. Connected systems allow real-time monitoring of trailer behavior and predictive maintenance for fleet operators. Automakers can differentiate products by offering smarter, safer towing features. Expansion of smart city infrastructure and intelligent transport systems supports adoption in urban and commercial applications. Continuous innovation strengthens the market potential across recreational, commercial, and industrial segments.
Market Segmentation Analysis:
By Component
The Trailer Assist System Market is segmented into Cameras and Ultrasonic Sensors, Software Modules and Algorithms, and Electronic Control Units (ECUs). Cameras and ultrasonic sensors dominate adoption due to their critical role in providing accurate spatial awareness during reversing and maneuvering. It enhances driver confidence and reduces collision risks in complex towing scenarios. Software modules and algorithms manage the processing of sensor data and execute automated steering commands. These components improve system reliability and responsiveness under varied road conditions. ECUs coordinate communication between sensors and vehicle subsystems, ensuring seamless integration with braking and steering mechanisms. Advanced ECUs support updates and diagnostics, enhancing long-term system performance and fleet maintenance.
- For instance, Continental’s Ultrasonic Back-Up Sensor Kit includes four sensors, a central control unit, and a speaker. It activates an audible alarm when the vehicle comes within 10 feet of an object—beeping faster as the distance decreases—and can also trigger a voice announcement and overlay distance indicators on the display.
By Vehicle Type
Passenger cars, light commercial vehicles, and other vehicle categories form the market segmentation by vehicle type. Passenger cars lead in adoption due to growing recreational towing and lifestyle vehicle use. It provides convenience in reversing trailers and caravans, improving user safety and satisfaction. Light commercial vehicles gain traction in logistics, agriculture, and construction applications where trailer handling efficiency is crucial. Other vehicle types, including heavy-duty trucks and specialty vehicles, adopt systems to support fleet safety and operational efficiency. The growing trailer usage in commercial and industrial sectors drives demand across diverse vehicle platforms.
- For instance, Hitachi Astemo’s advanced AD-ECU features dual CPUs—one for recognition and one for vehicle control—enabling parallel processing and reducing response latency to under 50 milliseconds when integrating stereo-camera data with braking and steering actuation.
By Technology Level
The market further segments by technology level into Semi-Autonomous SAE L1-L2 and other advanced automation levels. Semi-autonomous systems dominate due to their capability to assist drivers without requiring full automation. It reduces manual intervention in trailer maneuvering while maintaining control and safety. Advanced automation levels integrate AI and predictive analytics for enhanced trailer guidance and obstacle avoidance. These systems appeal to fleet operators and premium vehicle buyers seeking smarter, safer towing solutions. Continuous development in sensor fusion, connectivity, and algorithm optimization strengthens market adoption across both consumer and commercial segments.
Segments:
Based on Component:
- Cameras and Ultrasonic Sensors
- Software Modules
Based on Vehicle Type:
- Passenger Cars
- Light Commercial Vehicles
Based on Technology Level:
- Semi-Autonomous SAE L1-L2
- More
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds the largest share of the Trailer Assist System Market, accounting for 34.37% in 2024. The U.S. remains the leading contributor, supported by a strong base of pickup trucks, RVs, and commercial trailers. Advanced driver assistance adoption and strict safety regulations drive early integration by leading automakers. Consumer demand for towing convenience continues to push product penetration across passenger and light commercial vehicles. The region’s leadership is reinforced by innovation and strong investments from both OEMs and technology suppliers. Canada and Mexico also show steady adoption, though the U.S. dominates with 81.34% of regional revenue.
Europe
Europe represents close to 30% of global share, supported by strict automotive safety norms and high consumer interest in premium vehicles. Countries such as Germany, France, and the U.K. see strong integration due to OEM leadership from Volkswagen, BMW, and Daimler. Caravanning culture and logistics expansion increase trailer usage, making assist systems more relevant. Regulations on advanced driver assistance encourage manufacturers to offer these systems as standard or optional packages. Growth is also supported by consumer preference for vehicles equipped with ADAS for both safety and convenience. Eastern Europe adds potential with rising adoption in logistics and fleet vehicles.
Asia-Pacific
Asia-Pacific contributes about 25% market share and is expected to record the fastest growth. China and India lead adoption through rising vehicle ownership and infrastructure expansion. Japan drives uptake with advanced technologies and demand from elderly drivers for safety-focused assistance. Strong CAGR of over 25% through 2032 highlights the region’s importance in shaping the future market. Consumer preference for safer and technology-driven cars is steadily increasing. Expanding logistics, rapid urbanization, and government backing for ADAS adoption strengthen the regional outlook. The shift toward electrified and connected vehicles further supports wider use of trailer assist solutions.
Latin America
Latin America holds a smaller market share of around 6%, with slower but steady growth expected. Brazil and Mexico dominate regional demand due to larger automotive production bases. Adoption is still at an early stage, limited by cost sensitivity and lower penetration of ADAS. However, rising awareness of towing safety and gradual modernization of fleets provide growth opportunities. Manufacturers see the region as a developing market with long-term potential. Strategic partnerships and imports are likely to expand access to trailer assist technologies in the coming years.
Middle East & Africa
The Middle East & Africa accounts for about 5% market share, with adoption mainly in the commercial sector. GCC countries like Saudi Arabia and the UAE lead regional growth, supported by expanding logistics and infrastructure projects. Passenger car adoption is slower due to limited consumer awareness and high cost of advanced systems. However, luxury vehicle imports often come equipped with trailer assist, creating a niche market. Africa shows modest demand, mostly linked to fleet modernization in South Africa. The region is expected to remain a small but gradually expanding market for trailer assist systems.
Key Player Analysis
Competitive Analysis
The competitive landscape of the Trailer Assist System Market features players such as Garmin, Volkswagen, Echomaster, Bosch, Hella, Westfalia, Continental AG, Carit Automotive, Siemens, and Magna. The Trailer Assist System Market is highly competitive, shaped by continuous advancements in automotive safety and driver assistance technologies. Companies compete on innovation, focusing on improving camera accuracy, ultrasonic sensors, and algorithm efficiency to deliver seamless trailer maneuvering. Integration of these systems into both passenger vehicles and commercial fleets has become a key differentiator, with emphasis on ease of use and reliability. The market also sees strong momentum from aftermarket solutions, which allow retrofitting of older vehicles with advanced assist functions. Competition extends to pricing strategies, regional expansion, and compliance with regulatory standards that encourage adoption of advanced driver assistance systems. Overall, the market thrives on balancing cost, performance, and technological sophistication to capture growing demand.
Recent Developments
- In September 2024, Kodiak Robotics selected Wabash National's Trailers as a Service (TaaS) to optimize autonomous fleet operations. The partnership provides fully maintained trailers and managed care services, supporting Kodiak's high maintenance standards while advancing autonomous long-haul trucking capabilities and operational reliability.
- In October 2024, Nissan announced plans to launch affordable V2G technology in select electric vehicles by 2026. This system will allow EV owners to use stored electricity in car batteries to power homes or sell energy back to the grid, aiming to reduce annual EV charging costs by up to 50% and decrease net CO2 emissions from charging by 30% per year for the average UK household.
- In September 2023, Volta Trucks, a commercial vehicle manufacturer and services provider, signed a partnership with Spryker. In this regard, Volta Trucks aims to simplify truck ownership and accelerate the transition to an all-electric fleet through its innovative TaaS offering.
- In August 2023, Webfleet, Bridgestone fleet management solution, announced a strategic partnership with VEV, an e-fleet solutions provider, to boost the commercial Electric Vehicle (EV) transition. VEV provides a comprehensive fleet solution, helping commercial fleets build a robust fleet management system.
Report Coverage
The research report offers an in-depth analysis based on Component, Vehicle Type, Technology Level and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow steadily with rising adoption of driver assistance systems.
- Automakers will integrate trailer assist features in more mid-range and premium vehicles.
- Sensor and camera innovations will improve accuracy and reduce system errors.
- Software upgrades will enable faster trailer recognition and smoother maneuvering.
- Demand from commercial fleets will expand as logistics prioritize safety and efficiency.
- Aftermarket solutions will gain traction in regions with older vehicle bases.
- Regulatory support for advanced safety technologies will accelerate system adoption.
- Rising consumer awareness of towing safety will strengthen market penetration.
- Integration with electric and connected vehicles will create new opportunities.
- Emerging markets in Asia-Pacific and Latin America will drive long-term growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Trailer Assist System Market, and what is its projected size in 2032?
Which Trailer Assist System Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Trailer Assist System Market?
Who are the leading companies in the Trailer Assist System Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Trailer Assist System Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Trailer Assist System Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 144.3 million → 2032: USD 344.7 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Trailer Assist System Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Trailer Assist System Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Trailer Assist System Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Trailer Assist System Market Drivers
- 3.3 Trailer Assist System Market Restraints & Challenges
- 3.4 Trailer Assist System Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Trailer Assist System Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Trailer Assist System Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Trailer Assist System category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Trailer Assist System Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Trailer Assist System Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Trailer Assist System market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Trailer Assist System Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Trailer Assist System Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Trailer Assist System Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Trailer Assist System (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Trailer Assist System Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Trailer Assist System Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Trailer Assist System Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Trailer Assist System Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Trailer Assist System Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Trailer Assist System Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Trailer Assist System Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Trailer Assist System Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Trailer Assist System Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
