
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Transplant Diagnostics Market Size 2024 | USD 5980 million |
| Transplant Diagnostics Market, CAGR | 7.3% |
| Transplant Diagnostics Market Size 2032 | USD 10507.48 million |
Market Overview:
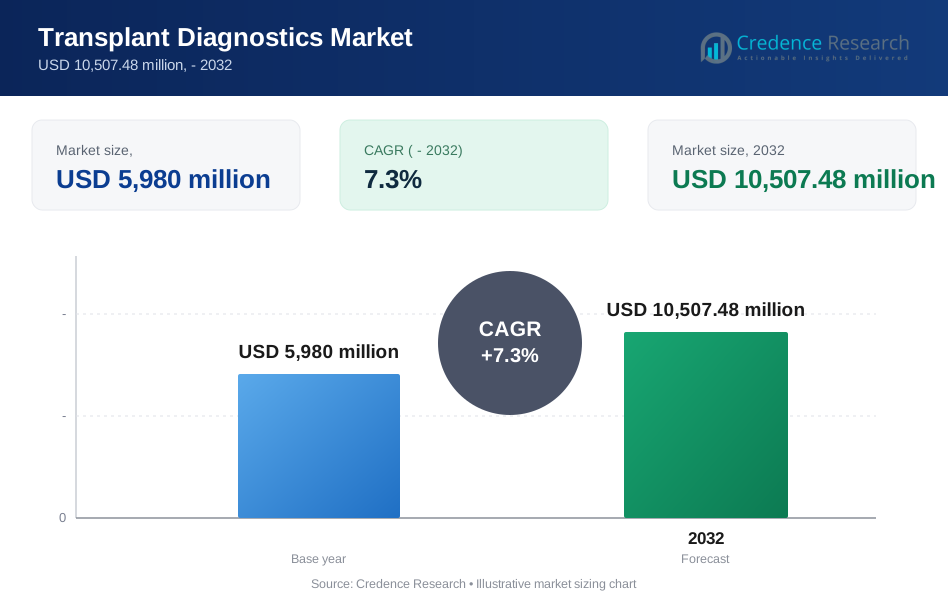
The Transplant Diagnostics Market is projected to grow from USD 5980 million in 2024 to an estimated USD 10507.48 million by 2032, with a compound annual growth rate (CAGR) of 7.3% from 2024 to 2032.
The primary drivers fueling growth in the transplant diagnostics market include the increased rate of organ transplants globally and advancements in diagnostic tools that aid in compatibility matching and post-transplant monitoring. Rising awareness about organ donation and an increase in the availability of transplant diagnostic products, especially in molecular assays, has further encouraged market growth. Moreover, as immune system incompatibility remains a critical challenge in transplants, the demand for highly accurate diagnostic tests is rising. Innovations in next-generation sequencing (NGS) and PCR-based methods have notably enhanced diagnostic accuracy and reliability. The ongoing research in biomarkers to predict transplant rejection risk also underscores the market’s potential, attracting both public and private investment.
Regionally, North America holds the largest share in the transplant diagnostics market, primarily due to the region's advanced healthcare infrastructure, higher rate of organ transplants, and robust funding in transplant-related research. Europe follows, driven by government initiatives promoting organ donation and enhanced diagnostic technologies. The Asia-Pacific region is expected to exhibit the highest growth rate during the forecast period due to the increasing prevalence of chronic diseases, rising healthcare expenditures, and improving healthcare infrastructure in countries like China and India. Furthermore, the presence of unmet medical needs and the growing focus on healthcare expansion in emerging economies are projected to offer lucrative opportunities for market players in the Asia-Pacific region.
Market Drivers:
Increasing Organ Transplantation Rates Worldwide:
The rising global incidence of chronic diseases such as kidney, liver, and heart conditions has led to an increase in organ transplantation procedures. For instance, in 2022, there were approximately 157,494 solid organ transplants reported globally. As more patients reach end-stage disease conditions, the demand for organ transplants has surged, subsequently driving the need for accurate transplant diagnostics. Effective diagnostic tools are essential in both pre- and post-transplant phases, helping medical teams assess donor-recipient compatibility, prevent immune rejection, and monitor organ health over time. This consistent rise in transplant procedures globally is a key factor propelling the transplant diagnostics market forward, creating sustained demand for innovative diagnostic products and services.
Advancements in Molecular and Genomic Technologies:
Significant advancements in molecular and genomic technologies have profoundly impacted the transplant diagnostics market. Technologies like next-generation sequencing (NGS) and polymerase chain reaction (PCR) have made it possible to detect genetic compatibility with heightened precision, ensuring a greater likelihood of transplant success. For instance, single-cell RNA sequencing (scRNA-seq) provides comprehensive genetic information at the individual cell level, which is crucial for understanding alloimmune responses in grafts. NGS, in particular, has allowed for faster, more detailed assessments of both donor and recipient tissue, reducing the risk of rejection and improving long-term outcomes. As these technologies continue to evolve, they enable laboratories and healthcare providers to conduct faster, more accurate analyses, which is critical in the fast-paced and complex environment of organ transplantation.
Increasing Awareness and Government Initiatives Supporting Organ Donation:
Government bodies and non-profit organizations worldwide have implemented a range of awareness campaigns and incentives to encourage organ donation. These efforts aim to address the significant gap between organ demand and availability, which remains a major challenge in many countries. As a result, the overall pool of available organs for transplantation has been expanding, with a corresponding rise in demand for transplant diagnostics. Additionally, some governments are investing in the development of diagnostic infrastructure, such as funding for laboratories and research initiatives. These efforts are contributing to a more robust transplant ecosystem, supporting the growth of the transplant diagnostics market by increasing both the availability of organs and the demand for high-quality diagnostic services.
Rising Investment in Healthcare Infrastructure and Research:
The transplant diagnostics market benefits greatly from the global trend of rising investment in healthcare infrastructure and R&D initiatives. Both public and private sectors are investing in the development of cutting-edge diagnostic solutions that support organ transplantation. This financial support enables the discovery of new biomarkers, the development of improved diagnostic assays, and the enhancement of existing diagnostic platforms. As healthcare systems continue to evolve and modernize, especially in emerging economies, the demand for accurate and efficient diagnostic tools becomes increasingly critical. This investment fosters innovation in transplant diagnostics, encouraging market growth and positioning advanced diagnostic products as an essential part of transplant care. The expansion of healthcare facilities and laboratories in developing regions also ensures greater access to transplant diagnostics, allowing the market to serve a broader population and further solidify its growth trajectory.
Market Trends:
Shift Towards Molecular Diagnostics and Genomic Testing:
The transplant diagnostics market is experiencing a significant shift toward molecular diagnostics and genomic testing, which offer enhanced precision and rapid results compared to traditional methods. For example, companies like Illumina and Thermo Fisher Scientific are leading the way with their NGS platforms, which allow for detailed genomic insights, facilitating better matching between donors and recipients. Technologies such as next-generation sequencing (NGS), polymerase chain reaction (PCR), and human leukocyte antigen (HLA) typing allow for detailed genomic insights, facilitating better matching between donors and recipients. The demand for these technologies is growing as healthcare providers prioritize diagnostic accuracy and time-sensitive decision-making in transplant procedures. As these techniques become more accessible and cost-effective, their adoption is expected to increase, further driving growth in the transplant diagnostics sector.
Increasing Focus on Non-Invasive Testing:
The development of non-invasive testing methods is another trend gaining traction within the transplant diagnostics market. Traditional biopsy-based diagnostics, while effective, can be invasive and carry associated risks for transplant patients. In response, the industry is advancing non-invasive methods such as cell-free DNA (cfDNA) testing, which allows for the detection of donor-derived cfDNA in the bloodstream to monitor for early signs of organ rejection. Non-invasive testing offers the benefits of less patient discomfort, reduced risk of complications, and more frequent monitoring opportunities, which are particularly advantageous in post-transplant care. The rising demand for non-invasive diagnostic options is encouraging further research and development in this area.
Growing Integration of Artificial Intelligence in Diagnostics:
Artificial intelligence (AI) is increasingly being integrated into transplant diagnostics to enhance the speed and accuracy of testing processes. For instance, AI-driven platforms, such as those developed by IBM Watson Health, assist in data analysis, streamline matching processes, and identify patterns that may predict organ rejection or compatibility issues more effectively. AI-driven platforms can assist in data analysis, streamline matching processes, and identify patterns that may predict organ rejection or compatibility issues more effectively. These systems can process vast datasets rapidly, providing insights that support clinical decision-making in real time. The incorporation of AI in diagnostic procedures not only improves the efficiency of diagnostics but also contributes to better patient outcomes by enabling proactive management of transplant complications. The growing role of AI reflects a broader trend in healthcare toward digital transformation and data-driven decision-making.
Rising Adoption of Biomarker-Based Diagnostic Assays:
The adoption of biomarker-based diagnostic assays is on the rise as researchers and clinicians seek more reliable indicators for assessing immune compatibility and monitoring for signs of organ rejection. Biomarkers provide valuable information regarding the state of the immune response and organ health, enabling personalized patient management. Innovations in biomarker research have led to the development of assays that can detect subtle immunological changes, allowing for early intervention and improved transplant success rates. The increased focus on biomarker-based diagnostics aligns with the demand for precision medicine and targeted approaches in healthcare, establishing this as a growing trend within the transplant diagnostics market. As biomarker assays become more sophisticated, their clinical utility in monitoring and predicting transplant outcomes will likely continue to expand, fueling further growth in this sector.
Market Restraints and Challenges:
High Costs of Advanced Diagnostic Technologies:
One of the primary challenges in the transplant diagnostics market is the high cost associated with advanced diagnostic technologies, including next-generation sequencing (NGS) and polymerase chain reaction (PCR) tests. While these molecular diagnostic tools offer superior accuracy and speed, their implementation often requires significant financial investment in equipment, skilled personnel, and infrastructure. This can be particularly burdensome for smaller healthcare facilities and those in developing regions, limiting accessibility to these advanced diagnostic methods. The cost barrier can deter widespread adoption, affecting market growth and the availability of high-quality diagnostics for all patients in need of transplants.
Lack of Skilled Professionals and Technical Expertise:
The transplant diagnostics market faces a critical shortage of skilled professionals who can operate sophisticated diagnostic equipment and interpret complex data from advanced assays. These diagnostic methods often require specialized training, and the limited availability of trained personnel, especially in rural and underserved areas, poses a challenge for expanding the market. Without adequate technical expertise, healthcare providers may struggle to adopt and integrate new diagnostic technologies effectively, which impacts both the quality of care and the market's growth potential.
Regulatory and Ethical Challenges in Transplantation:
The market for transplant diagnostics is also influenced by strict regulatory frameworks and ethical considerations surrounding organ donation and transplantation. Regulatory bodies impose rigorous standards for diagnostic devices and assays, which can delay the approval and market entry of new diagnostic products. Additionally, ethical challenges related to organ donation, such as concerns around organ trafficking and equitable access to transplants, further complicate the landscape. These regulatory and ethical hurdles add layers of complexity for market players and can impact the pace of innovation and adoption of new diagnostics in transplant medicine.
Market Segmentation Analysis:
The transplant diagnostics market is segmented by screening type, technique, application, product & services, and end-user, each contributing uniquely to market dynamics.
By screening category, pre-transplant diagnostics play a crucial role in compatibility testing and risk assessment, ensuring successful transplants, while post-transplant diagnostics support monitoring for early rejection and complications, enhancing long-term outcomes.
By technique, molecular assays, such as PCR and next-generation sequencing (NGS), dominate due to their high precision in genetic compatibility testing. Non-molecular assays, including serological and tissue typing, continue to hold a significant market share, especially in routine testing and simpler settings where molecular methods may not be feasible.
By application, solid organ transplantation remains the primary focus, with kidney, liver, heart, lungs, pancreas, and small bowel transplants as key segments. Kidney transplantation leads due to its high prevalence, followed by liver and heart transplants. Stem cell transplantation is also witnessing steady growth, supported by advancements in compatibility testing that are vital for immune acceptance.
By product & services segment includes reagents and consumables, which are essential for consistent testing, instruments for diagnostic procedures, and software & services for data management and analytical support. Reagents and consumables account for the largest share, given their recurrent use in diagnostics.
By End-user segmentation highlights hospitals and transplant centers as the primary users due to their comprehensive transplant services, followed by research laboratories, which drive innovation and advanced testing, and other facilities that support diagnostic needs in varying capacities.
Segmentation:
By Screening
- Pre-transplant Diagnostics
- Post-transplant Diagnostics
By Technique
- Molecular Assay
- Non-molecular Assay
- Application
- Solid Organ Transplantation
- Kidney
- Liver
- Heart
- Lungs
- Pancreas
- Small Bowel
- Stem Cell Transplantation
By Product & Services
- Reagents & Consumables
- Instruments
- Software & Services
By End-user
- Hospital and Transplant Center
- Research Laboratories
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the global transplant diagnostics market, accounting for approximately 40-45% of the total market. This dominant position is driven by a well-established healthcare infrastructure, high organ transplant rates, and significant investments in research and development. The United States, in particular, leads the region due to advanced diagnostic facilities, supportive healthcare policies, and a strong emphasis on organ donation programs. Additionally, government initiatives like the National Institutes of Health (NIH) funding for transplant-related research encourage advancements in transplant diagnostics. Canada also contributes to market growth, driven by its healthcare system’s focus on organ donation and the adoption of advanced diagnostic technologies. Overall, North America's high adoption rate of molecular diagnostics, coupled with a robust regulatory framework, strengthens its leading position.
Europe
Europe holds the second-largest market share, representing around 25-30% of the global transplant diagnostics market. Countries like Germany, France, the UK, and Spain drive growth in this region, backed by a high number of organ transplants and well-developed healthcare policies supporting transplant procedures. The European Union’s initiatives promoting organ donation and the harmonization of organ transplant regulations across member countries facilitate market expansion. The region has a growing demand for advanced diagnostics, particularly for post-transplant monitoring and molecular assays. Furthermore, rising investments in healthcare technology and increasing awareness about organ transplantation are expected to boost Europe’s transplant diagnostics market over the coming years.
Asia-Pacific
The Asia-Pacific region is expected to witness the highest growth rate in the transplant diagnostics market, holding approximately 15-20% of the global market share. Factors such as the rising prevalence of chronic diseases, expanding healthcare infrastructure, and increasing awareness about organ donation are driving growth. Countries like China, India, and Japan are leading this growth, with large patient populations and government initiatives supporting healthcare development. For example, the Chinese government’s efforts to reform and regulate organ donation have increased transplant rates in the country, consequently fueling demand for diagnostic solutions. In India, improving healthcare access and rising healthcare spending contribute to the market's expansion. The region's focus on affordable, accessible diagnostic technologies supports the adoption of both molecular and non-molecular assays, particularly in emerging markets.
Latin America
Latin America accounts for a smaller yet steadily growing portion of the market, estimated at around 5-7% of the global share. Countries like Brazil and Mexico drive regional growth, supported by efforts to improve healthcare infrastructure and organ donation awareness programs. Brazil, in particular, has one of the largest public healthcare systems, facilitating access to transplant diagnostics. However, limited access to advanced diagnostic technology and financial constraints pose challenges for market expansion. Nonetheless, the region’s gradual adoption of advanced diagnostics and supportive government initiatives suggest potential for growth.
Middle East and Africa
The Middle East and Africa hold the smallest share of the transplant diagnostics market, approximately 3-5%. Growth in this region is hindered by limited healthcare infrastructure, low transplant rates, and financial constraints. However, countries like Saudi Arabia, South Africa, and the UAE are making strides in improving healthcare facilities, which is gradually increasing the adoption of transplant diagnostics. Government efforts to improve organ donation systems and increase transplant facilities are expected to create growth opportunities in this region over time.
Key Player Analysis:
- Abbott
- BD (Becton, Dickinson and Company)
- Bio-Rad Laboratories, Inc.
- Bruker
- Hoffmann La-Roche Ltd
- Illumina, Inc.
- Omixon Inc.
- QIAGEN
- Thermo Fisher Scientific, Inc.
- Werfen (Immucor, Inc.)
Competitive Analysis:
The transplant diagnostics market is highly competitive, with key players focusing on technological advancements, strategic collaborations, and geographic expansions to strengthen their market presence. Leading companies, including Thermo Fisher Scientific, Bio-Rad Laboratories, Illumina, and Qiagen, dominate the market through innovative product offerings in molecular assays, next-generation sequencing (NGS), and polymerase chain reaction (PCR) techniques. These players invest heavily in research and development to introduce precise and rapid diagnostics for pre- and post-transplant screenings, which are critical in improving patient outcomes and reducing rejection rates. Strategic collaborations and acquisitions further bolster market positioning, allowing companies to broaden their diagnostic portfolios and reach emerging markets. Smaller players and new entrants are increasingly focusing on developing cost-effective and user-friendly diagnostic solutions, catering to unmet needs in emerging economies. The market’s competitive landscape is characterized by a focus on innovation and adaptability, with an emphasis on providing accurate and accessible diagnostic solutions globally.
Recent Developments:
- In May 2024, Thermo Fisher launched the CXCL10 testing service tailored for kidney transplant patients, designed to detect the CXCL10 chemokine faster than traditional tests.
- In February 2023, BD secured FDA approval for its BD Onclarity HPV assay, expanding its presence in the serology testing segment. Bio-Rad Laboratories received AQAC International and AFNOR approval for its iQ-Check kits in March 2023, highlighting its commitment to quality standards in diagnostics.
- In January 2022, Hoffmann-La Roche Ltd. introduced Cobas Infinity Edge, a cloud-based point-of-care platform, enabling healthcare practitioners to manage patient data seamlessly through advanced technology. This platform has allowed Roche to diversify its diagnostic offerings in healthcare.
- In August 2022, QIAGEN published a validation study in the Journal of Molecular Pathology for its clinical decision support software, QIAGEN Clinical Insight Interpret One (QCI Interpret One). Conducted independently by Genomics Quality Assessment (GenQA), the study confirmed the software’s high concordance with expert variant classification, strengthening its clinical credibility.
- In March 2022, Immucor Inc. also expanded its transplant diagnostics portfolio with two new products, reinforcing its commitment to advancing histocompatibility in transfusion and transplantation diagnostics.
Market Concentration & Characteristics:
The transplant diagnostics market is moderately concentrated, with a few leading companies holding a substantial share due to their strong portfolios in advanced diagnostic technologies such as molecular assays, next-generation sequencing (NGS), and polymerase chain reaction (PCR). Key players like Thermo Fisher Scientific, Bio-Rad Laboratories, and Qiagen dominate, supported by significant R&D investments, regulatory expertise, and global distribution networks. However, smaller firms and new entrants contribute by developing cost-effective, user-friendly diagnostics, especially targeting emerging markets. Market characteristics include high regulatory scrutiny due to the critical nature of transplant diagnostics in patient outcomes and long-term transplant success. Additionally, the market is marked by continuous innovation, driven by the need for precision, speed, and non-invasive testing methods. Strategic collaborations, mergers, and acquisitions are common as companies strive to expand their offerings and strengthen their competitive positioning, resulting in a dynamic and evolving landscape in the transplant diagnostics field.
Report Coverage:
The research report offers an in-depth analysis based on By Screening, By Technique, By Product & Services and By End-user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The transplant diagnostics market is expected to experience steady growth, driven by rising organ transplant rates worldwide.
- Advances in molecular diagnostics, particularly next-generation sequencing (NGS) and polymerase chain reaction (PCR), will enhance precision and adoption.
- Increasing demand for non-invasive diagnostic methods, like cell-free DNA (cfDNA) testing, will expand post-transplant monitoring options.
- Artificial intelligence integration in diagnostics will improve data analysis and prediction capabilities, optimizing patient outcomes.
- Biomarker research will continue to progress, supporting personalized diagnostics and early detection of transplant complications.
- Asia-Pacific is anticipated to witness the highest growth rate, fueled by healthcare expansion and rising chronic disease prevalence.
- Regulatory support and government incentives for organ donation programs will further stimulate market growth.
- Collaborations between research institutions and biotech companies are expected to accelerate innovation and clinical adoption.
- Cost reduction efforts in advanced diagnostic technologies will make high-quality testing more accessible globally.
- Expansion of cloud-based platforms and digital solutions will facilitate data management, enabling real-time insights and remote monitoring.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size for transplant diagnostics by 2032?
What is the expected CAGR for the transplant diagnostics market from 2024 to 2032?
What are the key drivers of growth in this market?
Which region holds the largest market share?
What challenges does the transplant diagnostics market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Transplant Diagnostics Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Transplant Diagnostics Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 5,980 million → 2032: USD 10,507.48 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Transplant Diagnostics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Transplant Diagnostics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Transplant Diagnostics Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Transplant Diagnostics Market Drivers
- 3.3 Transplant Diagnostics Market Restraints & Challenges
- 3.4 Transplant Diagnostics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Transplant Diagnostics Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Transplant Diagnostics Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Transplant Diagnostics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Transplant Diagnostics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Transplant Diagnostics Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Transplant Diagnostics market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Transplant Diagnostics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Transplant Diagnostics Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Transplant Diagnostics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Transplant Diagnostics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Transplant Diagnostics Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Transplant Diagnostics Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Transplant Diagnostics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Transplant Diagnostics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Transplant Diagnostics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Transplant Diagnostics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Transplant Diagnostics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Transplant Diagnostics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Transplant Diagnostics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
