
Market Overview
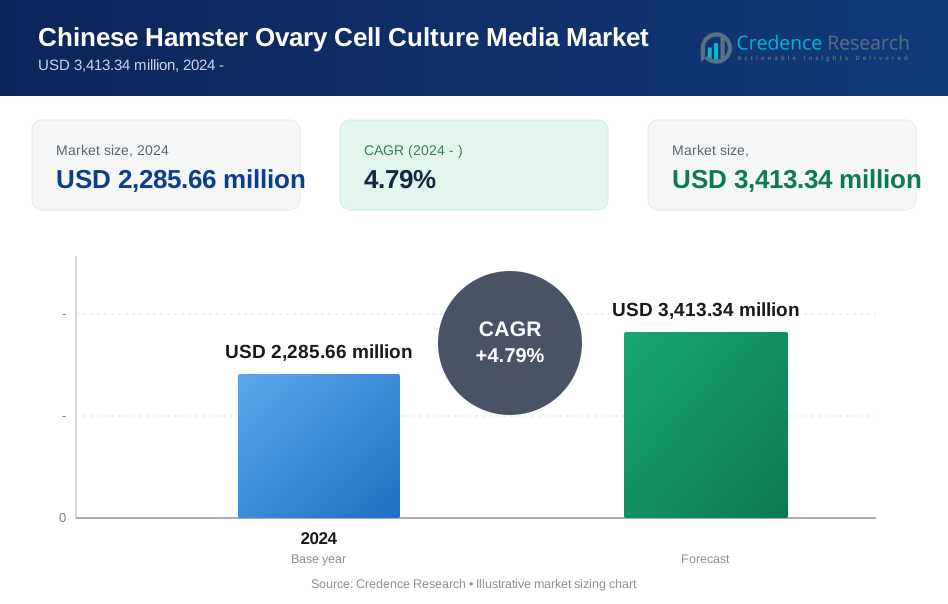
The Global Chinese Hamster Ovary (CHO) Cell Culture Media market size was valued at USD 1,704.12 million in 2018, growing to USD 2,285.66 million in 2024, and is anticipated to reach USD 3,413.34 million by 2032, at a CAGR of 4.79% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Chinese Hamster Ovary (CHO) Cell Culture Media Market Size 2024 | USD 2,285.66 Million |
| Chinese Hamster Ovary (CHO) Cell Culture Media Market, CAGR | 4.79% |
| Chinese Hamster Ovary (CHO) Cell Culture Media Market Size 2032 | USD 3,413.34 Million |
The global CHO cell culture media market is led by major players including Sartorius AG, Thermo Fisher Scientific, Lonza Group Ltd., Sigma Aldrich Corporation, and Cytiva, supported by regional firms such as Procell, QuaCell Biotechnology, Eminence BioPharm, and ExCell Bio. These companies dominate through advanced serum-free and chemically defined media portfolios, strong bioprocessing expertise, and strategic collaborations with biopharmaceutical manufacturers. North America accounted for over 40% of the market share in 2024, making it the leading region due to established biologics production and robust R&D infrastructure. Europe followed with nearly 28% share, driven by biosimilars growth and stringent quality standards, while Asia Pacific emerged as the fastest-growing region with 19% share, supported by expanding manufacturing hubs and rising biologics demand.
Market Insights
- The Global Chinese Hamster Ovary (CHO) Cell Culture Media market was valued at USD 1,704.12 million in 2018, reached USD 2,285.66 million in 2024, and is projected to hit USD 3,413.34 million by 2032, growing at a CAGR of 4.79%.
- Rising demand for monoclonal antibodies, which held over 50% application share in 2024, is a key driver supported by expanding biologics pipelines and strong regulatory acceptance of CHO cell platforms.
- Market trends highlight the shift toward chemically defined media, dominating with more than 55% share in 2024, along with growing adoption of single-use bioprocessing and biosimilars across Asia Pacific.
- The competitive landscape is led by Sartorius, Thermo Fisher, Lonza, Sigma Aldrich, and Cytiva, alongside regional players like Procell and QuaCell Biotechnology, focusing on innovation, acquisitions, and localized solutions.
- Regionally, North America led with over 40% share in 2024, followed by Europe at 28% and Asia Pacific at 19%, with Asia Pacific recording the fastest CAGR of 6.5%.
Market Segmentation Analysis:
By Type of Medium
The Chinese Hamster Ovary (CHO) cell culture media market is segmented into serum-based, serum-free, and chemically defined media. In 2024, chemically defined medium dominated with over 55% market share, supported by rising demand for consistency, reproducibility, and regulatory compliance in large-scale biomanufacturing. Serum-free media followed, gaining traction in biologics production due to reduced contamination risk and lower variability, while serum-based media held a smaller share, mainly in early-stage R&D. The shift toward chemically defined formulations is driven by increasing monoclonal antibody demand and stringent quality standards across global biopharmaceutical pipelines.
- For instance, Sartorius partners with Merck KGaA, which offers the EX-CELL Advanced CHO Fed-batch Medium, a product available since before 2023. Using an optimized process—which includes the medium, feeds, and the specific cell line—it is possible to achieve monoclonal antibody titers above 10 g/L in commercial bioreactors.
By Cell Type
Among CHO cell types, CHO-K1 cells accounted for more than 45% of market share in 2024, driven by their widespread use in recombinant protein expression and adaptability in diverse culture conditions. CHO-S cells followed closely with strong adoption in high-yield suspension cultures, particularly for large-scale antibody manufacturing. The “others” category, including engineered and hybrid cell lines, represented a niche but growing segment as innovation in gene editing accelerates. The dominance of CHO-K1 stems from its well-established regulatory acceptance, robust productivity, and extensive use in commercial-scale biopharmaceutical production.
- For instance, in 2022, Lonza invested in and delivered on growth projects aimed at improving manufacturing capacity and efficiency for therapeutic antibodies and other biologics across its global network of GMP facilities.
By Application
The application landscape is led by monoclonal antibody production, which captured over 50% share in 2024, supported by surging demand for targeted therapies in oncology and autoimmune diseases. Recombinant protein production ranked second, benefiting from expanding applications in enzyme replacement and therapeutic proteins. Vaccine production contributed significantly with growing adoption of CHO platforms in modern vaccine development, particularly for viral and protein-based vaccines. The “others” segment, covering research and diagnostics, maintained a smaller share. The dominance of monoclonal antibody applications reflects industry focus on biologics innovation and strong pipeline approvals worldwide.

Key Growth Drivers
Rising Demand for Monoclonal Antibodies
The growing global burden of cancer, autoimmune, and infectious diseases has significantly increased demand for monoclonal antibodies (mAbs). In 2024, over 50% of CHO cell culture media applications were linked to mAb production, making it the dominant driver. CHO cells are the preferred platform due to their high protein yield, scalability, and regulatory acceptance. Expanding mAb pipelines across oncology and immunology have accelerated investment in advanced media formulations. Biopharmaceutical companies are adopting chemically defined media to enhance production efficiency, reduce variability, and ensure compliance with stringent quality standards, fueling long-term market expansion.
- For instance, Lonza reported achieving antibody titers exceeding 10 g/L using its GS Xceed® CHO platform in commercial-scale fed-batch processes during 2023.
Expansion of Biopharmaceutical Manufacturing Capacity
Global pharmaceutical firms are investing heavily in biomanufacturing facilities, with a strong focus on Asia-Pacific and North America. CHO cell culture media forms the backbone of these large-scale production plants, particularly for biologics and biosimilars. In 2024, global biologics accounted for nearly 35% of new drug approvals, reflecting rapid adoption. Rising government funding, tax incentives, and favorable regulatory frameworks support industry growth. Continuous investment in single-use bioprocessing and automation enhances demand for media tailored to scalable, high-density cultures. These expansions are creating sustained requirements for advanced, cost-effective, and regulatory-compliant CHO media formulations.
- For instance, Samsung Biologics expanded its Songdo facility in 2023, reaching 604,000 liters of total CHO-based bioreactor capacity, the largest globally for biologics manufacturing.
Shift Toward Serum-Free and Chemically Defined Media
The transition from serum-based to serum-free and chemically defined media is a major growth driver. Chemically defined media accounted for more than 55% market share in 2024, reflecting the industry’s focus on safety, reproducibility, and regulatory compliance. Biopharmaceutical manufacturers prefer serum-free and chemically defined formulations as they reduce contamination risks, eliminate variability, and support high-yield production. Regulatory agencies increasingly recommend serum-free processes, accelerating adoption. This shift is particularly crucial for monoclonal antibody and vaccine production, where scalability and purity are essential. As demand for consistent and cost-efficient manufacturing grows, adoption of chemically defined CHO media will continue to strengthen globally.
Key Trends & Opportunities
Adoption of Single-Use Bioprocessing Systems
Single-use technologies are increasingly shaping CHO cell culture media demand. Disposable bioreactors and modular systems minimize contamination risks, reduce cleaning costs, and enable faster turnaround in multi-product facilities. Media formulations designed for single-use compatibility support flexible and efficient production of biologics, vaccines, and biosimilars. With rising demand for small-batch and personalized therapies, single-use systems allow scalability without major infrastructure investments. This trend presents opportunities for media manufacturers to develop specialized solutions optimized for high-density CHO cell cultures, supporting both commercial-scale and contract manufacturing growth.
- For instance, Thermo Fisher Scientific’s HyPerforma DynaDrive single-use bioreactor reached 5,000 L capacity in 2021, enabling high-density CHO cultures with antibody titers over 12 g/L.
Growth in Biosimilars and Personalized Medicine
The expiration of biologics patents is driving rapid biosimilar adoption, particularly in Europe and Asia-Pacific. CHO cell culture media plays a critical role in ensuring biosimilar quality and consistency, fueling steady demand. At the same time, advancements in personalized medicine and gene therapy are expanding applications for CHO-based platforms. Tailored therapies for oncology and rare diseases require precise, reproducible, and high-quality culture media. Companies developing customized formulations for biosimilar and personalized drug pipelines are well-positioned to capture growth opportunities. The trend highlights CHO media’s importance in the evolving biopharmaceutical landscape.
- For instance, WuXi Biologics utilized Chinese Hamster Ovary (CHO)-based systems for its manufacturing operations in 2023. The company has developed advanced fed-batch platforms, such as WuXiUI™, which have achieved very high yields, with some bispecific antibodies demonstrating yields as high as 25 g/L.
Key Challenges
High Production Costs and Price Sensitivity
Despite strong growth potential, CHO cell culture media remains expensive due to complex formulation requirements, stringent regulatory compliance, and advanced manufacturing technologies. Small and mid-sized biotech firms face challenges in adopting premium chemically defined media, leading to high price sensitivity. In addition, fluctuating raw material costs and supply chain dependencies increase operational expenses. These factors can limit market penetration, especially in cost-sensitive regions such as Latin America and parts of Asia. Reducing costs while maintaining quality and consistency is a major challenge for manufacturers.
Stringent Regulatory and Quality Compliance
CHO cell-based biologics must meet strict regulatory standards set by agencies like the FDA and EMA. Ensuring that media formulations comply with evolving safety, purity, and reproducibility requirements is a complex task. Variability in raw materials or contamination risks can delay approvals and affect production timelines. Manufacturers face challenges in scaling production without compromising regulatory compliance. Moreover, the industry’s shift toward chemically defined and serum-free media requires continuous R&D investment to meet these expectations. Adhering to strict compliance frameworks while innovating adds both cost and time pressures on global market players.

Regional Analysis
North America
North America held the largest share of the CHO cell culture media market, accounting for over 40% in 2024 with revenues of USD 991.54 million, up from USD 746.99 million in 2018. The market is projected to reach USD 1,484.84 million by 2032, growing at a CAGR of 4.8%. Strong biopharmaceutical R&D, advanced manufacturing capacity, and the dominance of monoclonal antibody production drive regional leadership. The presence of key players and favorable regulatory support ensures North America maintains its top position in the global landscape throughout the forecast period.
Europe
Europe represented the second-largest market, contributing nearly 28% share in 2024 with revenues of USD 630.86 million, rising from USD 487.78 million in 2018. By 2032, the region is expected to reach USD 887.49 million, advancing at a CAGR of 4.0%. Europe’s strong biosimilars industry, robust clinical trial activity, and government-backed biologics initiatives support steady growth. The region’s emphasis on serum-free and chemically defined media aligns with strict regulatory compliance. With rising healthcare investments and expanding biologics pipelines, Europe continues to hold a significant role in the global CHO media market.
Asia Pacific
Asia Pacific is the fastest-growing region, projected at a CAGR of 6.5%. The market expanded from USD 317.37 million in 2018 to USD 462.55 million in 2024, and is anticipated to reach USD 785.10 million by 2032, representing about 19% of the global share in 2024. Rapid growth is fueled by expanding biopharmaceutical manufacturing hubs in China, India, and South Korea, along with supportive government funding and rising biologics demand. Increasing investment in vaccine production and biosimilars further boosts adoption of advanced CHO cell culture media across the region.
Latin America
Latin America accounted for around 5% of the market in 2024, generating USD 106.87 million, up from USD 80.68 million in 2018. The market is expected to reach USD 141.30 million by 2032, advancing at a CAGR of 3.2%. Brazil and Mexico remain the key contributors, with increasing focus on domestic biologics production and clinical trials. Despite limited infrastructure compared to developed regions, rising healthcare expenditure and demand for affordable biosimilars are gradually driving adoption of serum-free and chemically defined CHO media, providing a steady growth path for the regional market.
Middle East
The Middle East CHO cell culture media market was valued at USD 54.46 million in 2024, up from USD 44.71 million in 2018, and is projected to reach USD 67.68 million by 2032, growing at a CAGR of 2.4%. The region contributed close to 3% of the global share in 2024, led by the UAE and Saudi Arabia. Growth is supported by rising investments in healthcare infrastructure and biotechnology research. However, limited large-scale manufacturing capacity and dependency on imports restrain faster expansion, keeping growth moderate compared to leading regions.
Africa
Africa represented a smaller share, contributing around 2% of the market in 2024, with revenues of USD 39.38 million, up from USD 26.60 million in 2018. The market is expected to reach USD 46.93 million by 2032, reflecting a CAGR of 1.8%. Growth is primarily concentrated in South Africa due to stronger healthcare systems and increasing collaborations in vaccine research. However, limited R&D infrastructure and reliance on imported CHO media constrain broader adoption. While the market size remains modest, international initiatives in public health and biotechnology could gradually open opportunities for regional growth.

Market Segmentations:
By Type of Medium
- Serum-Based Medium
- Serum-Free Medium
- Chemically Defined Medium
By Cell Type
- CHO-K1
- CHO-S
- Others
By Application
- Monoclonal Antibody Production
- Recombinant Protein Production
- Vaccine Production
- Others
By End User
- Biopharmaceutical Companies
- Biotechnology Companies
- Research Laboratories
- Academic Institutes
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The global CHO cell culture media market is highly competitive, with a mix of established bioprocess solution providers and emerging regional players. Leading companies such as Sartorius AG, Thermo Fisher Scientific, Lonza Group Ltd., Sigma Aldrich Corporation, and Cytiva dominate the market through broad product portfolios, strong R&D investments, and global distribution networks. These players emphasize innovation in serum-free and chemically defined media to meet regulatory compliance and scalability demands. Regional specialists like Procell, QuaCell Biotechnology, and Eminence BioPharm strengthen market penetration in Asia through cost-effective and tailored solutions. Companies are also pursuing partnerships, capacity expansions, and acquisitions to enhance their competitive position. For instance, expanding single-use bioprocess technologies and biosimilar production pipelines has increased collaboration between media suppliers and biopharmaceutical firms. The competitive environment is defined by a focus on product differentiation, regulatory alignment, and sustainable manufacturing practices to address rising global demand for monoclonal antibodies, recombinant proteins, and vaccines.
Key Player Analysis
- Sartorius AG
- Thermo Fisher Scientific
- Lonza Group Ltd.
- Sigma Aldrich Corporation
- Cytiva (formerly GE Healthcare Life Sciences)
- OPM Biosciences
- Procell
- QuaCell Biotechnology
- Eminence BioPharm
- STEMCELL Technologies
- ExCell Bio
- Medium Bank
Recent Developments
- In July 2023, Merck KGaA announced an expansion plan for its Lenexa, Kansas facility, adding 9,100 square meters of laboratory space and increasing production capacity for cell culture media. This strategic initiative supports the company's goal of strengthening its supply chain to meet the growing demand for Chinese hamster ovary (CHO) cell culture platforms
- In February 2023, the European Investment Bank (EIB) secured an USD 19.42 million agreement with Estonia-based biotech firm Icosagen AS. The funding aims to enhance Icosagen's production facility and advance its research and development technology platforms, reinforcing its role as a leader in biotechnology innovation
- In February 2022, Sartorius AG finalized the acquisition of Novasep's business, strengthening its chromatography portfolio. This acquisition includes systems designed for small biomolecules, such as oligonucleotides, peptides, and insulin, along with innovative platforms for continuous biopharmaceutical production, expanding Sartorius' capabilities in the biopharma sector
Report Coverage
The research report offers an in-depth analysis based on Type of Medium, Cell Type, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to witness steady growth throughout the forecast period.
- Monoclonal antibody production will remain the leading application due to high therapeutic demand.
- Chemically defined media will gain further dominance as the industry seeks greater consistency.
- Serum-free media adoption will increase as manufacturers focus on contamination-free processes.
- CHO-K1 cells will continue to lead among cell types due to wide regulatory acceptance.
- Asia Pacific will emerge as the fastest-growing region with strong biosimilar development.
- North America will retain its leadership supported by advanced biologics pipelines and R&D strength.
- Europe will maintain a strong position through biosimilar approvals and strict compliance standards.
- Leading companies will expand through strategic partnerships, acquisitions, and product innovation.
- Growth in vaccines, recombinant proteins, and personalized therapies will drive new opportunities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Chinese Hamster Ovary (CHO) Cell Culture Media market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Chinese Hamster Ovary (CHO) Cell Culture Media market projected to grow between 2025 and 2032?
Which Global Chinese Hamster Ovary (CHO) Cell Culture Media market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Chinese Hamster Ovary (CHO) Cell Culture Media market?
Who are the leading companies in the Global Chinese Hamster Ovary (CHO) Cell Culture Media market?
Which region commanded the largest share of the Global Chinese Hamster Ovary (CHO) Cell Culture Media market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Chinese Hamster Ovary Cell Culture Media Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Chinese Hamster Ovary Cell Culture Media Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 2,285.66 million → forecast year: USD 3,413.34 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Chinese Hamster Ovary Cell Culture Media Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Chinese Hamster Ovary Cell Culture Media Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Chinese Hamster Ovary Cell Culture Media Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Chinese Hamster Ovary Cell Culture Media Market Drivers
- 3.3 Chinese Hamster Ovary Cell Culture Media Market Restraints & Challenges
- 3.4 Chinese Hamster Ovary Cell Culture Media Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Chinese Hamster Ovary Cell Culture Media Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Chinese Hamster Ovary Cell Culture Media Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Chinese Hamster Ovary Cell Culture Media category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Chinese Hamster Ovary Cell Culture Media Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Chinese Hamster Ovary Cell Culture Media Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Chinese Hamster Ovary Cell Culture Media market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Chinese Hamster Ovary Cell Culture Media Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Chinese Hamster Ovary Cell Culture Media Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Chinese Hamster Ovary Cell Culture Media Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Chinese Hamster Ovary Cell Culture Media (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Chinese Hamster Ovary Cell Culture Media Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Chinese Hamster Ovary Cell Culture Media Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Chinese Hamster Ovary Cell Culture Media Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Chinese Hamster Ovary Cell Culture Media Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Chinese Hamster Ovary Cell Culture Media Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Chinese Hamster Ovary Cell Culture Media Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Chinese Hamster Ovary Cell Culture Media Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Chinese Hamster Ovary Cell Culture Media Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Chinese Hamster Ovary Cell Culture Media Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
