
Market Overview
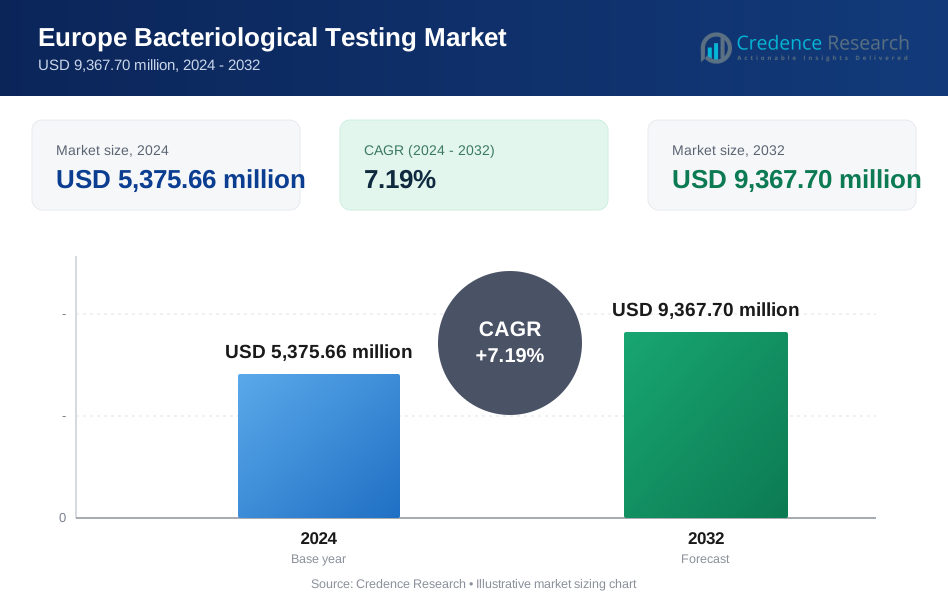
Europe Bacteriological Testing Market size was valued at USD 3,659.94 million in 2018, rising to USD 5,375.66 million in 2024, and is anticipated to reach USD 9,367.70 million by 2032, at a CAGR of 7.19% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Bacteriological Testing Market Size 2024 | USD 5,375.66 Million |
| Europe Bacteriological Testing Market, CAGR | 7.19% |
| Europe Bacteriological Testing Market Size 2032 | USD 9,367.70 Million |
The Europe Bacteriological Testing Market is shaped by the presence of global leaders and regional specialists offering diverse testing solutions. Major players such as Merieux NutriSciences, Thermo Fisher Scientific Inc., Eurofins, Agilent Technologies Inc., Bio-Rad Laboratories Inc., Intertek, Merck KGaA, Neogen Corporation, BioMerieux, Symbio Labs, Alfa Chemistry, and Vimta Labs strengthen their positions through advanced instruments, rapid test kits, and compliance-driven services. These companies focus on innovation, automation, and strategic collaborations to expand their reach across industries, including food, pharmaceuticals, and water testing. Germany emerges as the leading region with a 24% market share in 2024, supported by its strong food processing base, advanced laboratory infrastructure, and strict regulatory enforcement driving demand for bacteriological testing solutions.
Market Insights
- The Europe Bacteriological Testing Market was USD 3,659.94 million in 2018, reached USD 5,375.66 million in 2024, and is projected at USD 9,367.70 million by 2032, growing at 7.19%.
- Instruments dominate by product with 42% share in 2024, supported by automation demand, while test kits hold 34% and consumable reagents account for 24%.
- Salmonella leads by bacteria with 30% share, followed by coliform at 25% and Listeria at 18%, with Legionella, Campylobacter, and others comprising the rest.
- Rapid testing holds 63% share in 2024, driven by speed, accuracy, and compliance, while traditional testing accounts for 37% within regulated labs and research centers.
- Germany leads regionally with 24% share, followed by the U.K. at 17% and France at 15%, while Italy, Spain, Russia, and the Rest of Europe collectively strengthen the market.
Market Segment Insights
By Product
Instruments hold the largest share of the Europe Bacteriological Testing Market, accounting for 42% of revenue in 2024. Their dominance is supported by growing demand for advanced analytical equipment, automation in laboratories, and higher accuracy requirements across food and pharmaceutical testing. Test kits represent around 34% share, driven by rising adoption in rapid detection processes, particularly in field testing and smaller laboratories. Consumable reagents capture 24%, reflecting steady demand as recurring supplies in routine bacteriological testing workflows.
- For instance, Thermo Fisher Scientific launched the SureTect Listeria monocytogenes PCR Assay, expanding its portfolio of validated molecular detection kits for food safety testing.
By Bacteria
Salmonella leads the segment with a 30% market share in 2024, as regulatory agencies and industries focus on controlling foodborne pathogens. Coliform testing follows with 25%, due to its critical role in water and beverage safety monitoring. Listeria accounts for 18%, supported by stringent guidelines in dairy and ready-to-eat food industries. Legionella represents 12%, as Europe enforces strict monitoring in water systems and healthcare facilities. Campylobacter holds 10%, while others collectively contribute 5%, covering broader pathogen surveillance needs.
- For instance, Bio-Rad Laboratories launched its iQ-Check Salmonella II PCR kit in Europe, validated under ISO 16140-2 for improved detection in food samples.
By Technology
Rapid testing dominates the technology segment with 63% share in 2024, fueled by demand for faster turnaround, improved accuracy, and compliance with stringent food safety standards. The adoption of rapid methods is rising across food, water, and pharmaceutical industries, driven by the need for real-time detection. Traditional methods maintain a 37% share, as they remain standard in regulated laboratories and research institutions where detailed analysis and validation are required.

Key Growth Drivers
Rising Food Safety Regulations
Stringent food safety regulations across Europe remain a major driver for the bacteriological testing market. Agencies such as EFSA and national regulators enforce strict monitoring of foodborne pathogens like Salmonella and Listeria. This regulatory pressure compels food producers and processors to adopt advanced testing solutions. Growing consumer awareness about contamination risks further boosts compliance-driven testing. As a result, both large and mid-scale manufacturers increase investments in routine bacteriological testing, ensuring consistent demand for instruments, test kits, and reagents across the region.
- For instance, Eurofins Scientific launched a new Listeria Whole Genome Sequencing (WGS) service in Germany to help food companies meet EFSA’s stricter monitoring requirements for pathogen tracing.
Expanding Pharmaceutical and Healthcare Applications
The pharmaceutical sector contributes significantly to market growth by requiring bacteriological testing to ensure drug safety and sterility. Rising production of biologics, injectable drugs, and vaccines drives demand for accurate microbial contamination detection methods. Healthcare institutions also prioritize water and environmental monitoring to prevent hospital-acquired infections. With Europe’s strong pharmaceutical base, particularly in Germany, Switzerland, and the UK, investments in microbiological quality control continue to rise. This broader application spectrum strengthens market adoption of both traditional and rapid bacteriological testing technologies.
- For instance, Merck KGaA launched the Milliflex® Rapid System 2.0, a rapid automated solution for microbial testing in pharmaceuticals, helping companies reduce sterility testing time from 14 days to less than 5 days.
Technological Advancements in Rapid Testing
Advancements in rapid testing technologies drive market expansion by improving speed, sensitivity, and ease of use. Techniques such as PCR, immunoassays, and biosensors are increasingly adopted to deliver real-time results, helping industries reduce downtime and product recalls. Automation in sample preparation and analysis also improves efficiency in high-volume testing labs. In addition, growing R&D investments from key players enhance product availability and innovation. These technological improvements align with industry needs for reliable, cost-effective, and regulatory-compliant bacteriological testing solutions across Europe’s food, pharma, and water sectors.
Key Trends & Opportunities
Adoption of Digital and Automated Solutions
Automation and digitalization are emerging as strong trends in Europe’s bacteriological testing market. Automated sample handling and advanced data analytics reduce human error while increasing throughput. Integration of AI-based platforms with laboratory information management systems (LIMS) is creating opportunities for faster decision-making and predictive contamination control. The shift toward smart laboratories supports compliance with strict quality standards and offers cost savings. These advancements create a long-term opportunity for testing service providers and technology developers to expand across Europe’s industrial and healthcare sectors.
- For instance, bioMérieux launched the MAST ISOPLEX® Bacteria Detect, an automated molecular test platform in Europe designed to accelerate pathogen identification in food and clinical labs, supporting digital workflows for faster results.
Growing Demand for Environmental and Water Testing
The rising focus on environmental safety and water quality monitoring creates fresh opportunities for bacteriological testing in Europe. Governments and municipalities are enforcing strict monitoring of Legionella and coliform bacteria to reduce risks in public water supplies. Industries such as hospitality and healthcare are increasing investment in water testing solutions to ensure safety and compliance. With climate change influencing microbial growth in water systems, demand for reliable and rapid testing is expected to accelerate. This trend offers significant expansion prospects for technology providers and testing laboratories.
- For instance, IDEXX Laboratories launched the Legionella EZ Test in Europe, a culture-based detection method designed to provide results in seven days, supporting compliance with EU and national guidelines.
Key Challenges
High Cost of Advanced Testing Technologies
The cost of advanced bacteriological testing technologies remains a barrier to wider adoption, especially among small and medium enterprises. Instruments, automated systems, and molecular testing kits involve high upfront investments and recurring expenses. Smaller food processors and water testing labs often rely on traditional methods due to budget constraints. This cost challenge limits penetration of rapid technologies in some segments, slowing overall market growth. Addressing affordability through cost-effective solutions and partnerships remains a key challenge for market players in Europe.
Regulatory Complexity Across Countries
Regulatory frameworks for bacteriological testing vary across European countries, creating compliance challenges for businesses. While EU-level agencies provide overarching guidelines, each member state enforces its own standards and testing requirements. Companies operating in multiple countries face increased costs and operational complexity to align with diverse rules. Inconsistencies in approval timelines and certification processes also delay the adoption of new technologies. This fragmented regulatory environment adds uncertainty for industry participants and hinders the smooth expansion of bacteriological testing practices across Europe.
Skilled Workforce Shortages
A shortage of skilled professionals in microbiology and laboratory testing poses a challenge for the bacteriological testing market. Operating advanced instruments and interpreting rapid test results require specialized expertise, which many smaller labs struggle to maintain. The growing reliance on automation and digital systems further increases the need for technically trained staff. Without adequate workforce development, laboratories face delays and errors in testing processes. This talent gap may restrict the efficient implementation of advanced testing solutions across industries in Europe.

Regional Analysis
Germany
Germany leads the Europe Bacteriological Testing Market with a 24% share in 2024. Strong presence of food and beverage processing industries drives consistent demand for bacteriological testing. The country enforces strict food safety regulations, particularly for Salmonella and Listeria control, which supports the adoption of advanced testing technologies. Pharmaceutical and healthcare sectors also contribute to market growth through high investment in microbial quality control. Germany’s well-established laboratory infrastructure enables rapid adoption of automation and molecular testing. It remains a key hub for technological innovation and market expansion.
U.K.
The U.K. holds a 17% share in the Europe Bacteriological Testing Market. Growing consumer awareness and strict oversight from the Food Standards Agency encourage widespread adoption of bacteriological testing solutions. The market benefits from increasing demand in water quality monitoring, driven by Legionella control regulations. The country’s strong healthcare and pharmaceutical base ensures continuous use of rapid testing systems. Investments in R&D strengthen opportunities for automation and advanced diagnostic methods. It continues to expand due to demand from both industrial and public health sectors.
France
France accounts for 15% of the Europe Bacteriological Testing Market. Its strong dairy and meat processing sectors generate steady demand for bacteriological testing across the supply chain. Regulatory emphasis on foodborne pathogens such as Listeria and Salmonella supports the widespread adoption of both traditional and rapid testing methods. Pharmaceutical manufacturing and healthcare institutions also contribute to market revenues. Local laboratories increasingly adopt advanced kits and reagents for high-volume testing. It remains an important contributor to regional market growth with ongoing investments in testing infrastructure.
Italy
Italy captures a 12% share in the Europe Bacteriological Testing Market. The market is supported by demand from food and beverage exports, particularly in dairy and meat products, which require extensive microbial testing. National regulations aligned with EU standards drive the adoption of both rapid and traditional technologies. Water safety monitoring also creates additional demand, especially for Legionella detection. Increasing modernization of laboratories enhances the uptake of automated instruments. It continues to strengthen its position with growing reliance on bacteriological testing in export-driven sectors.
Spain
Spain holds a 10% share in the Europe Bacteriological Testing Market. The food industry’s focus on seafood and meat processing creates significant demand for microbial safety testing. National enforcement of hygiene regulations ensures routine bacteriological testing across food facilities. Pharmaceutical and cosmetics industries also use advanced methods to ensure product safety. Rapid urbanization and tourism further push the demand for water quality monitoring. It remains an expanding market segment with rising adoption of cost-effective rapid testing solutions.
Russia
Russia accounts for 9% of the Europe Bacteriological Testing Market. Demand is driven by stricter enforcement of food safety standards and growing awareness of microbial contamination risks. Local industries increasingly adopt rapid technologies, supported by international partnerships and equipment imports. Pharmaceutical and healthcare applications also expand, requiring consistent bacteriological monitoring. Investments in laboratory modernization support the adoption of advanced instruments. It demonstrates steady growth with rising demand for comprehensive testing solutions across multiple sectors.
Rest of Europe
The Rest of Europe contributes 13% to the Europe Bacteriological Testing Market. Countries in Eastern and Northern Europe are expanding their testing capacities with support from EU-funded food safety programs. The demand for bacteriological testing grows in food exports, water management, and healthcare services. Increasing focus on compliance with EU guidelines encourages broader adoption of advanced testing technologies. Local laboratories gradually integrate rapid testing methods to meet regulatory standards. It strengthens overall regional demand by bridging gaps in testing infrastructure across smaller markets.

Market Segmentations:
By Product
- Instruments
- Test Kits
- Consumable Reagents
By Bacteria
- Salmonella
- Coliform
- Listeria
- Legionella
- Campylobacter
- Others
By Technology
- Traditional
- Rapid
By End User
- Food and Beverage
- Pharmaceutical
- Cosmetics & Personal Care
- Water
- Others
By Region
- Germany
- U.K.
- France
- Italy
- Spain
- Russia
- Rest of Europe
Competitive Landscape
The competitive landscape of the Europe Bacteriological Testing Market is defined by the presence of global leaders and specialized regional players offering a wide portfolio of instruments, test kits, and reagents. Companies such as Merieux NutriSciences, Thermo Fisher Scientific, Eurofins, and Agilent Technologies maintain strong positions through advanced technologies and extensive laboratory networks. Bio-Rad Laboratories, Merck KGaA, and BioMerieux focus on innovation in rapid testing solutions, supported by continuous R&D investments. Intertek and Neogen Corporation strengthen their reach through compliance-driven testing services across food, pharmaceutical, and water industries. Emerging participants such as Vimta Labs, Symbio Labs, and Alfa Chemistry contribute to competitive diversity by offering specialized solutions and localized expertise. The market remains competitive with frequent product launches, strategic collaborations, and acquisitions aimed at expanding service capabilities and geographic reach. It reflects a balanced mix of multinational corporations and niche providers, fostering innovation and ensuring broad coverage across industries.
Key Players
- Merieux NutriSciences Corporation
- Thermo Fisher Scientific Inc.
- Eurofins
- Agilent Technologies Inc.
- Bio-Rad Laboratories Inc.
- Intertek
- Merck KGaA
- Neogen Corporation
- Vimta Labs
- BioMerieux
- Symbio Labs
- Alfa Chemistry
- Other Key Players
Recent Developments
- In September 2025, Sysmex Europe entered into a strategic partnership with Kuehne+Nagel to enhance distribution and healthcare sector operations in Europe for bacteriological and related testing solutions.
- In September 2025, LuminUltra acquired France-based GL Biocontrol to strengthen its microbial testing presence in Europe.
- In February 2025, bioMérieux launched GENE-UP® TY per, a PCR solution to accelerate Listeria monocytogenes root cause analysis in the food sector.
Report Coverage
The research report offers an in-depth analysis based on Product, Bacteria, Technology, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for bacteriological testing will grow with stricter European food safety regulations.
- Rapid testing technologies will gain wider adoption across food, pharma, and water sectors.
- Automation and digital integration will enhance efficiency in laboratory operations.
- Pharmaceutical manufacturing will drive steady demand for microbial contamination testing.
- Water testing for Legionella and coliform bacteria will expand with public safety initiatives.
- Advanced test kits will become more common in small and mid-sized laboratories.
- Environmental monitoring will emerge as a key area of application for testing solutions.
- Regional laboratories will modernize infrastructure to meet EU compliance standards.
- Strategic partnerships and acquisitions will strengthen market presence of leading players.
- Growing consumer awareness of hygiene will sustain investment in bacteriological testing solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Europe Bacteriological Testing Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Europe Bacteriological Testing Market projected to grow between 2025 and 2032?
Which Europe Bacteriological Testing Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Europe Bacteriological Testing Market?
Who are the leading companies in the Europe Bacteriological Testing Market?
Which region commanded the largest share of the Europe Bacteriological Testing Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe Bacteriological Testing Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Europe Bacteriological Testing Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5,375.66 million → 2032: USD 9,367.70 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe Bacteriological Testing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe Bacteriological Testing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe Bacteriological Testing Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Europe Bacteriological Testing Market Drivers
- 3.3 Europe Bacteriological Testing Market Restraints & Challenges
- 3.4 Europe Bacteriological Testing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe Bacteriological Testing Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe Bacteriological Testing Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe Bacteriological Testing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe Bacteriological Testing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Europe Bacteriological Testing Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Europe Bacteriological Testing market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe Bacteriological Testing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe Bacteriological Testing Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Europe Bacteriological Testing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe Bacteriological Testing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Europe Bacteriological Testing Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Europe Bacteriological Testing Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Europe Bacteriological Testing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Europe Bacteriological Testing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Europe Bacteriological Testing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Europe Bacteriological Testing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Europe Bacteriological Testing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Europe Bacteriological Testing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Europe Bacteriological Testing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
