
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Turbine Inlet Cooling Systems Market Size 2024 | USD 4595 million |
| Turbine Inlet Cooling Systems Market, CAGR | 4.7% |
| Turbine Inlet Cooling Systems Market Size 2032 | USD 6635.27 million |
Market Overview:
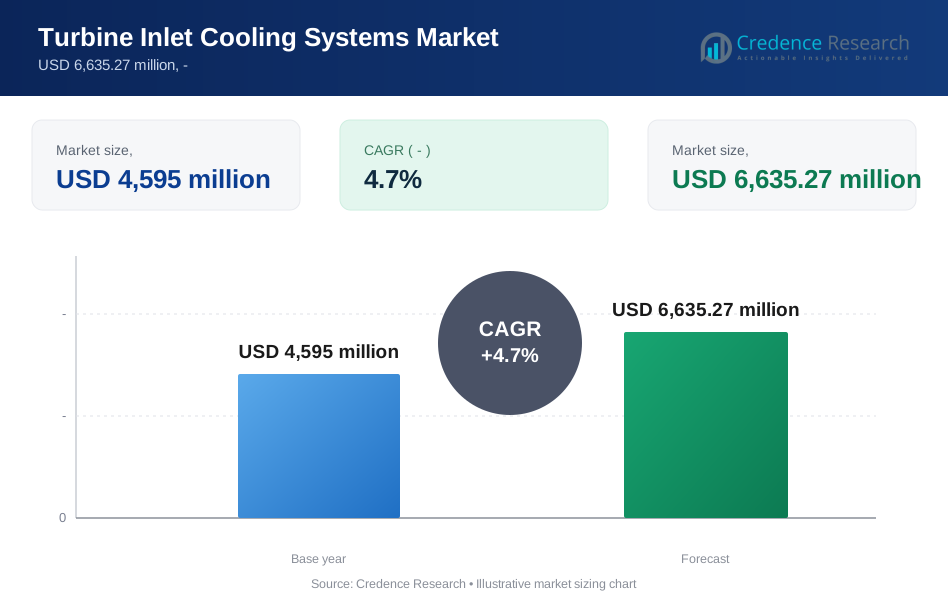
The Turbine Inlet Cooling Systems Market is projected to grow from USD 4595 million in 2024 to an estimated USD 6635.27 million by 2032, with a compound annual growth rate (CAGR) of 4.7% from 2024 to 2032.
Several key drivers are influencing the turbine inlet cooling systems market. One primary factor is the rising global energy demand, which places pressure on power generation facilities to operate more efficiently. By cooling the air entering gas turbines, these systems help improve power output and efficiency, particularly in regions with high ambient temperatures. The increased use of renewable energy sources such as solar and wind also complements turbine inlet cooling systems, as these systems can ensure stable energy supply during peak demand periods. Additionally, technological advancements in turbine cooling technologies, such as mechanical chillers, evaporative cooling, and fogging systems, have made these solutions more cost-effective and efficient. Government regulations promoting energy efficiency and environmental sustainability further support the adoption of turbine inlet cooling systems in various industrial sectors.
Regionally, North America, Europe, Asia Pacific, and the Middle East and Africa represent key markets for turbine inlet cooling systems. North America holds a significant share due to the high prevalence of gas turbine power plants, particularly in the United States, where temperature fluctuations demand efficient cooling systems. In Europe, stringent environmental regulations and investments in energy efficiency are key drivers for the market. The Asia Pacific region is expected to witness the fastest growth, driven by rapid industrialization, increasing energy demand, and ongoing investments in the power generation sector in countries like China and India. The Middle East and Africa, with its high ambient temperatures and growing need for energy efficiency, also represent a promising market for turbine inlet cooling systems.
Market Drivers:
Rising Global Energy Demand:
One of the primary drivers of the turbine inlet cooling systems market is the growing global demand for energy. As populations and industries continue to expand, especially in emerging economies, the need for reliable and efficient energy generation has become increasingly critical. Power plants, particularly those relying on gas turbines, face the challenge of operating efficiently under variable temperature conditions. For instance, according to the Turbine Inlet Cooling Association, turbine inlet cooling systems can boost the capacity and efficiency of combustion turbine systems during hot weather, making them a resilient and sustainable option for energy providers. Turbine inlet cooling systems offer a solution by cooling the air entering the turbines, which enhances power output and efficiency, particularly in hot climates. This helps to meet rising energy demands without requiring the construction of additional power generation infrastructure, making it a cost-effective option for energy providers.
Need for Improved Power Plant Efficiency:
Turbine inlet cooling systems play a crucial role in enhancing the efficiency of gas turbines. In regions with high ambient temperatures, the performance of gas turbines can significantly decrease due to the lower density of hot air. By cooling the inlet air, these systems increase air density, allowing the turbine to generate more power with the same fuel input. For instance, GE Vernova reports that their inlet air-cooling system can increase gross power output by as much as 11 MW under optimal conditions. This improved efficiency is essential for power plants aiming to reduce operational costs while maximizing energy output. The ability to enhance turbine performance, particularly during peak demand periods when energy generation is most crucial, makes turbine inlet cooling systems a valuable asset for power plants across various regions.
Technological Advancements in Cooling Systems:
Technological advancements have further fueled the demand for turbine inlet cooling systems. Innovations in cooling technologies, such as mechanical chillers, evaporative cooling, and fogging systems, have made these systems more efficient, reliable, and cost-effective. These technologies allow power plants to choose the most suitable cooling solution based on their specific needs, environmental conditions, and budget constraints. Additionally, the development of more advanced control systems has enabled operators to optimize the cooling process, reducing energy consumption and operational costs. As a result, the growing availability of cutting-edge turbine cooling solutions is driving their adoption in both new and existing power plants, contributing to market growth.
Government Regulations and Environmental Concerns:
Increasing environmental concerns and government regulations aimed at promoting energy efficiency and reducing carbon emissions have also contributed to the growth of the turbine inlet cooling systems market. Many countries are implementing stringent policies that require power generation facilities to optimize their energy use and minimize environmental impact. Turbine inlet cooling systems help meet these regulatory requirements by enhancing the efficiency of gas turbines, reducing fuel consumption, and lowering emissions. In addition, the integration of renewable energy sources such as solar and wind into the power grid has made energy supply more variable, creating a greater need for stable, efficient power generation solutions. Turbine inlet cooling systems, by improving the reliability and output of gas turbines, help balance energy supply and demand, supporting both regulatory compliance and environmental sustainability.
Market Trends:
Growing Adoption of Renewable Energy Integration:
A notable trend in the turbine inlet cooling systems market is the growing integration of renewable energy sources like solar and wind into power grids. For example, Wind power installations worldwide grew dramatically from 14.86 GW in 2006 to 591 GW in 2018, demonstrating the rapid expansion of renewable energy infrastructure. As renewable energy becomes a larger component of global energy supply, the need for stable and efficient power generation systems has increased. Gas turbines, often used as a reliable backup for renewable energy, can operate more efficiently with turbine inlet cooling systems. These systems help compensate for the variable nature of renewable energy sources by ensuring a steady output during periods of peak demand or when renewable energy generation is insufficient. This trend is driving demand for turbine inlet cooling systems, particularly in regions with large-scale renewable energy installations.
Technological Advancements in Cooling Solutions:
Technological innovation is significantly shaping the turbine inlet cooling systems market. Advanced cooling technologies such as high-efficiency fogging systems, inlet chillers, and hybrid solutions are gaining traction due to their ability to enhance turbine performance more effectively. These systems allow for better adaptability to fluctuating environmental conditions, making them more suitable for diverse climates and operational needs. Additionally, the development of more sophisticated control systems and automation has enabled greater precision in managing the cooling process, which reduces energy consumption and improves the overall efficiency of power generation. For instance, the drive for energy efficiency has led to significant technological innovations in cooling systems. Advanced digital control solutions have been successfully implemented in 14 commercially operating units as of December 2021, proving their effectiveness in real-world applications. This trend towards smarter and more adaptive cooling technologies is expected to boost the adoption of turbine inlet cooling systems globally.
Increasing Focus on Energy Efficiency and Environmental Compliance:
As governments worldwide continue to enforce stricter regulations on energy efficiency and emissions, there is a growing emphasis on optimizing power plant performance. Turbine inlet cooling systems have emerged as a key solution to meet these regulatory demands, as they significantly improve gas turbine efficiency, reduce fuel consumption, and lower greenhouse gas emissions. Power generation companies are increasingly investing in these systems to comply with environmental regulations while maintaining operational efficiency. This focus on sustainability and energy conservation is expected to continue driving the growth of the turbine inlet cooling systems market as more regions adopt stringent emissions standards and energy efficiency guidelines.
Rising Demand in Emerging Economies:
Emerging economies, particularly in Asia-Pacific and the Middle East, are witnessing rapid industrialization and urbanization, leading to a surge in energy demand. As these regions strive to expand their power generation capacities, there is a growing need for efficient technologies that can help maximize energy output without significantly increasing fuel consumption or operational costs. Turbine inlet cooling systems are gaining popularity in these markets due to their ability to enhance the performance of gas turbines in hot and arid climates. The increasing investment in infrastructure development and the expansion of industrial sectors in these regions are key trends driving the demand for turbine inlet cooling systems. As energy demand continues to rise in emerging markets, this trend is expected to significantly contribute to the growth of the global market.
Market Restraints and Challenges:
High Initial Capital Investment:
One of the major restraints in the turbine inlet cooling systems market is the high initial capital investment required for installation. The cost of implementing advanced cooling technologies, such as mechanical chillers or hybrid systems, can be prohibitive for small- to medium-sized power plants or facilities operating on tight budgets. While the long-term benefits of improved efficiency and reduced operational costs are clear, the upfront expense often acts as a barrier to adoption. Many operators may delay or avoid investment in these systems, particularly in regions with fluctuating energy demand or less stringent regulatory environments.
Operational and Maintenance Challenges:
Another challenge facing the turbine inlet cooling systems market is the complexity of maintaining and operating these systems over time. Cooling technologies such as fogging or evaporative cooling systems require regular maintenance to ensure optimal performance. This includes periodic cleaning, monitoring for corrosion, and managing water quality. Failure to maintain these systems properly can result in reduced efficiency, higher operational costs, and even system failures. Additionally, in regions with limited access to skilled technicians or spare parts, maintaining these cooling systems can become a significant challenge, further limiting their adoption.
Weather and Climate Dependency:
The effectiveness of turbine inlet cooling systems is often highly dependent on local weather and climate conditions. In cooler climates, where ambient temperatures rarely reach levels that significantly impact gas turbine performance, the need for cooling systems is less pressing. This limits the market for turbine inlet cooling technologies in certain regions. Moreover, extreme weather conditions, such as high humidity or frequent temperature fluctuations, can diminish the performance of some cooling systems, making them less reliable in specific environments. This climate dependency creates a variable demand for turbine inlet cooling systems, particularly in temperate regions.
Market Segmentation Analysis:
By Technology, the market includes several key solutions such as inlet fogging, evaporative cooling, mechanical chillers, and hybrid systems. Inlet fogging and evaporative cooling are widely used due to their cost-effectiveness and efficiency in increasing air density and power output. Mechanical chillers and absorption cooling systems are preferred in regions with extreme heat, providing higher cooling efficiency. Hybrid systems, which combine different cooling technologies, are gaining popularity for their flexibility and superior performance.
By Component, key products include chillers, inlet coils, pumps, cooling towers, thermal energy storage tanks, and air-cooled heat exchangers. Chillers and cooling towers are crucial components in large-scale installations, while inlet coils and pumps are integral to ensuring the smooth operation of the cooling systems.
By Application, the market is divided into CT (Combined Cycle) plants and industrial applications. CT plants represent the largest application segment due to their high energy demand, while industrial sectors like manufacturing and processing plants also benefit from turbine inlet cooling systems to optimize energy efficiency.
By End-Use, the power generation sector dominates the market, as these systems are critical in improving the efficiency of gas turbines. Other important end-use industries include oil & gas, chemical, petrochemical, and food processing, all of which demand reliable and efficient power generation solutions to support their operations.
Segmentation:
By Technology
- Inlet Fogging
- Chiller System
- Evaporative Cooling
- Mechanical Chillers
- Fogging System
- Wet Compression
- Hybrid System
- Absorption Cooling
By Component
- Chillers
- Inlet Coils
- Pump
- Cooling Tower
- Thermal Energy Storage Tank
- Air Cooled Heat Exchanger
By Application
- CT Plant
- Industrial
By End-Use
- Power Generation
- Oil & Gas
- Chemical
- Petrochemical
- Food Processing
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis:
North America
North America holds a significant share of the global turbine inlet cooling systems market, accounting for approximately 35% of the total market. The region’s dominance can be attributed to the high concentration of gas turbine power plants, particularly in the United States, where fluctuating temperatures, especially during the summer months, necessitate the use of cooling systems to optimize turbine efficiency. Moreover, North America has a well-established energy infrastructure, and increasing investments in upgrading aging power plants drive the demand for turbine inlet cooling systems. The U.S. also leads in adopting advanced cooling technologies such as mechanical chillers and hybrid systems, which offer greater efficiency and adaptability. In Canada, the focus on renewable energy integration has further accelerated the adoption of these systems.
Europe
Europe represents approximately 25% of the turbine inlet cooling systems market. The region's growth is driven by stringent regulations related to energy efficiency and carbon emissions, pushing power generation companies to adopt more efficient technologies. Countries like Germany, the United Kingdom, and France are leading the market, with a strong focus on renewable energy integration and reducing the environmental impact of gas turbine operations. Europe’s climate conditions, with relatively cooler temperatures, reduce the need for turbine inlet cooling systems in certain areas. However, in Southern Europe, where temperatures are higher, there is a growing demand for these systems, especially during peak energy usage periods.
Asia Pacific
The Asia Pacific region is expected to witness the fastest growth in the turbine inlet cooling systems market, currently accounting for around 22% of the market share. Rapid industrialization, urbanization, and increasing energy demand, particularly in countries like China, India, and Southeast Asian nations, are key drivers. The region's hot and humid climate makes it particularly suitable for the adoption of turbine inlet cooling technologies to ensure efficient power generation. Governments in these countries are investing heavily in expanding their energy infrastructure, and the need for reliable power generation technologies is propelling the demand for turbine inlet cooling systems.
Middle East and Africa
The Middle East and Africa region holds approximately 15% of the global market, with high potential for growth due to the region’s extreme climatic conditions and the growing demand for energy. The Middle East, with its hot desert climate, places a significant strain on gas turbines during peak temperatures, making turbine inlet cooling systems essential for maintaining efficient power generation. Countries like Saudi Arabia, the UAE, and Qatar are investing in energy infrastructure, with a focus on improving the efficiency of existing power plants. Africa is also expected to experience growth in this market as energy demand rises in line with industrialization and urban development.
Latin America
Latin America accounts for roughly 8% of the turbine inlet cooling systems market. The region's growing energy needs, driven by industrial expansion and urbanization, have led to increased investments in power generation infrastructure. Brazil, Mexico, and Argentina are the leading countries in adopting turbine inlet cooling systems to enhance the performance of gas turbines in both power generation and industrial sectors. However, economic constraints and political instability in some parts of the region can hinder market growth.
Key Player Analysis:
- American Moistening Company Inc.
- Baltec IES Pty. Ltd.
- Caldwell Energy Company Inc.
- Camfil Power Systems
- Cat Pumps Inc.
- Humifrio S.L.
- Mee Industries Inc.
- Score Energy Limited
- Siemens AG
- Stellar Energy
- UTC Technologies Company
Competitive Analysis:
The turbine inlet cooling systems market is highly competitive, with several key players striving to gain market share by offering advanced and efficient solutions. Major companies like Stellar Energy, Siemens, Johnson Controls, and Mee Industries lead the market, providing a range of technologies such as mechanical chillers, evaporative cooling, and hybrid systems. These companies are focused on innovation, improving system performance, and expanding their product portfolios to meet the growing demand for energy-efficient solutions. Smaller regional players are also emerging, particularly in markets like Asia Pacific and the Middle East, where demand for turbine inlet cooling systems is rapidly increasing. Strategic partnerships, mergers, and acquisitions are common strategies employed by market leaders to strengthen their position and expand their global presence. Additionally, companies are investing in R&D to develop more cost-effective and environmentally friendly technologies to address the evolving needs of the power generation industry.
Recent Developments:
- Stellar Energy announced in January 2024 a $28 million investment to enhance its manufacturing capabilities. The investment includes $20 million for building infrastructure and $8 million for equipment, aiming to triple production capacity in 2024 and achieve a fivefold increase by 2025. As part of this growth strategy, the company acquired the former GE Oil & Gas manufacturing facility at Alliance Florida at Cecil Commerce Center in March 2024, encompassing a 524,271-square-foot main building and an 8,400-square-foot additional facility. The expansion project, which includes site modifications worth $1.14 million, is expected to create 250 new jobs.
Market Concentration & Characteristics:
The turbine inlet cooling systems market exhibits a moderate level of concentration, with a mix of large multinational corporations and smaller regional players. Key players like Stellar Energy, Johnson Controls, and Siemens dominate the market, leveraging their extensive expertise, global reach, and strong financial capabilities to maintain a competitive edge. However, smaller firms and local companies also play a significant role, particularly in emerging markets where the demand for customized and cost-effective solutions is growing. The market is characterized by rapid technological advancements, with innovations in cooling technologies such as hybrid systems and advanced fogging systems gaining traction. The industry is also driven by regulatory pressures for energy efficiency and environmental sustainability, which influences the development of new, more efficient cooling solutions. Additionally, the market is highly dependent on regional climate conditions, with demand particularly strong in areas with hot climates and high energy consumption.
Report Coverage:
The research report offers an in-depth analysis based on By Technology, By Component, By Application and By End-Use. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The turbine inlet cooling systems market is expected to see steady growth due to increasing global energy demand and the need for more efficient power generation.
- Adoption of renewable energy sources will drive demand for turbine cooling systems to stabilize power output in fluctuating grid conditions.
- Technological advancements, such as hybrid cooling systems, will enhance efficiency and adaptability, boosting market expansion.
- The power generation sector will remain the largest end-use segment, driven by the need to optimize gas turbine performance.
- Emerging economies in Asia Pacific and the Middle East will lead market growth due to rapid industrialization and extreme climate conditions.
- Rising environmental regulations and energy efficiency mandates will encourage the adoption of turbine inlet cooling technologies.
- High initial capital costs may continue to challenge market penetration in smaller or cost-sensitive regions.
- Increased investments in energy infrastructure will support long-term market expansion, especially in developing regions.
- The market will see growing competition among global players and regional firms, fostering innovation and pricing pressure.
- Continuous R&D efforts will focus on developing more sustainable and cost-effective cooling solutions to meet evolving industry needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the turbine inlet cooling systems market?
What factors are driving the growth of this market?
Which regions are leading the market for turbine inlet cooling systems?
What are the main challenges facing the turbine inlet cooling systems market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Turbine Inlet Cooling Systems Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Turbine Inlet Cooling Systems Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 4,595 million → forecast year: USD 6,635.27 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Turbine Inlet Cooling Systems Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Turbine Inlet Cooling Systems Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Turbine Inlet Cooling Systems Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Turbine Inlet Cooling Systems Market Drivers
- 3.3 Turbine Inlet Cooling Systems Market Restraints & Challenges
- 3.4 Turbine Inlet Cooling Systems Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Turbine Inlet Cooling Systems Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Turbine Inlet Cooling Systems Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Turbine Inlet Cooling Systems category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Turbine Inlet Cooling Systems Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Turbine Inlet Cooling Systems Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Turbine Inlet Cooling Systems market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Turbine Inlet Cooling Systems Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Turbine Inlet Cooling Systems Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Turbine Inlet Cooling Systems Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Turbine Inlet Cooling Systems (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Turbine Inlet Cooling Systems Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Turbine Inlet Cooling Systems Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Turbine Inlet Cooling Systems Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Turbine Inlet Cooling Systems Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Turbine Inlet Cooling Systems Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Turbine Inlet Cooling Systems Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Turbine Inlet Cooling Systems Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Turbine Inlet Cooling Systems Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Turbine Inlet Cooling Systems Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
