
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| UAE Plastic Welding Equipment Market Size 2024 | USD 24.87 million |
| UAE Plastic Welding Equipment Market, CAGR | 4.80% |
| UAE Plastic Welding Equipment Market Size 2032 | USD 36.20 million |
Market Overview
UAE Plastic Welding Equipment market size was valued at USD 24.87 million in 2024 and is anticipated to reach USD 36.20 million by 2032, at a CAGR of 4.80% during the forecast period (2024-2032).
The UAE plastic welding equipment market is driven by the increasing demand for high-performance, durable plastic components across key industries such as automotive, construction, and manufacturing. The rise in industrial automation and the growing use of plastics for lightweight and cost-effective solutions are key factors fueling market growth. Additionally, the adoption of advanced welding technologies, including laser welding and ultrasonic welding, is enhancing efficiency, precision, and product quality. The focus on sustainability and reducing material waste is further accelerating the demand for plastic welding equipment, as these technologies offer cleaner and more reliable methods. Moreover, the expanding infrastructure development in the UAE, along with a growing manufacturing sector, is creating significant opportunities for plastic welding equipment. The trend towards automation and the need for energy-efficient, high-quality production processes are expected to continue shaping the market's growth trajectory in the coming years.
The UAE plastic welding equipment market is driven by key players with a strong regional presence, including Leister Technologies AG, RITMO S.p.A., Emerson Electric Co., and Herrmann Ultraschalltechnik GmbH & Co. KG. These companies offer a diverse range of products, such as manual, semi-automatic, and fully automatic welding systems, catering to the growing demand across industries like automotive, packaging, and electronics. Geographically, Dubai leads the market due to its commercial prominence, followed by Abu Dhabi, which benefits from significant infrastructure development. Sharjah also plays a key role with its growing manufacturing sector, while smaller emirates like Ajman, Fujairah, and Ras Al Khaimah contribute to the expanding demand for plastic welding equipment. The presence of major global and regional manufacturers in these areas supports market growth, with increasing investments in automation and technology driving the evolution of plastic welding solutions across the UAE.
Market Insights
- The UAE plastic welding equipment market was valued at USD 24.87 million in 2024 and is expected to reach USD 36.20 million by 2032, growing at a CAGR of 4.80% during the forecast period.
- The global plastic welding equipment market was valued at USD 11,340.00 million in 2024 and is projected to reach USD 19,842.36 million by 2032, growing at a CAGR of 7.24% from 2024 to 2032.
- Increasing demand for lightweight and durable plastic components in industries such as automotive, construction, and electronics is a major market driver.
- Advancements in welding technologies, including laser and ultrasonic welding, are contributing to higher efficiency and precision in manufacturing processes.
- The trend towards automation in manufacturing, with a shift towards fully automated welding systems, is significantly shaping the market.
- High initial investment costs and the need for specialized skills are key restraints limiting market growth.
- The UAE’s key markets, including Dubai and Abu Dhabi, are driving demand, supported by the growth of manufacturing and infrastructure projects.
- Competitive players like Leister Technologies, Emerson Electric, and Herrmann Ultraschalltechnik are leading the market with advanced solutions.
Report Scope
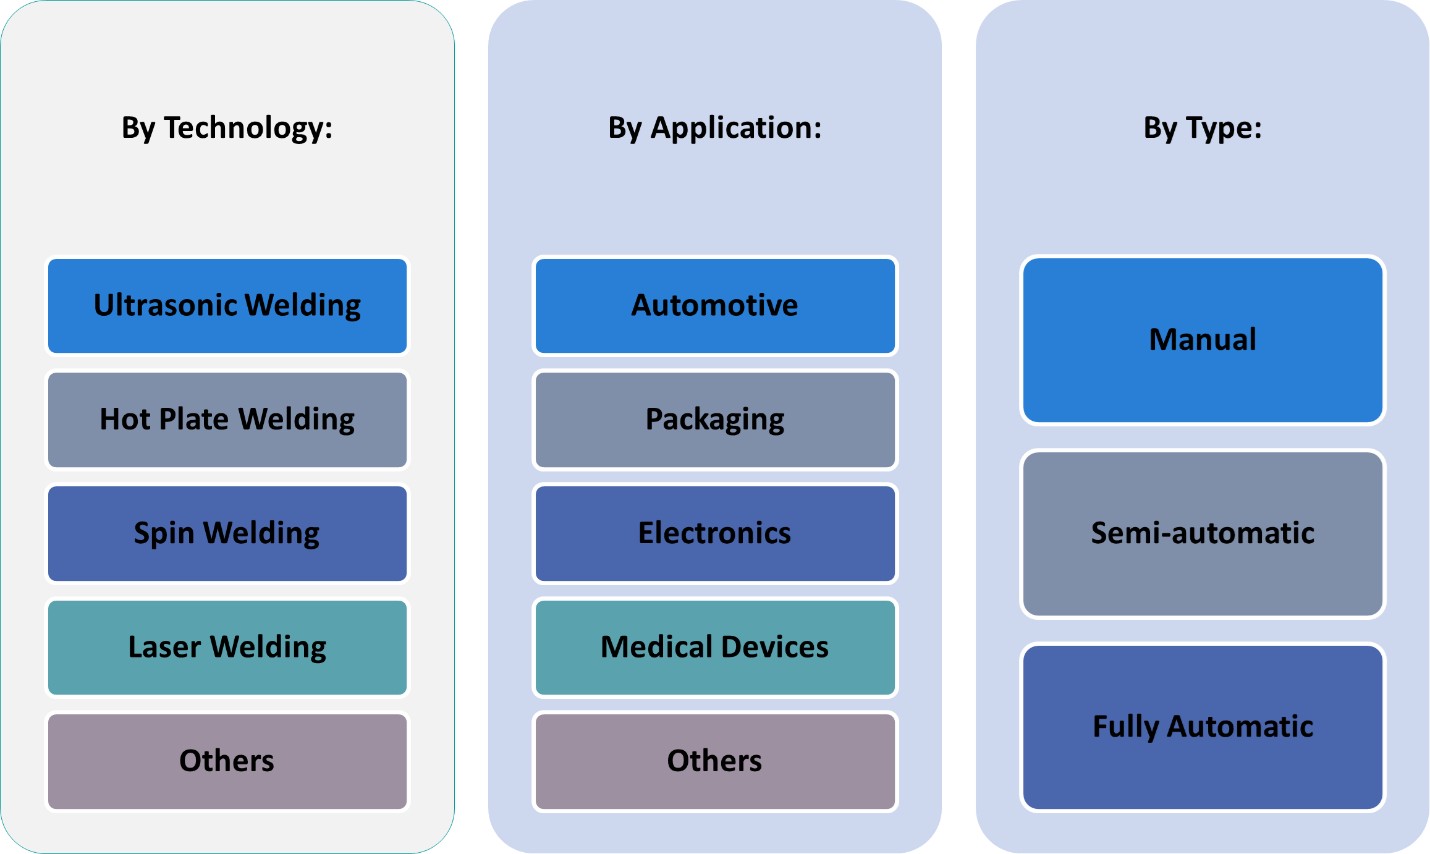
This report segments the UAE Plastic Welding Equipment Market as follows:
Market Drivers
Growing Demand Across Key Industries
The demand for plastic welding equipment in the UAE is driven by the increasing reliance on plastic components across several industries, including automotive, construction, and manufacturing. For instance, the UAE’s automotive sector has embraced plastic welding technologies to produce lightweight vehicle components that enhance fuel efficiency and reduce emissions. As industries seek cost-effective, durable, and lightweight solutions, the use of plastics has surged. The automotive sector, in particular, benefits from plastic components due to their weight-saving characteristics, which help improve fuel efficiency and reduce emissions. The construction industry also increasingly uses plastic materials for pipes, fittings, and insulation, which require welding technologies for assembly. As these industries grow, the need for advanced plastic welding solutions continues to expand, providing significant opportunities for market growth in the region.
Advancements in Welding Technologies
Technological advancements in plastic welding equipment are playing a crucial role in the market’s growth. For instance, UAE-based manufacturers have adopted ultrasonic welding machines to improve precision and efficiency in plastic joining applications. Traditional methods such as hot gas welding and extrusion welding are being complemented by innovative technologies like laser welding, ultrasonic welding, and spin welding. These advanced techniques offer higher precision, faster processing times, and enhanced efficiency, meeting the stringent requirements of modern manufacturing processes. Laser welding, in particular, has gained popularity due to its ability to weld complex geometries with minimal distortion, while ultrasonic welding is increasingly used in applications that demand high-quality, clean welds, such as medical devices. These advancements not only improve the quality of welded plastic products but also help reduce energy consumption and waste, making the technologies more attractive to businesses focused on sustainability.
Increasing Infrastructure Development and Urbanization
The UAE’s continuous urbanization and rapid infrastructure development are significant drivers of growth in the plastic welding equipment market. The government’s focus on large-scale construction projects, such as commercial buildings, residential complexes, and transportation systems, has spurred the demand for plastic components in various applications. For instance, plastic pipes and fittings are widely used in water and sewage systems, while plastic-based materials are becoming increasingly common in interior construction. As the UAE continues to invest in infrastructure, the demand for plastic welding equipment for producing and assembling these components is expected to grow. The expanding urbanization and the push for modernization ensure a sustained requirement for advanced welding technologies in the region.
Environmental and Sustainability Considerations
The growing emphasis on environmental sustainability in the UAE is another significant driver for the adoption of plastic welding equipment. Plastic welding technologies, which offer more efficient and precise methods of joining plastic components, help reduce material waste and energy consumption during production. This aligns with the broader sustainability goals set by the UAE government, which has actively sought to improve waste management and reduce carbon footprints across industries. Additionally, plastic welding allows for better recycling and reuse of plastic materials, further supporting eco-friendly practices. As manufacturers increasingly adopt these sustainable solutions, the demand for advanced plastic welding equipment continues to rise, making it an essential tool for businesses striving to meet both production goals and environmental regulations.
Market Trends
Shift Towards Automation and Smart Manufacturing
A key trend in the UAE plastic welding equipment market is the growing shift toward automation and smart manufacturing solutions. For instance, Rockwood Welding Automation has highlighted the increasing adoption of automated welding systems in the UAE’s manufacturing sector, particularly in metalworking and heavy machinery. As industries strive for greater efficiency and reduced production costs, there is a clear move towards incorporating automated welding systems into production lines. These systems, which often integrate robotics and artificial intelligence (AI), enhance precision, speed, and consistency, while minimizing human error. Automated plastic welding solutions enable manufacturers to meet high production volumes with reduced labor costs and shorter cycle times. With the increasing focus on Industry 4.0 and smart factory setups, the demand for automated plastic welding equipment is expected to rise significantly in the UAE, driving market growth in this direction.
Rising Adoption of Laser and Ultrasonic Welding Technologies
Another notable trend is the increasing adoption of advanced welding technologies, particularly laser welding and ultrasonic welding, in the UAE. These technologies offer distinct advantages over traditional methods, including superior precision, speed, and the ability to weld complex geometries. Laser welding, known for its high accuracy and ability to minimize heat-affected zones, is becoming increasingly popular in industries that require high-performance plastic components, such as the automotive and electronics sectors. Ultrasonic welding, on the other hand, is ideal for high-speed applications with a focus on quality and cleanliness. These advanced welding technologies are in high demand due to their ability to produce strong, clean, and reliable joints while reducing energy consumption and material waste, aligning with the trend toward more sustainable production practices.
Focus on Sustainability and Eco-friendly Practices
Sustainability is becoming a critical focus in the UAE plastic welding equipment market, with an increasing emphasis on eco-friendly practices in manufacturing. For instance, the UAE Energy Strategy 2050 aims to generate 50% of the nation’s energy from clean sources, encouraging industries to adopt energy-efficient technologies. The adoption of plastic welding technologies that reduce energy consumption, material waste, and emissions is gaining momentum as companies aim to align with global sustainability initiatives. Plastic welding technologies, such as ultrasonic and laser welding, contribute to this goal by offering cleaner, more efficient methods of joining materials, which reduce the environmental impact compared to traditional welding techniques. Additionally, these technologies support the growing trend of plastic recycling, allowing for the reuse of materials in new products. As the UAE works to reduce its carbon footprint and promote greener practices across industries, the demand for sustainable plastic welding solutions continues to rise.
Expansion in the Automotive and Electronics Sectors
The UAE's plastic welding equipment market is also witnessing growth due to the expanding use of plastics in the automotive and electronics sectors. The automotive industry, in particular, is a major driver as manufacturers increasingly use lightweight plastic components to improve fuel efficiency and reduce emissions. These components, which include bumpers, dashboards, and other interior parts, require advanced welding technologies for assembly. Similarly, in the electronics sector, plastic welding is essential for producing high-precision components such as enclosures, connectors, and casings for electronic devices. As both industries continue to grow in the UAE, driven by increasing consumer demand and technological innovation, the need for advanced plastic welding equipment is expected to escalate, creating further market opportunities.
Market Challenges Analysis
High Initial Investment and Maintenance Costs
One of the key challenges in the UAE plastic welding equipment market is the high initial investment and ongoing maintenance costs associated with advanced welding technologies. For instance, laser welding machines can range from a few thousand dollars for entry-level models to over $100,000 for industrial-grade systems, making them a significant financial commitment for SMEs. While automated systems, laser welding, and ultrasonic welding offer superior performance, their initial purchase price and installation costs can be prohibitive, especially for small and medium-sized enterprises (SMEs). Additionally, these systems require regular maintenance and specialized training for operators, which can further increase operational costs. For businesses with limited capital, these financial barriers can pose significant challenges to adopting advanced plastic welding solutions, potentially slowing the adoption rate of these technologies in the market.
Skill Gaps and Training Requirements
Another challenge facing the plastic welding equipment market in the UAE is the shortage of skilled labor and the need for extensive training. The advanced welding techniques, such as laser and ultrasonic welding, require operators with specialized technical knowledge and experience to operate and maintain the equipment effectively. However, there is a skills gap in the region, with a limited pool of trained professionals capable of handling these complex systems. Companies must invest in training programs to upskill their workforce, which adds to their operational costs. Additionally, the lack of sufficient training resources can lead to inefficiencies and errors in production, further hindering the market’s growth potential. This challenge is particularly relevant in a rapidly developing industry where keeping up with technological advancements is essential for competitiveness.
Market Opportunities
The UAE plastic welding equipment market presents several promising opportunities due to the rapid growth of key industries such as automotive, construction, and electronics. As the automotive sector increasingly relies on lightweight plastic components to improve fuel efficiency and reduce emissions, the demand for advanced welding technologies, including laser and ultrasonic welding, is expected to rise. Additionally, the construction industry’s growing use of plastic pipes, fittings, and insulation materials provides significant opportunities for plastic welding equipment, particularly as the UAE continues its large-scale infrastructure projects. As urbanization and industrialization accelerate in the region, the need for durable, high-quality plastic components will drive further adoption of welding technologies, offering substantial growth potential for equipment suppliers.
Another significant opportunity lies in the growing emphasis on sustainability and eco-friendly manufacturing practices. As the UAE seeks to align with global environmental goals, companies are increasingly looking for ways to reduce waste, energy consumption, and carbon emissions in their production processes. Plastic welding technologies, such as ultrasonic and laser welding, help achieve these goals by providing efficient and precise methods of joining materials with minimal waste. Additionally, these technologies support the growing trend of plastic recycling, which is becoming increasingly important in various industries. As businesses across the UAE adopt more sustainable practices, the demand for energy-efficient, low-waste welding solutions will continue to grow, creating new opportunities for plastic welding equipment manufacturers and suppliers to cater to the region’s evolving market needs.
Market Segmentation Analysis:
By Type:
The UAE plastic welding equipment market can be categorized into three main types based on automation: manual, semi-automatic, and fully automatic. Manual plastic welding equipment remains popular in small-scale operations or for applications requiring high customization, where operators can adjust settings according to specific needs. However, its demand is gradually being surpassed by semi-automatic and fully automatic systems, as businesses seek greater efficiency and precision. Semi-automatic welding equipment strikes a balance between manual and fully automatic systems, offering increased productivity and reducing human error while maintaining flexibility in production. This segment is seeing growth in industries with mid-scale operations, where automation is necessary but complete system integration is not yet required. Fully automatic plastic welding systems are gaining traction, particularly in large-scale manufacturing environments. These systems provide the highest level of precision, speed, and efficiency, making them ideal for industries requiring high-volume production, such as automotive and electronics. The demand for automated solutions is expected to rise as businesses in the UAE prioritize speed, consistency, and reduced operational costs.
By Application:
In terms of application, the UAE plastic welding equipment market is driven by demand across several key industries, including electronics, packaging, automotive, and medical devices. The electronics sector is witnessing significant growth as the need for high-quality, precise plastic enclosures and components for devices such as smartphones, laptops, and medical equipment intensifies. Plastic welding is crucial for assembling these components, with ultrasonic and laser welding techniques being particularly popular for their ability to achieve precise, clean welds. The packaging sector also contributes significantly to the market, driven by the increasing demand for plastic packaging solutions in food, beverage, and consumer goods industries. In the automotive industry, plastic welding equipment is essential for assembling lightweight components such as bumpers and dashboards, supporting the growing trend of using plastics to reduce vehicle weight and improve fuel efficiency. The medical device industry’s growing need for durable, high-quality plastic parts, such as surgical instruments and diagnostic equipment, also supports the demand for advanced welding technologies. As these industries continue to expand in the UAE, the demand for specialized plastic welding equipment is expected to increase, offering promising growth opportunities for the market.
Segments:
Based on Type:
- Manual
- Semi-automatic
- Fully Automatic
Based on Application:
- Electronics
- Packaging
- Automotive
- Medical Devices
- Others
Based on Technology:
- Ultrasonic Welding
- Hot Plate Welding
- Spin Welding
- Laser Welding
- Others
Based on the Geography:
- Abu Dhabi
- Dubai
- Sharjah
- Ajman
- Fujairah
- Ras Al Khaimah
- Umm Al Quwain
Regional Analysis
Dubai
Dubai holds the largest market share at approximately 40%, owing to its position as the UAE's commercial and industrial hub. The city is home to numerous manufacturing and automotive industries that rely heavily on plastic welding technologies for production. Dubai's strong infrastructure, coupled with its strategic location for trade and its focus on industrial diversification, has attracted substantial investments in manufacturing and construction sectors, further driving demand for advanced plastic welding equipment. This trend is expected to continue, maintaining Dubai’s lead in the market share.
Abu Dhabi
Abu Dhabi follows closely, accounting for around 30% of the UAE’s plastic welding equipment market. As the capital of the UAE, Abu Dhabi is the center for large-scale industrial projects, including the oil, gas, and petrochemical sectors. These industries increasingly use plastic components for various applications, requiring precise welding solutions. The city’s significant investments in infrastructure development and manufacturing capacity, along with its push for technological advancement, contribute to the growing demand for plastic welding equipment. Moreover, the continued development of the automotive and construction sectors in Abu Dhabi ensures strong growth prospects for this region in the coming years.
Sharjah
Sharjah holds a market share of approximately 15%, driven by its robust manufacturing base, which is centered around plastics, packaging, and industrial products. The emirate’s manufacturing sector is a key driver for the demand for plastic welding equipment, particularly in packaging, where plastic components need to be securely joined. Sharjah’s relatively lower operational costs compared to Dubai and Abu Dhabi also make it an attractive location for SMEs involved in plastic component manufacturing. With ongoing industrial expansion, Sharjah is expected to maintain steady growth in its share of the plastic welding equipment market.
Ajman, Fujairah, Ras Al Khaimah, and Umm Al Quwain
Other smaller emirates such as Ajman, Fujairah, Ras Al Khaimah, and Umm Al Quwain contribute collectively to the remaining 15% of the market share. These regions are growing steadily in terms of industrial and infrastructure development, although they are not yet major players in the plastic welding equipment market compared to Dubai, Abu Dhabi, and Sharjah. However, the demand for plastic welding equipment in these regions is expected to rise as they continue to develop their manufacturing sectors, particularly in automotive, packaging, and construction. As these areas expand their industrial capacities, their contribution to the UAE plastic welding equipment market is projected to increase in the future.
Key Player Analysis
- Leister Technologies AG
- RITMO S.p.A.
- Emerson Electric Co.
- Herrmann Ultraschalltechnik GmbH & Co. KG
- Frimo Group GmbH
- Bielomatik Leuze GmbH & Co. KG
- Mecasonic Group
- CEMAS Elettra
- CHN-TOP Machinery Group
- Haitian International Holdings Ltd.
Competitive Analysis
The UAE plastic welding equipment market is highly competitive, with leading players offering a wide range of solutions to cater to the growing demand across various industries. Prominent companies in the market include Leister Technologies AG, RITMO S.p.A., Emerson Electric Co., Herrmann Ultraschalltechnik GmbH & Co. KG, Frimo Group GmbH, Bielomatik Leuze GmbH & Co. KG, Mecasonic Group, CEMAS Elettra, CHN-TOP Machinery Group, and Haitian International Holdings Ltd. These players dominate the market with their advanced plastic welding technologies, including manual, semi-automatic, and fully automatic welding systems, each offering specialized benefits in terms of precision, speed, and cost-effectiveness. There is a growing emphasis on integrating automation, energy efficiency, and precision in welding technologies to cater to the evolving needs of industries such as automotive, packaging, electronics, and construction. The competitive landscape is also shaped by increasing investments in research and development to enhance product capabilities and meet sustainability standards. Manufacturers are focusing on expanding their presence in high-growth regions like Dubai and Abu Dhabi, where industrial and infrastructure development is robust. Additionally, companies are developing strategic partnerships and distribution networks to strengthen market access and improve customer service. The rising demand for fully automated systems is encouraging continuous innovation, with players working to deliver cost-effective and high-performance welding solutions.
Recent Developments
- In March 2025, Leister transferred its laser plastic welding business to Hymson Novolas AG, a subsidiary of Hymson Laser Technology Group Co. Ltd. The transition ensures continuity and further development of existing product lines, with a new Laser Technology Center established in Switzerland. Leister will now focus more on its core competencies: plastic welding (hot air, infrared) and industrial process heat.
- In February 2025, Herrmann continues to set industry standards with its ultrasonic welding solutions, particularly for medical devices and sensitive components. The company emphasizes individualized process development, intelligent process control, and digital quality monitoring for reproducible, high-strength welds. Herrmann will showcase new applications and integration options at K 2025, focusing on automation and sustainability in medical and packaging industries.
- In January 2025, Dukane highlighted its patented Q-Factor, Melt-Match®, Low Amplitude Preheat, and Ultra-High Frequency (260–400 Hz) vibration welding technologies, emphasizing their leadership in process control and diagnostics.
- In May 2024, Emerson launched the Branson™ GLX-1 Laser Welder, designed for the automated assembly of small, intricate plastic parts. The GLX-1 features a compact, modular design suitable for cleanroom environments, advanced servo-based actuation, and the ability to “un-weld” plastics for closed-loop recycling. It uses Simultaneous Through-Transmission Infrared® (STTlr) laser-welding technology for high efficiency, weld strength, and aesthetics. Enhanced connectivity, security, and data collection features support Industry 4.0 integration.
Market Concentration & Characteristics
The UAE plastic welding equipment market exhibits moderate to high market concentration, characterized by the presence of several established manufacturers offering specialized and technologically advanced solutions. The market is defined by a strong emphasis on product quality, precision, and reliability, catering to the growing needs of industries such as automotive, electronics, construction, and medical devices. Key characteristics of the market include a shift towards automation, increasing adoption of energy-efficient and sustainable welding technologies, and a focus on high-performance applications. Innovation plays a central role, with companies investing in R&D to develop customized solutions that meet evolving industrial requirements. Additionally, the market demonstrates a strong preference for ultrasonic and laser welding systems, driven by their efficiency and clean processing capabilities. While larger enterprises dominate the competitive landscape, there is also a growing space for niche players offering specialized equipment for specific applications. Overall, the market is dynamic and continuously evolving with technological advancements and industrial growth.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Technology and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The UAE plastic welding equipment market is projected to grow steadily, driven by increasing demand across automotive, electronics, and construction sectors.
- Advancements in welding technologies, such as laser and ultrasonic systems, are enhancing precision and efficiency in manufacturing processes.
- The adoption of automation and smart manufacturing practices is leading to a shift towards fully automated welding systems.
- Sustainability initiatives are encouraging the development of eco-friendly welding equipment that reduces energy consumption and waste.
- The construction industry's expansion, particularly in infrastructure projects, is boosting the demand for plastic welding solutions.
- Integration of digital technologies like IoT and AI is transforming welding equipment, enabling real-time monitoring and improved productivity.
- The medical device industry's growth is contributing to increased demand for high-quality plastic welding applications.
- Challenges such as high initial investment costs and the need for skilled labor are affecting the adoption rate among small and medium enterprises.
- Regional development in emirates like Dubai and Abu Dhabi is fostering market growth through industrialization and infrastructure investments.
- The competitive landscape is intensifying, with companies focusing on innovation and strategic partnerships to gain market share.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Demand Across Key Industries
The increasing reliance on plastic components in automotive, construction, and manufacturing sectors in the UAE is driving the need for advanced plastic welding equipment, as these industries require durable, lightweight, and cost-effective solutions.
Advancements in Welding Technologies
The adoption of innovative technologies such as laser and ultrasonic welding is enhancing manufacturing efficiency, precision, and product quality, making plastic welding equipment more attractive for high-performance applications.
Increasing Infrastructure Development and Urbanization
Large-scale infrastructure projects and rapid urbanization in the UAE are boosting demand for plastic pipes, fittings, and construction materials, all of which require reliable plastic welding solutions for assembly and installation.
Focus on Sustainability and Eco-friendly Practices
The UAE's emphasis on sustainability and reducing material waste is accelerating the adoption of plastic welding equipment, as these technologies offer cleaner, more energy-efficient, and recyclable joining methods.
Shift Towards Automation and Smart Manufacturing
Manufacturers in the UAE are increasingly integrating automated and smart welding systems to improve production speed, consistency, and reduce labor costs, fueling demand for fully automatic plastic welding equipment.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the UAE Plastic Welding Equipment?
What are the key segments within the UAE Plastic Welding Equipment?
What are some challenges faced by the UAE Plastic Welding Equipment?
Who are the major players in the UAE Plastic Welding Equipment?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Manual
- 1.2.2 Semi-automatic
- 1.2.3 Fully Automatic
- 1.3 By Technology
- 1.3.1 Ultrasonic Welding
- 1.3.2 Hot Plate Welding
- 1.3.3 Spin Welding
- 1.3.4 Laser Welding
- 1.3.5 Others
- 1.4 By Application
- 1.4.1 Electronics
- 1.4.2 Packaging
- 1.4.3 Automotive
- 1.4.4 Medical Devices
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 24.87 million → 2032: USD 36.20 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 UAE Plastic Welding Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 UAE Plastic Welding Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 UAE Plastic Welding Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 UAE Plastic Welding Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 UAE Plastic Welding Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 UAE Plastic Welding Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 UAE Plastic Welding Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 UAE Plastic Welding Equipment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 24.87 million → 2032: USD 36.20 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 UAE Plastic Welding Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Manual
- 12.3.7.2 Semi-automatic
- 12.3.7.3 Fully Automatic
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Ultrasonic Welding
- 12.4.7.2 Hot Plate Welding
- 12.4.7.3 Spin Welding
- 12.4.7.4 Laser Welding
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Electronics
- 12.5.7.2 Packaging
- 12.5.7.3 Automotive
- 12.5.7.4 Medical Devices
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 UAE Plastic Welding Equipment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 UAE Plastic Welding Equipment Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 UAE Plastic Welding Equipment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 UAE Plastic Welding Equipment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Leister Technologies AG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 RITMO S.p.A.
- 18.4 Emerson Electric Co.
- 18.5 Herrmann Ultraschalltechnik GmbH & Co. KG
- 18.6 Frimo Group GmbH
- 18.7 Bielomatik Leuze GmbH & Co. KG
- 18.8 Mecasonic Group
- 18.9 CEMAS Elettra
- 18.10 CHN-TOP Machinery Group
- 18.11 Haitian International Holdings Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

