
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| UK Data Center Infrastructure Management (DCIM) market Size 2023 | USD 152.18 million |
| UK Data Center Infrastructure Management (DCIM) market, CAGR | 7.99% |
| UK Data Center Infrastructure Management (DCIM) market Size 2032 | USD 288.47 million |
Market Overview
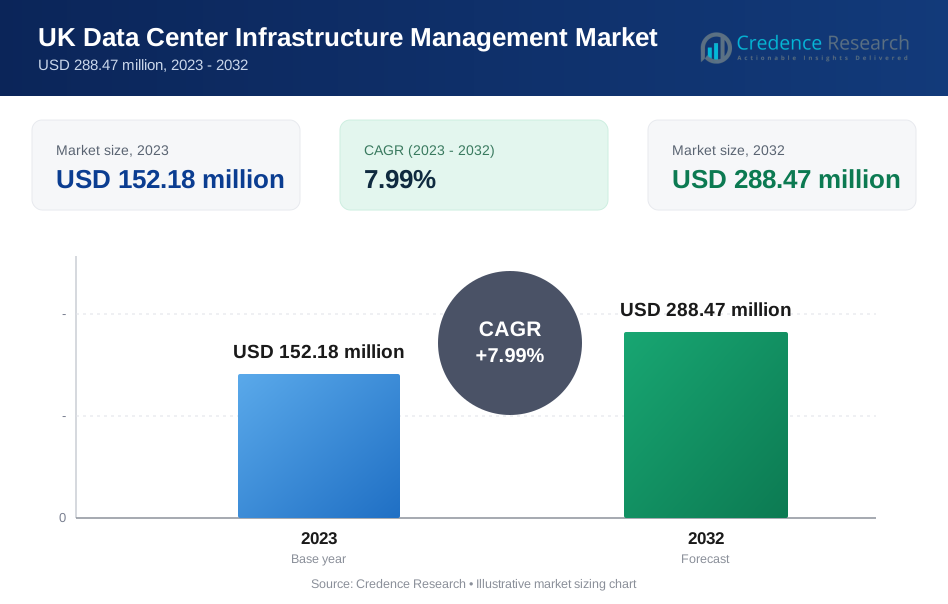
The UK Data Center Infrastructure Management (DCIM) market is projected to grow from USD 152.18 million in 2023 to USD 288.47 million by 2032, reflecting a compound annual growth rate (CAGR) of 7.99%.
The UK Data Center Infrastructure Management (DCIM) market is primarily driven by the increasing demand for energy-efficient data centers and the growing adoption of cloud services across various industries. The integration of AI and IoT technologies enhances operational efficiencies and predictive maintenance capabilities, further propelling market growth. Additionally, the shift towards sustainable practices and the implementation of green data centers are key trends, as organizations focus on reducing their carbon footprint while adhering to stringent environmental regulations. These drivers are crucial in shaping the future landscape of the UK DCIM market.
In the UK Data Center Infrastructure Management (DCIM) market, London and Scotland represent significant geographical segments. London, as a global financial and technological hub, has a substantial demand for sophisticated DCIM solutions to manage its dense network of data centers supporting myriad high-tech and financial enterprises. Meanwhile, Scotland is emerging as a strategic location for data centers due to its cooler climate and renewable energy resources, appealing to companies focused on sustainability. Key players such as ABB, Schneider Electric, and Cisco Systems, Inc., are instrumental in driving innovation and adoption of DCIM solutions across these regions, addressing local and industry-specific needs.
Market Drivers
Growing Demand for Data Centers
The UK's data center market is experiencing robust growth driven by the increasing digitalization of services, heightened mobile connectivity, and the rapid proliferation of online platforms. This surge in data generation necessitates expansive data storage and processing facilities. For instance, the integration of Internet of Things (IoT) devices and artificial intelligence (AI) applications further compounds this demand, requiring resilient infrastructure capable of handling complex data operations. Additionally, the widespread adoption of cloud computing solutions is spurring the need for more sophisticated data centers.
Need for Efficient and Cost-Effective Operations
Amid rising energy costs and a strong focus on sustainability, the importance of energy-efficient data center operations has become paramount. For instance, these solutions not only enhance energy efficiency but also align with the broader industry shift towards sustainable practices, helping firms reduce their environmental impact without compromising on service quality or operational capacity. Data Center Infrastructure Management (DCIM) solutions are pivotal in helping organizations optimize resource use, thereby slashing operational costs while boosting overall efficiency.
Data Security and Compliance
In an era marked by frequent and severe data breaches, securing data assets has become a critical priority for businesses. DCIM solutions play an essential role in fortifying data centers against security threats and ensuring compliance with stringent regulations such as the General Data Protection Regulation (GDPR). These tools provide enhanced oversight and control mechanisms, enabling organizations to maintain high standards of data security and meet compliance requirements effectively, thus safeguarding sensitive information and maintaining trust with stakeholders.
Advancements in Technology and Competitive Pressure
The data center sector is also shaped by continual technological advancements and competitive dynamics. Emerging technologies such as edge computing, 5G, and blockchain present new opportunities for enhancing data center infrastructure management. Simultaneously, automation and AI are revolutionizing operations by minimizing human error and optimizing efficiency. This technological evolution, coupled with intense market competition, compels businesses to leverage DCIM solutions to distinguish themselves through efficient operations and superior service delivery, thereby securing a competitive edge in a crowded market.
Market Trends
Enhanced Sustainability and Technological Integration in Data Centers
The focus on sustainability within the data center sector is intensifying as facilities increasingly adopt energy-efficient technologies and integrate renewable energy sources to minimize their environmental impact. This shift not only addresses the urgent need to reduce carbon footprints but also aligns with global efforts to combat climate change. For instance, a recent survey found that a significant number of data centers are now utilizing renewable energy sources such as solar and wind power. Water conservation measures are also being implemented more broadly to mitigate the impact of regional water scarcities. Alongside these green initiatives, the sector is experiencing a transformation through the integration of advanced automation and artificial intelligence. Modern Data Center Infrastructure Management (DCIM) solutions are harnessing AI and machine learning to not only automate mundane tasks but also enhance operational efficiencies and enable predictive maintenance. These intelligent systems are crucial for preempting potential issues, thereby minimizing downtime and reducing maintenance costs, which are critical for maintaining high availability and service reliability in today’s data-driven environments.
Adoption of New Architectures and Security Enhancements in Data Management
Concurrently, the data center landscape is evolving through the adoption of edge computing and the development of micro data centers. These technologies facilitate distributed data processing closer to the source of data generation, significantly reducing latency and improving performance for real-time data applications. This proximity is vital for emerging technologies that rely on instantaneous data processing. Moreover, the scalability and flexibility offered by cloud-based DCIM solutions are transforming how businesses manage their data infrastructures. These solutions allow for seamless scalability and integration with other cloud services, catering to the dynamic needs of modern enterprises without hefty upfront investments. On the security front, data centers are ramping up cybersecurity measures to protect against increasingly sophisticated threats and ensure compliance with stringent data privacy regulations such as GDPR. This comprehensive approach to security and privacy is crucial in maintaining trust and operational integrity in an era where data breaches can have devastating consequences on reputational and financial fronts. These trends collectively highlight a significant shift towards more resilient, efficient, and sustainable data management practices in the data center industry.
Market Challenges Analysis
Financial Burdens and Regulatory Challenges in Data Center Operations
The operation and expansion of data centers in the UK are significantly hindered by high capital costs and stringent regulatory compliance demands. Building and maintaining modern data center facilities require substantial initial investments, encompassing infrastructure, state-of-the-art equipment, and strategic real estate acquisitions. For instance, Amazon Web Services (AWS) has committed to investing £8 billion in data centers in the UK over the next five years. Furthermore, the ongoing operational costs, primarily driven by substantial energy consumption, pose persistent financial challenges, especially for large-scale operations striving for high availability and performance. These financial outlays are exacerbated by the need to adhere to a complex and ever-evolving regulatory landscape. Data centers must navigate and comply with stringent data privacy and security regulations, such as GDPR, which entail both logistical challenges and additional costs. The constant evolution of these regulations adds layers of complexity to compliance, demanding continuous oversight and adaptation that can strain resources and operational focus.
Market Competition and Technological Evolution Impacting Data Center Viability
The UK data center market faces intense competitive pressures and rapid technological advancements, creating a challenging environment for businesses. The market is crowded with both domestic and international players, fostering a competitive landscape that often leads to aggressive pricing strategies and potential squeezes on profitability. This competition is further intensified by the need to attract and retain specialized expertise in data center infrastructure management—a field where skilled professionals are in high demand and short supply, leading to a competitive market for talent. Additionally, data centers must continuously update and adapt to emerging technologies to stay relevant and efficient. The pace of technological change can render existing infrastructure obsolete within a few years, necessitating ongoing investments in upgrades and replacements. This cycle of rapid obsolescence is challenging to manage financially and operationally. Moreover, the reliance on global supply chains introduces vulnerabilities to external disruptions, such as pandemics or geopolitical tensions, which can lead to equipment shortages and project delays, further compounding the challenges faced by data center operators in maintaining competitive and efficient operations while striving for sustainability and compliance.
Market Segmentation Analysis:
By Component:
The UK Data Center Infrastructure Management (DCIM) market is strategically segmented into solutions and services, addressing diverse operational demands. The solutions segment encompasses software that optimizes the performance and efficiency of data centers through enhanced visibility and control of infrastructure. These solutions are critical for real-time monitoring, energy management, and ensuring system reliability. On the other hand, the services segment includes professional services such as installation, integration, and support, which are vital for the seamless operation and maintenance of DCIM systems. Services also cover managed DCIM services, which are increasingly popular among enterprises seeking to outsource the complexities of data center management to focus on core business functions. This bifurcation ensures that all aspects of data center infrastructure management are comprehensively addressed, catering to a wide range of business needs and operational scales within the UK market.
By Application:
In terms of application, the UK DCIM market is categorized into asset management, capacity management, power monitoring, environment monitoring, BI and analytics, and others. Asset management tools are essential for optimizing the use of all physical and digital assets within data centers, enhancing operational efficiency. Capacity management solutions help forecast future resource needs and manage current capacities to avoid underutilization or overloading of resources. Power monitoring is increasingly critical, given the focus on energy efficiency and cost reduction. Environment monitoring solutions ensure that the data center’s physical environment is maintained within optimal parameters, thereby prolonging equipment life and reducing the risk of system failures. Lastly, BI and analytics applications provide valuable insights that drive strategic decision-making and continuous improvement in data center operations. This segmentation by application highlights the multifaceted approach required to effectively manage the intricate ecosystems of modern data centers.
Segments:
Based on Component:
- Solutions
- Services
Based on Application:
- Asset Management
- Capacity Management
- Power Monitoring
- Environment Monitoring
- BI and Analytics
- Others
Based on End-user:
- Enterprise Data Center
- Managed Data Center
- Colocation Data Center
- Cloud and Edge Data Center
Based on Deployment:
- On-premise
- Cloud
Based on Enterprise:
- Small and Medium-Sized Enterprises (SMEs)
- Large-Sized Enterprise
Based on Distribution Channel:
- BFSI
- Government and Public Sector
- IT and ITeS
- Healthcare and Life Sciences
- Others
Based on the Geography:
- London
- Scotland
Regional Analysis
London
The UK data center infrastructure management (DCIM) market is dominated by London, which holds a commanding 45% market share. As the country's financial and technological hub, London's insatiable demand for robust, efficient, and scalable data center solutions drives the DCIM market forward. The city's status as a global business center attracts multinational corporations and tech startups alike, all requiring state-of-the-art data management capabilities. London's dense urban environment and stringent energy regulations have spurred the adoption of sophisticated DCIM tools that optimize space utilization and energy efficiency. The presence of major cloud service providers and colocation facilities in the Greater London area further fuels the demand for advanced DCIM solutions. These providers leverage cutting-edge management tools to ensure high availability, security, and performance for their clients. Additionally, London's position as a leader in fintech and digital innovation creates a constant need for data centers that can handle high-frequency trading, blockchain technologies, and artificial intelligence workloads, all of which benefit from comprehensive DCIM solutions. The competitive nature of London's tech scene also drives continuous innovation in DCIM offerings, with vendors constantly evolving their products to meet the exacting standards of this demanding market.
Scotland
In contrast, Scotland holds a smaller but growing 12% market share in the UK DCIM market. The region's emergence as a data center hotspot is driven by several factors, including its cooler climate, which naturally aids in reducing cooling costs, and its commitment to renewable energy sources. Cities like Edinburgh and Glasgow are actively positioning themselves as attractive alternatives to London for data center operations, offering lower operational costs and a skilled workforce. The Scottish government's initiatives to boost the digital economy and attract tech investments have led to the establishment of new data centers, particularly in emerging tech hubs. These developments have created a growing demand for DCIM solutions tailored to the unique needs of the Scottish market. The region's focus on sustainability aligns well with modern DCIM tools that emphasize energy efficiency and environmental monitoring. As Scotland continues to diversify its economy and invest in digital infrastructure, the adoption of advanced DCIM solutions is expected to accelerate. The region's universities and research institutions also contribute to the DCIM market by driving innovation in areas such as edge computing and IoT, which require robust data center management capabilities.
Key Player Analysis
- ABB
- Intel Corporation
- Fujitsu
- Microsoft
- Cisco Systems, Inc.
- BGIS
- Panduit
- Eaton
- Schneider Electric
- Equinix, Inc.
- Vertiv Group Corp.
- Sunbird Software, Inc.
- Nlyte Software Limited
- FNT Software
- Rittal GmbH & Co. KG
- iTRACS, LLC
Competitive Analysis
The competitive landscape of the UK Data Center Infrastructure Management (DCIM) market is dominated by leading players such as ABB, Schneider Electric, Cisco Systems, Inc., Microsoft, and Vertiv Group Corp. These companies are at the forefront due to their robust product offerings that cater to the complex needs of modern data centers, including energy management, operational efficiency, and real-time data monitoring. Their competitive edge is further sharpened by continuous innovation, particularly in integrating AI and IoT into their solutions, enhancing their appeal to data centers focusing on automation and predictive maintenance. Strategic partnerships and acquisitions also play a crucial role in their market positioning, allowing them to expand their technological capabilities and market reach. This dynamic competition drives advancements in DCIM technologies, ensuring that data centers can meet the increasing demands for efficiency and compliance with environmental and data security standards.
Recent Developments
- In July 2024, Vertiv launched the Vertiv™ MegaMod™ CoolChip, a high-density prefabricated modular data center solution to accelerate global deployment of AI compute.
- In June 2024, Cisco revealed Nexus HyperFabric AI Clusters, a new simplified data center infrastructure solution with NVIDIA for generative AI.
- In August 2024, FNT Software released FNT Command 14, a platform with sustainability enhancements and improved usability features for managing IT, data center, and telecommunication infrastructures.
- In March 2024, Schneider Electric announced a collaboration with NVIDIA to optimize data center infrastructure and introduce AI data center reference designs.
- In June 2023, ABB announced the acquisition of Eve Systems, a Munich-based leader in smart home technology.
Market Concentration & Characteristics
The UK Data Center Infrastructure Management (DCIM) market exhibits a moderate level of market concentration, with a few dominant players such as ABB, Schneider Electric, and Cisco Systems, Inc., leading the industry. These companies have solidified their market positions through comprehensive product portfolios that offer advanced solutions for data center optimization and management. The market is characterized by a strong focus on innovation, particularly in areas such as energy efficiency, real-time monitoring, and the integration of AI and IoT technologies. These innovations are crucial in meeting the increasing demands of modern data centers for sustainability and operational efficiency. The presence of these leading players fosters a competitive environment that encourages continuous technological advancement and the development of solutions that address both current and emerging data center challenges. This dynamic market structure ensures that the UK DCIM market remains at the forefront of addressing the complex needs of data infrastructure management in an evolving technological landscape.
Report Coverage
The research report offers an in-depth analysis based on Component, Application, End-user, Deployment, Enterprise, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued growth in data center investments will drive the expansion of the DCIM market in the UK.
- Increasing adoption of cloud-based DCIM solutions due to their scalability and cost-effectiveness.
- Enhanced focus on energy efficiency and sustainability will lead to greater implementation of green technologies.
- Integration with IoT and AI technologies will improve operational efficiencies and predictive maintenance capabilities.
- Demand for real-time monitoring and advanced analytics will rise as organizations seek to optimize data center performance.
- The development of robust security features within DCIM solutions will be prioritized to address growing cybersecurity threats.
- Edge computing and micro data centers will necessitate DCIM solutions tailored for distributed and smaller infrastructures.
- Rapid technological advancements will require continuous updates and integrations in DCIM systems.
- Regulatory pressures will push organizations to adopt DCIM solutions that ensure compliance with industry standards.
- The competitive landscape will drive continuous innovation, leading to new features and enhancements in DCIM technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the UK Data Center Infrastructure Management Market?
What factors are driving the growth of the UK Data Center Infrastructure Management Market?
What are the key segments within the UK Data Center Infrastructure Management Market?
What are some challenges faced by the UK Data Center Infrastructure Management Market?
Who are the major players in the UK Data Center Infrastructure Management Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 UK Data Center Infrastructure Management Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global UK Data Center Infrastructure Management Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 152.18 million → 2032: USD 288.47 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 UK Data Center Infrastructure Management Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. UK Data Center Infrastructure Management Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 UK Data Center Infrastructure Management Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 UK Data Center Infrastructure Management Market Drivers
- 3.3 UK Data Center Infrastructure Management Market Restraints & Challenges
- 3.4 UK Data Center Infrastructure Management Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 UK Data Center Infrastructure Management Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 UK Data Center Infrastructure Management Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, UK Data Center Infrastructure Management category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 UK Data Center Infrastructure Management Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. UK Data Center Infrastructure Management Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the UK Data Center Infrastructure Management market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 UK Data Center Infrastructure Management Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 UK Data Center Infrastructure Management Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 UK Data Center Infrastructure Management Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in UK Data Center Infrastructure Management (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New UK Data Center Infrastructure Management Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global UK Data Center Infrastructure Management Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America UK Data Center Infrastructure Management Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe UK Data Center Infrastructure Management Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific UK Data Center Infrastructure Management Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America UK Data Center Infrastructure Management Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East UK Data Center Infrastructure Management Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa UK Data Center Infrastructure Management Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. UK Data Center Infrastructure Management Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
