
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| UK Interior Design Market Size 2023 | USD 5,583.51 millio |
| UK Interior Design Market, CAGR | 4.31% |
| UK Interior Design Market Size 2032 | USD 8,169.28 million |
Market Overview:
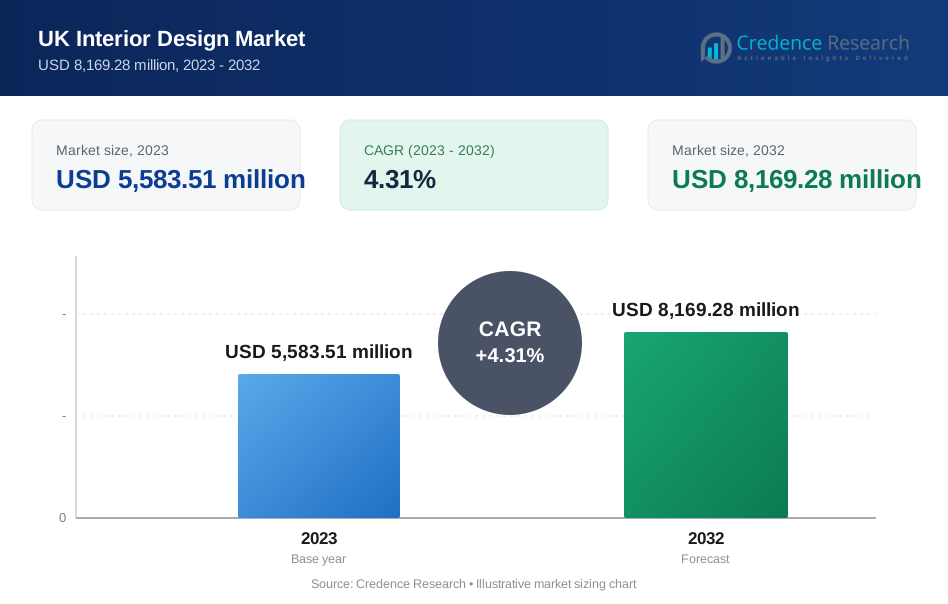
UK Interior Design Market size was valued at USD 5,583.51 million in 2023 and is anticipated to reach USD 8,169.28 million by 2032, at a CAGR of 4.31% during the forecast period (2023-2032).
Key drivers of the UK interior design market include changing consumer preferences, growing disposable income, and a heightened focus on sustainability. Consumers increasingly desire customized and aesthetically appealing spaces that reflect their personal styles. With an expanding middle class, consumer spending is rising, further driving demand for high-quality interior designs. The trend of home renovations, particularly post-COVID-19, has also played a significant role in market expansion. Businesses are investing in office spaces that promote employee well-being and productivity. Additionally, there is a growing shift toward eco-friendly, energy-efficient designs as consumers and businesses become more environmentally conscious. The adoption of technology, including smart home devices and augmented reality (AR) tools, further boosts the market’s growth potential by offering new ways to create immersive and personalized spaces.
Regionally, the UK interior design market displays a range of trends, with differences between urban and rural areas. London remains the primary hub, with a significant portion of the market focused on luxury residential projects, high-end retail stores, and commercial office spaces. London’s cosmopolitan nature drives demand for contemporary designs incorporating international styles, attracting both local and global clients. In contrast, cities like Manchester, Birmingham, and Edinburgh are seeing growing demand for interior design services, especially in residential and hospitality sectors, driven by economic growth, urbanization, and new construction. Additionally, the rise of remote work has increased demand for home office designs. The rural market, although smaller, is shifting toward more sustainable and rustic designs, blending with natural surroundings. The trend toward rural retreats and eco-friendly homes is expected to gain momentum as people seek to escape urban congestion.
Market Insights:
- The UK interior design market, valued at approximately USD 5,583.51 million in 2023, is projected to reach USD 8,169.28 million by 2032, driven by increasing consumer demand for personalized and aesthetically appealing spaces.
- Economic recovery and rising disposable incomes are fueling demand for both luxury and affordable interior design services, particularly in urban areas.
- Sustainability is a key driver, with both businesses and consumers prioritizing eco-friendly materials and energy-efficient designs to align with environmental goals.
- Technological advancements, including smart home devices and augmented reality tools, are transforming the design process and enhancing consumer engagement.
- The residential segment remains the largest market share, but commercial, hospitality, and healthcare projects are growing rapidly due to increased investments in workspaces and customer-centric environments.
- High costs associated with luxury and custom-designed interiors are limiting access to premium services for a broader audience, especially in rural or economically constrained areas.
- Regional disparities are evident, with London and major cities like Manchester and Birmingham driving the majority of demand, while rural areas focus more on sustainable, rustic designs.
Market Drivers:
Increasing Demand for Customized and Aesthetic Spaces
One of the key drivers in the UK interior design market is the growing demand for customized and aesthetically pleasing spaces. Consumers today seek interior designs that reflect their personal tastes, lifestyles, and preferences. This desire for personalization has fueled the rise of bespoke designs, which allow individuals to transform their living and working environments into unique, expressive spaces. As homeownership rates rise and more people are spending time at home, particularly after the COVID-19 pandemic, the demand for home improvement and redesign services has surged. For instance, A report from techUK indicated that by November 2022, 77% of UK adults owned at least one connected home device, up from 67% pre-pandemic. From luxurious décor to minimalist designs, the focus is now on creating spaces that are not only functional but also resonate with personal identity, contributing to overall market growth.
Economic Growth and Rising Disposable Income
Economic growth and increasing disposable income are another driving factor for the UK interior design market. As the economy recovers and consumer confidence improves, people have more purchasing power, allowing them to invest in home and office redesigns. For instance, according to the Office for National Statistics (ONS), real households' disposable income (RHDI) per head in the UK increased by 1.3% in the second quarter of 2024. This trend is particularly evident in urban areas, where there is a higher concentration of wealth and demand for high-end interior design services. With the continuous rise in disposable income, especially among the middle class, more individuals and businesses are willing to spend on premium interior design solutions. This has led to an increase in the demand for both luxury and affordable design options, further propelling the market’s expansion.
Sustainability and Eco-Friendly Design Trends
The growing focus on sustainability and environmentally conscious design choices has become a significant driver for the UK interior design market. Consumers and businesses alike are increasingly prioritizing eco-friendly materials and energy-efficient designs. From using sustainable furniture to integrating renewable energy solutions and low-carbon-emitting paints, the interior design industry is aligning with broader environmental goals. This trend is further reinforced by the government’s commitment to reducing carbon emissions and promoting sustainable building practices. For instance, companies like IKEA and B&Q have committed to eco-friendly product offerings, with IKEA planning to make all of its products 100% sustainable by 2030. As eco-friendly products become more accessible and affordable, there is an increasing demand for designs that align with consumers' values of sustainability, driving growth in the sector.
Technological Advancements and Smart Home Integration
Technological advancements are playing an important role in shaping the UK interior design market. The rise of smart home technology, including voice-controlled systems, automated lighting, and integrated appliances, has influenced how interior spaces are designed and equipped. Homeowners and businesses alike are incorporating smart technology into their spaces to enhance convenience, security, and energy efficiency. Additionally, the use of augmented reality (AR) and virtual reality (VR) tools is transforming how interior designers visualize and communicate design concepts to clients. These technologies enable clients to see potential designs in 3D before making decisions, improving the design process and enhancing consumer satisfaction. For instance, Companies like JUMP into DESIGN® have developed platforms that enable users to create hyper-realistic designs in real-time using AR and VR technologies. Their software allows for 2D and 3D visualizations that can be viewed on low-spec devices or VR headsets, enhancing the design experience significantly. As technology continues to evolve, the integration of smart systems and digital tools into interior designs will remain a key driver in the market.
Market Trends:
Personalization and Customization in Interior Design
A prominent trend in the UK interior design market is the growing demand for personalization and customization. Consumers increasingly seek interior designs that reflect their individuality, values, and lifestyles. This shift has led to a greater focus on bespoke furniture, tailored layouts, and personalized design elements. Interior designers are now offering more flexible solutions, with an emphasis on creating unique spaces that tell a personal story. Homeowners and businesses are opting for customized materials, color schemes, and décor items, moving away from mass-produced products. For isntacne, Andrew Martin, a homeware brand that offers bespoke wallpaper featuring famous artworks from the National Gallery. This allows homeowners to incorporate unique, personalized elements into their spaces, reflecting individual tastes and stories. This trend is driven by a desire for more meaningful, curated spaces that offer both functionality and personal expression. The increased availability of technology and online platforms that allow for design customization has also contributed to this trend's growth.
Sustainable Design Solutions
Sustainability continues to be a defining trend in the UK interior design market. As climate change concerns grow, both consumers and businesses are increasingly prioritizing eco-friendly design solutions. The use of sustainable materials such as recycled furniture, low-VOC paints, and energy-efficient lighting is gaining traction. For instance, Sustainable design is gaining traction, as demonstrated by Spradling®, which recently collaborated with University of Westminster students to create sustainable architectural designs using eco-friendly fabrics. Moreover, there is a growing demand for designs that incorporate green building certifications, such as BREEAM or LEED. This trend is driven by both consumer awareness and governmental incentives to reduce carbon footprints. Consumers, particularly millennials and Gen Z, are more inclined to invest in sustainable interior designs, often opting for products and materials that are ethically sourced and environmentally responsible. As sustainable practices become more mainstream, the market for eco-friendly interior design is expected to continue growing.
Technology Integration and Smart Interiors
Technology integration is rapidly reshaping the UK interior design market, with a strong emphasis on smart homes and automation. The demand for connected living spaces has led to the incorporation of smart home technologies into interior design. Homeowners are increasingly integrating devices such as voice-activated assistants, smart thermostats, lighting systems, and security features into their living environments. This trend is not limited to residential spaces; businesses are also adopting smart office solutions to enhance productivity and employee comfort. The rise of augmented reality (AR) and virtual reality (VR) tools is another major technology-driven trend, allowing clients to visualize and interact with designs before finalizing decisions. For instance, Smart home technology is becoming integral to interior design, with companies like Metercube offering tailored interior packages that seamlessly integrate smart devices into living spaces. This approach enhances both functionality and aesthetic appeal, making homes more efficient and user-friendly. As technology advances, the blending of interior design with smart systems is expected to become even more prevalent, making homes and workplaces more efficient and comfortable.
Multifunctional Spaces and Remote Work Adaptations
The rise of remote work has significantly impacted the UK interior design market, with many individuals and businesses now prioritizing multifunctional spaces. With the increase in home offices and the blending of work and personal life, there is a growing demand for flexible and adaptable designs. Consumers are looking for spaces that can easily transition from work areas to relaxation zones, often incorporating modular furniture and movable partitions to maximize space utilization. In urban areas where space is often limited, there is a particular focus on designing smaller, more efficient living spaces that cater to multiple functions. This trend is driving demand for multifunctional furniture, such as fold-away desks, expandable storage, and adaptable room layouts. For instance, the demand for multifunctional spaces is being addressed by companies like Hushoffice, which designs modular furniture that can easily adapt to various uses. This flexibility is crucial for accommodating the needs of remote workers who require versatile environments for both work and leisure. As remote working becomes a permanent fixture for many, the demand for these types of designs is expected to remain strong, influencing the broader interior design landscape.
Market Challenges Analysis:
High Costs of Luxury and Custom Designs
One of the primary restraints in the UK interior design market is the high cost associated with luxury and custom-designed interiors. While demand for bespoke solutions continues to grow, the significant price tags attached to high-end materials, furniture, and specialized design services can limit access to these offerings for a broader consumer base. Many homeowners and businesses may find it difficult to justify such high expenditures, especially when economic uncertainties and budget constraints are in play. This price sensitivity can hinder the expansion of the market to certain segments, particularly those outside of major urban centers where disposable incomes may be lower.
Shortage of Skilled Labour
The interior design industry in the UK is also facing a shortage of skilled labor, particularly in the fields of craftsmanship and specialized design services. As demand for custom, high-quality designs increases, so does the need for skilled professionals capable of delivering unique and sophisticated interiors. The lack of qualified designers, craftsmen, and tradespeople is creating challenges in meeting project timelines and maintaining the high standards expected by clients. This skill gap can lead to delays in project completion, increased labor costs, and a reduction in overall market productivity, particularly for smaller design firms.
Economic Instability and Uncertainty
Economic instability and market uncertainties, including fluctuations in property prices and potential interest rate hikes, are additional challenges that could hinder the growth of the interior design market in the UK. With a more cautious consumer attitude toward spending during uncertain economic periods, homeowners and businesses may prioritize essential purchases over discretionary investments like interior redesigns. Economic challenges can also impact the construction and real estate sectors, which in turn affect the demand for interior design services tied to these industries.
Supply Chain Disruptions
Supply chain disruptions, particularly in the wake of the COVID-19 pandemic, have continued to affect the interior design market. Delays in the availability of materials, furniture, and imported goods have impacted project timelines and costs. Designers and businesses are struggling to secure the necessary products to complete designs on time and within budget. Ongoing global supply chain challenges may further exacerbate these issues, impacting the overall efficiency and profitability of the interior design market.
Market Opportunities:
A significant market opportunity in the UK interior design sector lies in the growing demand for sustainable and eco-friendly design solutions. As consumer awareness around environmental issues increases, both residential and commercial clients are increasingly prioritizing green and energy-efficient designs. The trend toward using sustainable materials, such as recycled wood, natural fibers, and energy-efficient lighting, is expanding. Additionally, interior designs that incorporate renewable energy solutions, like solar-powered lighting and energy-efficient insulation, are gaining traction. Businesses and consumers alike are seeking to reduce their carbon footprints, presenting a prime opportunity for interior designers who specialize in eco-conscious designs. Designers who can offer environmentally responsible, aesthetically pleasing, and functional spaces are well-positioned to capture this growing segment of the market.
Another promising opportunity in the UK interior design market is the integration of smart home technology. As the demand for connected homes continues to rise, homeowners and businesses are looking to incorporate cutting-edge technology into their living and working environments. Smart home features, such as voice-controlled assistants, automated lighting, and security systems, offer immense potential for designers to create sophisticated, efficient spaces. Additionally, the use of augmented reality (AR) and virtual reality (VR) tools in interior design is transforming the industry, enabling clients to visualize and interact with designs before committing to them. These technologies not only enhance the customer experience but also offer opportunities for interior designers to differentiate themselves and provide innovative, tech-forward solutions. As technology continues to advance, the integration of smart systems and digital tools will remain a key driver for growth in the sector.
Market Segmentation Analysis:
The UK interior design market is diverse, with several segments contributing to its overall growth. In terms of
By project type, the residential segment dominates, driven by consumer demand for personalized living spaces. Commercial projects, including office spaces and corporate interiors, are also significant, reflecting the growing trend of businesses investing in aesthetically appealing, functional work environments. Hospitality, healthcare, and retail sectors also present opportunities, with hotels, medical facilities, and retail stores increasingly prioritizing interior designs that enhance customer experience. Educational institutions and public buildings contribute to the demand for specialized designs focused on functionality and efficiency.
By service type, interior design consulting is the most sought-after service, followed by space planning and furniture & fixture selection, as clients seek expert guidance in creating functional and visually appealing spaces. Lighting design and color consultation services are gaining traction, with an increasing focus on ambiance and aesthetic appeal.
By budget range of projects varies significantly, with the majority of consumers opting for mid-range budgets of $10,000-$50,000, while high-net-worth individuals and businesses often engage in larger projects, ranging from $250,000 to over $500,000 for luxury designs and new builds.
By project complexity, major renovations and new builds are prominent, particularly in urban areas. High-end luxury projects are also on the rise, driven by affluent clients seeking bespoke, opulent designs.
By client types, including homeowners, businesses, architects, contractors, developers, and property managers, each with unique needs and preferences, further enhancing the market's complexity and opportunity for tailored services.
Segmentation:
By Project Type
- Residential
- Commercial
- Hospitality
- Healthcare
- Retail
- Educational
- Public Buildings
By Service Type
- Interior Design Consulting
- Interior Decoration
- Space Planning
- Furniture & Fixture Selection
- Lighting Design
- Color Consultation
By Budget Range
- Under $10,000
- $10,000-$50,000
- $50,000-$100,000
- $100,000-$250,000
- $250,000-$500,000
- Over $500,000
By Project Complexity
- Simple Refurbishment
- Major Renovation
- New Build
- High-End Luxury
By Client Type
- Homeowners
- Businesses
- Architects
- Contractors
- Developers
- Property Managers
Regional Analysis:
The UK interior design market exhibits diverse regional trends, with distinct demands across various parts of the country. The market is primarily concentrated in urban areas, driven by the higher concentration of residential, commercial, and retail developments. However, there are notable differences in demand, driven by economic conditions, population density, and consumer preferences.
London and the South East
London remains the dominant region in the UK interior design market, commanding the largest share of approximately 40%. The city is a global hub for design, attracting high-net-worth individuals, luxury real estate developers, and multinational businesses. London’s interior design market is characterized by high demand for premium, bespoke solutions, particularly in luxury residential, commercial office spaces, and hospitality projects. The cosmopolitan nature of the city fosters a blend of international styles, pushing the envelope on innovative and high-end interior designs. Additionally, with a growing population and increasing urbanization, the South East also sees significant demand for interior design services, particularly in areas such as residential home renovations and urban regeneration projects.
Midlands and North of England
The Midlands and North of England represent another key region for the UK interior design market, contributing around 25% of the market share. Cities like Birmingham, Manchester, Leeds, and Sheffield have seen significant growth in their interior design sectors, driven by urban regeneration, commercial developments, and a growing interest in home remodeling. The demand in these regions is diverse, with residential and hospitality design projects being particularly prominent. The increasing number of young professionals, coupled with rising disposable income, has also contributed to a surge in demand for affordable yet stylish home design solutions. Businesses in these regions are also investing in office refurbishments to enhance employee well-being and productivity, further driving the demand for interior design services.
Scotland and Wales
Scotland and Wales, while smaller in market share, still play a significant role in the UK interior design landscape, contributing about 15% collectively. In Scotland, cities like Edinburgh and Glasgow are seeing increased demand for residential and hospitality design, driven by a booming tourism sector and a growing interest in sustainable design. Similarly, Wales is witnessing a surge in interest for eco-friendly, rural-inspired designs as the trend toward sustainable living continues to gain traction. Both regions are also capitalizing on trends like multifunctional spaces and remote work setups, driven by the broader shift toward flexible living and working arrangements.
South West and Northern Ireland
The South West of England, while accounting for a smaller portion of the market at approximately 10%, has shown growing demand for interior design services, particularly in rural retreats, eco-friendly homes, and holiday let properties. Northern Ireland, contributing around 5% to the overall market, is also experiencing a gradual increase in demand for both residential and commercial interior design, with an emphasis on traditional and contemporary blends suited to the region's unique architectural style. Both regions are benefiting from increasing interest in sustainable living and the demand for designs that blend with natural surroundings.
Key Player Analysis
- Gensler
- Jacobs Engineering Group Inc.
- Perkins and Will
- Stantec Inc
- Areen Design Services Ltd
- IA Interior Architects
- Cannon Design
- Hirsch Bedner Associates
- NELSON & Associates Interior Design and Space Planning Inc.
- Büro Kif
- Framework Studio
Competitive Analysis:
The UK interior design market is highly competitive, with a broad range of players, including established design firms, independent designers, and large-scale design consultancies. Key players dominate the market in terms of brand recognition and market share, including firms like Design Council, Alexander James Interiors, and Kelly Hoppen Interiors. These companies are known for their high-end, bespoke solutions catering to affluent clients across residential, commercial, and hospitality sectors. For instance, Known for integrating culture with design, Gensler emphasizes user experience in their projects and has a vast international presence . Additionally, the rise of digital platforms and online interior design services has introduced new competition, with companies offering cost-effective, personalized solutions through virtual consultations and augmented reality tools. To stay competitive, firms must differentiate themselves through innovation, sustainable design practices, and the integration of smart technologies. As consumer preferences shift towards eco-friendly and customized designs, businesses that prioritize sustainability, technology integration, and exceptional customer service are poised to capture market share and maintain a competitive edge.
Recent Developments:
- Stantec has opened a new office in Belfast in November 2024, located in the city's Cathedral Quarter. This move supports an increasing number of colleagues and aims to leverage cross-sector opportunities in community development, energy, and transport sectors. The office, designed with sustainability in mind, reflects Stantec's commitment to creating environments that support innovation and employee well-being.
Market Concentration & Characteristics:
The UK interior design market is characterized by moderate concentration, with a mix of large, well-established firms and smaller, independent design studios. While a few key players dominate the high-end residential and commercial sectors, such as Kelly Hoppen Interiors and Studioilse, the market is fragmented in terms of service offerings and client demographics. Larger firms often focus on luxury and bespoke designs, catering to high-net-worth individuals and corporate clients, while smaller studios may specialize in niche markets like sustainable designs or budget-friendly home renovations. The market is also defined by increasing specialization, with a growing focus on areas such as eco-friendly designs, smart home integration, and multi-functional spaces. Competitive dynamics are driven by innovation, customer experience, and the ability to deliver tailored solutions. As demand for personalized and sustainable designs continues to rise, firms that adapt to these evolving trends will continue to thrive in this dynamic market.
Report Coverage:
The research report offers an in-depth analysis based on By Project Type, By Service Type, By Budget Range , By Project Complexity and By Client Type. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The UK interior design market is anticipated to experience steady growth, driven by increasing consumer demand for personalized spaces.
- Increasing disposable incomes will fuel demand for both luxury and mid-range interior design services.
- Sustainable and eco-friendly design trends will continue to shape the market as consumers prioritize environmental responsibility.
- Technological integration, including smart home devices and AR/VR tools, will enhance customer experiences and increase market innovation.
- The remote work trend will further boost demand for home office designs and multifunctional spaces.
- Urban areas, particularly London, will remain the primary hubs for high-end and commercial interior design projects.
- Regional markets like Manchester, Birmingham, and Edinburgh will see significant growth in residential and hospitality design.
- The market will see increased competition from digital platforms offering virtual interior design services.
- Consumer interest in wellness-focused designs will drive demand for healthier, more ergonomic spaces.
- As the market matures, the emphasis will shift toward design firms that offer holistic, integrated, and technology-driven solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the UK interior design market?
What are the key drivers of the UK interior design market?
Which regions in the UK have the highest demand for interior design services?
What are the main challenges facing the UK interior design market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 UK Interior Design Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 UK Interior Design Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 5,583.51 million → 2032: USD 8,169.28 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 UK Interior Design Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. UK Interior Design Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 UK Interior Design Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 UK Interior Design Drivers
- 3.3 UK Interior Design Restraints & Challenges
- 3.4 UK Interior Design Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 UK Interior Design Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 UK Interior Design Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, UK Interior Design category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 UK Interior Design Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. UK Interior Design Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2023)
- 5.1.2 Export Volume by Destination Country (2023) (Where Applicable)
- 5.1.3 Import Value by Source Country (2023)
- 5.1.4 Import Volume by Source Country (2023) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to UK Interior Design in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 UK Interior Design Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2023
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 UK Interior Design Share Analysis – 2023
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution (the historical period vs. 2023)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 UK Interior Design Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in UK Interior Design (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in UK Interior Design
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. UK Interior Design – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. UK Interior Design – Priority Domestic Market 1
Chapter 10. UK Interior Design – Priority Domestic Market 2
Chapter 11. UK Interior Design – Priority Domestic Market 3
Chapter 12. UK Interior Design – Priority Domestic Market 4
Chapter 13. UK Interior Design Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
