
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
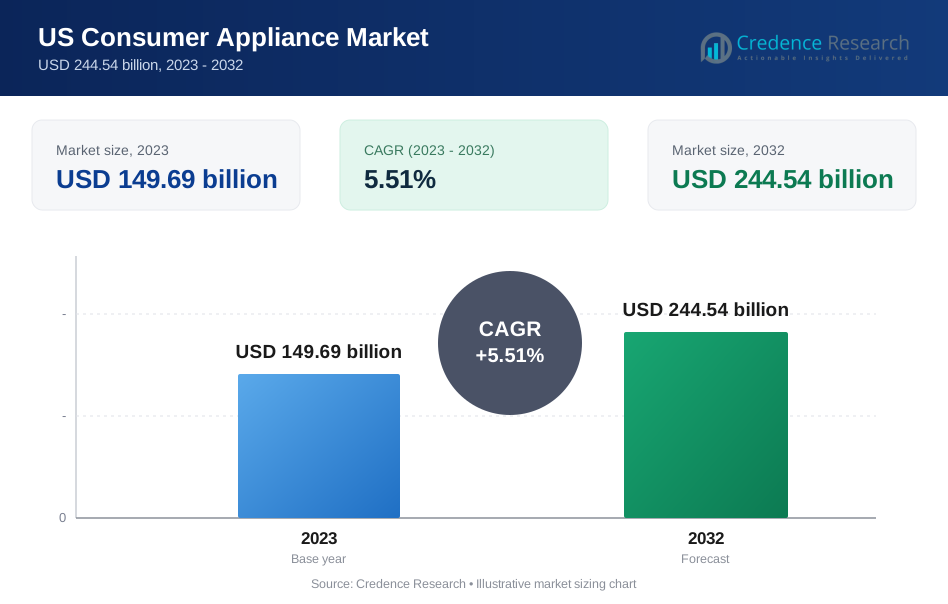
| US Consumer Appliance Market Size 2023 | USD 149.69 billion |
| US Consumer Appliance Market, CAGR | 5.51% |
| US Consumer Appliance Market Size 2032 | USD 244.54 billion |
Market Overview
The US Consumer Appliance Market is projected to grow from USD 149.69 billion in 2023 to an estimated USD 244.54 billion by 2032, reflecting a compound annual growth rate (CAGR) of 5.51% from 2024 to 2032. This robust growth trajectory is driven by increasing consumer demand for advanced and energy-efficient appliances, along with rising disposable incomes and a trend toward smart home integration.
Key drivers in the market include technological advancements, such as the integration of IoT in household appliances, which enhances convenience and efficiency for users. Additionally, the growing focus on sustainability and energy conservation has led to higher adoption rates of eco-friendly appliances, further propelling market growth.
Geographically, the US market is dominated by regions such as the Northeast and West Coast, where higher urbanization and disposable income levels drive significant demand. Key players in the market include industry leaders like Whirlpool Corporation, General Electric Company, and LG Electronics, who are continually innovating to maintain their competitive edge in this dynamic market.
Market Drivers
Technological Advancements and Smart Home Integration
The rapid pace of technological advancements is a significant driver of growth in the US consumer appliance market. The integration of smart technologies, particularly the Internet of Things (IoT), has revolutionized the way consumers interact with their household appliances. For instance, a survey by the Consumer Technology Association found that 69% of US households now own at least one smart home device, with smart appliances being among the fastest-growing categories. IoT-enabled devices, such as smart refrigerators, washing machines, and ovens, allow users to control and monitor their appliances remotely through smartphones or voice-activated assistants like Amazon Alexa or Google Assistant. This technological leap offers unparalleled convenience, energy efficiency, and enhanced functionality, making smart appliances increasingly popular among consumers. Additionally, the rise of connected homes, where multiple devices are interconnected and communicate with each other, has further accelerated the adoption of smart appliances.
Increasing Focus on Energy Efficiency and Sustainability
The growing emphasis on energy efficiency and sustainability is another critical driver of the US consumer appliance market. With rising awareness about environmental issues and the need to reduce carbon footprints, consumers are increasingly opting for energy-efficient appliances that consume less power and minimize environmental impact. For instance, a study by the American Council for an Energy-Efficient Economy (ACEEE) revealed that ENERGY STAR certified appliances can reduce energy consumption by up to 30% compared to standard models. Regulatory bodies such as the US Environmental Protection Agency (EPA) and the Department of Energy (DOE) have implemented stringent energy efficiency standards, such as the ENERGY STAR program, which certifies appliances that meet or exceed specific energy performance criteria. As a result, manufacturers are investing heavily in research and development to design and produce appliances that comply with these standards while delivering superior performance.
Rising Disposable Incomes and Urbanization
The US consumer appliance market is also driven by rising disposable incomes and increased urbanization. As the economy continues to grow, more households have higher disposable incomes, enabling them to invest in modern and high-quality appliances that enhance their lifestyle. For instance, data from the US Bureau of Economic Analysis showed that personal disposable income increased by 2.8% in 2023, contributing to higher consumer spending on durable goods, including appliances. Urbanization, particularly in metropolitan areas, has led to smaller living spaces, prompting consumers to seek appliances that are compact, multifunctional, and designed to optimize space utilization. Additionally, the rise in single-person households and dual-income families has increased the demand for appliances that offer convenience and time-saving features. For example, a survey by the National Association of Home Builders found that 86% of homebuyers consider a washer and dryer to be essential or desirable features in a new home, highlighting the importance of convenience-oriented appliances in modern households.
Evolving Consumer Preferences and Lifestyle Changes:
Changing consumer preferences and lifestyle trends are significant factors shaping the US consumer appliance market. The modern consumer is more informed, tech-savvy, and conscious of quality, design, and functionality. There is a growing preference for appliances that offer personalized experiences, cater to specific needs, and align with individual lifestyles. For instance, health-conscious consumers are driving the demand for kitchen appliances that support healthy cooking methods, such as air fryers, blenders, and juicers. Similarly, the increasing interest in home entertainment and leisure has boosted the market for appliances like home theater systems, smart TVs, and gaming consoles. The COVID-19 pandemic has also influenced consumer behavior, leading to a greater focus on home improvement and comfort. As people spent more time at home during lockdowns, there was a surge in demand for appliances that enhance home living, such as air purifiers, robotic vacuum cleaners, and advanced cooking appliances. This shift in consumer behavior is expected to persist, with continued demand for appliances that cater to evolving lifestyle needs and preferences.
Market Trends
Growing Adoption of Smart Appliances and Connected Ecosystems:
The US consumer appliance market is witnessing a significant trend towards the adoption of smart appliances, driven by advancements in technology and the increasing popularity of connected ecosystems. For instance, according to a survey by YouGov, 39% of US consumers now own at least one smart home device. Consumers are increasingly seeking appliances that offer more than just basic functionality, favoring devices that integrate with their digital lives. Smart appliances, such as refrigerators with built-in touchscreens, washing machines with remote operation capabilities, and ovens that can be controlled via smartphone apps, are becoming mainstream. These appliances not only offer convenience but also provide enhanced energy efficiency, personalized settings, and real-time monitoring and diagnostics. The growth of smart home ecosystems, where appliances and devices are interconnected and communicate seamlessly, further fuels this trend. For instance, a study by Parks Associates found that 36% of US broadband households own a smart home device. Companies like Samsung, LG, and Whirlpool are leading the charge by offering a wide range of smart appliances that can be integrated into smart home systems, catering to the growing consumer demand for connected living.
Increasing Emphasis on Sustainability and Eco-Friendly Products:
Sustainability has become a central theme in the US consumer appliance market, with both manufacturers and consumers placing greater emphasis on eco-friendly products. This trend is driven by heightened awareness of environmental issues and a stronger regulatory push towards energy efficiency. For instance, a survey by the Consumer Technology Association found that 61% of consumers consider energy efficiency an important factor when purchasing smart home devices. Consumers are increasingly choosing appliances that are ENERGY STAR certified, which guarantees that the products meet strict energy efficiency guidelines set by the US Environmental Protection Agency (EPA). In addition to energy efficiency, there is a growing demand for appliances made from sustainable materials and those that have a reduced carbon footprint. For example, manufacturers are exploring the use of recycled plastics and metals in the production of appliances, and there is an increased focus on developing products that consume less water and electricity. The trend towards sustainability is also reflected in the rising popularity of repairable and durable appliances, as consumers become more conscious of the environmental impact of disposable products. For instance, a study by the Electrical and Electronic Equipment Sustainability Council found that 77% of consumers would be willing to pay more for products that last longer. This shift towards sustainability is not only reshaping consumer preferences but is also driving innovation within the industry, as manufacturers strive to meet the growing demand for eco-friendly and sustainable appliances.
Market Restraints and Challenges
Supply Chain Disruptions and Rising Raw Material Costs:
The US consumer appliance market faces significant challenges due to ongoing supply chain disruptions and rising raw material costs. For instance, a survey by the National Association of Manufacturers found that 88% of manufacturers reported supply chain disruptions due to the COVID-19 pandemic. These disruptions have led to delays in production, increased lead times, and a scarcity of key components like semiconductors, which are crucial for smart appliances. Additionally, the cost of raw materials such as steel, copper, and plastics has surged, putting pressure on manufacturers to either absorb the costs or pass them on to consumers through higher prices. For example, the U.S. Bureau of Labor Statistics reported that the producer price index for steel mill products increased by 81.3% between August 2020 and August 2021. This situation not only impacts the profitability of manufacturers but also affects the affordability of consumer appliances, potentially slowing down market growth. The ongoing challenges in the supply chain highlight the need for manufacturers to diversify their sourcing strategies and invest in more resilient and localized supply chains to mitigate these risks.
Intense Market Competition and Price Sensitivity:
The US consumer appliance market is characterized by intense competition, with numerous players vying for market share in a crowded landscape. Established brands like Whirlpool, LG, and Samsung face stiff competition not only from each other but also from emerging players and low-cost manufacturers, particularly from Asia. This competitive environment leads to price wars, with companies striving to offer feature-rich products at competitive prices to attract consumers. For instance, a consumer survey by Statista found that 62% of US consumers consider price as the most important factor when purchasing household appliances. However, the high level of price sensitivity among consumers poses a challenge for manufacturers, as they must balance the need to offer innovative and high-quality products while keeping prices affordable. This pressure to maintain competitive pricing can limit profit margins and stifle innovation, as companies may be forced to cut costs in areas such as research and development. Moreover, the challenge of differentiating products in a market saturated with similar offerings makes it difficult for brands to stand out and secure customer loyalty. To overcome these challenges, companies must focus on building strong brand identities, investing in customer service, and leveraging emerging technologies to offer unique value propositions that resonate with consumers.
Market Segmentation Analysis
By Product Type
The consumer appliance market features several key segments, each driven by specific consumer needs and trends. Kitchen appliances, including refrigerators, ovens, dishwashers, and microwaves, dominate the market due to their essential role and growing preference for advanced features and energy efficiency. For instance, a recent industry survey indicates that smart refrigerators with AI-powered features are gaining significant traction among tech-savvy consumers. Small appliances, such as toasters, coffee makers, and blenders, are popular for their convenience and innovative, space-saving designs. Government data suggests that the small appliance segment has seen robust growth, particularly in urban areas where space optimization is crucial. Washing machines continue to see steady demand for both front-load and top-load models, driven by technological advancements and a focus on energy and water efficiency. A leading manufacturer's market research reveals that consumers are increasingly prioritizing eco-friendly washing machines with advanced water-saving technologies.Air purifiers are gaining traction due to increasing awareness of indoor air quality and health concerns, with advanced filtration technologies in high demand. Recent consumer surveys indicate a surge in air purifier sales, especially in regions with high pollution levels or allergy concerns. Water heaters and purifiers are growing in importance as consumers prioritize hygiene and effective water heating and purification solutions. Industry reports suggest that tankless water heaters are becoming increasingly popular due to their energy efficiency and space-saving design.
By End Use
The US consumer appliance market is segmented into several key areas, each driven by specific needs and requirements. The Domestic segment, the largest, focuses on household comfort and convenience, with growth fueled by innovations in smart and energy-efficient appliances. A recent government household survey indicates a significant increase in the adoption of smart home appliances across various demographics. The Professional segment, catering to offices and salons, emphasizes durability and efficiency to handle high usage demands. Industry data shows that commercial-grade appliances with extended warranties and service plans are particularly popular in this segment. In the Hotels sector, there is a strong demand for high-quality and reliable appliances to meet luxury and comfort standards. A hospitality industry report highlights the growing trend of hotels investing in high-end, energy-efficient appliances to enhance guest experience and reduce operational costs. Salon & Grooming Parlors require specialty appliances for personal care, reflecting a growing emphasis on grooming and aesthetics. Market research indicates a rising demand for professional-grade hair care appliances with advanced features like ionic technology and precision temperature control. The Cafeteria & Restaurants segment relies on professional-grade appliances like commercial refrigerators and ovens for efficiency and performance. Recent industry surveys show an increasing preference for multifunctional cooking appliances that can handle diverse menu offerings while optimizing kitchen space.
Segments
Based on Product Type
- Kitchen Appliances
- Small Appliances
- Washing Machines
- Air Purifiers
- Water Heaters
- Water Purifiers
- Cloth Dryers/Tumblers
- Air Conditioners
- Others
Based on End Use
- Domestic
- Professional
- Hotels
- Salon & Grooming Parlors
- Cafeteria & Restaurants
- Offices & Institutes
- Others
Based on Sales Channel
- Offline
- Organized Retailer
- Unorganized
- Online
- Company Direct Sales
- Independent Vendor/E-Commerce
Based on Region
- Northeast
- Midwest
- South
- West
Regional Analysis
Northeast (28%):
The Northeast region, encompassing states such as New York, New Jersey, and Massachusetts, holds a significant share of the consumer appliance market. This region benefits from a high concentration of urban areas with high disposable incomes, driving demand for advanced and premium appliances. For instance, a survey conducted by the Consumer Technology Association found that households in the Northeast are more likely to own smart home devices compared to other regions. The presence of major metropolitan areas like New York City and Boston contributes to higher sales of both high-end and smart appliances. Additionally, the Northeast's focus on sustainability and energy efficiency aligns with the growing consumer preference for eco-friendly products. The U.S. Energy Information Administration reported that Northeastern states have some of the highest adoption rates of ENERGY STAR certified appliances. The region's aging infrastructure and residential renovations also support steady demand for replacement appliances.
West (30%):
The West region, including states such as California, Washington, and Oregon, leads the market with the largest share. This region is characterized by its high population density, particularly in major cities like Los Angeles and San Francisco, and a strong emphasis on technological innovation and sustainability. The West's robust economy and affluent consumer base drive significant demand for smart appliances, energy-efficient products, and high-tech kitchen gadgets. For instance, a report by the California Energy Commission revealed that the state has the highest penetration of smart thermostats in the country. Furthermore, the region's diverse climate conditions, ranging from hot summers to varied weather patterns, influence the demand for air conditioners, heaters, and other climate control appliances. The National Oceanic and Atmospheric Administration data shows that Western states experience some of the most extreme temperature variations, contributing to higher sales of climate control appliances.
Key players
- Whirlpool Corporation
- General Electric (GE) Appliances
- Samsung Electronics Co., Ltd.
- Bosch Group
- LG Electronics Inc. (LG)
- Panasonic Corporation (Panasonic)
- Robert Bosch
Competitive Analysis
In the US consumer appliance market, key players such as Whirlpool Corporation, General Electric (GE) Appliances, and Samsung Electronics Co., Ltd. hold prominent positions due to their extensive product portfolios and strong brand recognition. Whirlpool and GE Appliances lead with a broad range of traditional and smart appliances, focusing on reliability and innovation. Samsung and LG emphasize cutting-edge technology and smart home integration, appealing to tech-savvy consumers with advanced features and IoT connectivity. Bosch and Robert Bosch are renowned for their high-quality, energy-efficient products, catering to premium market segments. Panasonic complements the competitive landscape with its emphasis on innovation and energy efficiency. Each player differentiates itself through technological advancements, product quality, and strategic market positioning, creating a dynamic and competitive environment.
Recent Developments
- In April 2024, Whirlpool Corporation completed a major transaction with Arçelik A.Ş, creating a new European appliance company called Beko Europe B.V. This transaction combines Whirlpool's European major domestic appliance business with Arcelik's appliance businesses. Whirlpool now owns 25% of Beko Europe B.V., while Arcelik owns 75%.
- In June 2024, reports emerged that German engineering group Robert Bosch is considering making an offer to acquire Whirlpool Corporation. While this is still speculative, it could potentially be a significant development in the appliance industry if it materializes.
Market Concentration and Characteristics
The US consumer appliance market exhibits moderate to high market concentration, dominated by a few major players including Whirlpool Corporation, General Electric (GE) Appliances, Samsung Electronics Co., Ltd., and LG Electronics Inc. These leading companies command significant market share due to their extensive product offerings, strong brand recognition, and continuous innovation in technology and energy efficiency. The market is characterized by a high degree of competition, with firms striving to differentiate themselves through smart home integration, eco-friendly solutions, and advanced features. This competitive landscape is further shaped by regional preferences, economic conditions, and shifting consumer demands for sustainable and technologically advanced appliances. As a result, the market is dynamic, with constant developments and strategic positioning by key players to capture and maintain market share.
Report Coverage
The research report offers an in-depth analysis based on Product Type, End Use, Sales Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The integration of advanced technologies, such as artificial intelligence and machine learning, will continue to drive innovation in consumer appliances, enhancing functionality and user experience.
- The demand for smart home systems will grow, with appliances increasingly incorporating IoT connectivity for seamless integration into smart home ecosystems and improved remote control capabilities.
- Rising consumer awareness and regulatory pressures will lead to a greater emphasis on energy-efficient appliances, with manufacturers focusing on developing products that reduce energy consumption and lower utility bills.
- Environmental sustainability will become a key focus, with an increased push for eco-friendly materials and manufacturing processes to meet growing consumer and regulatory demands for greener products.
- Expanding urbanization and rising disposable incomes in emerging markets, particularly in growing metropolitan areas, will drive demand for new and upgraded consumer appliances.
- Consumer preferences for personalized and customizable appliances will grow, leading manufacturers to offer more options for design, functionality, and features tailored to individual needs.
- Appliances that promote health and wellness, such as advanced air purifiers and water purifiers, will see increased demand as consumers become more health-conscious and prioritize indoor air and water quality.
- Online sales channels will continue to expand, with a growing number of consumers purchasing appliances through e-commerce platforms, necessitating improvements in online retail strategies and customer service.
- Intense competition among major players will drive continuous innovation while also exerting pressure on pricing, leading companies to balance advanced features with cost-effectiveness.
- Manufacturers will face ongoing challenges related to compliance with evolving regulations and standards for energy efficiency, safety, and environmental impact, requiring continuous adaptation and innovation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the US Consumer Appliance Market?
What are the key drivers of growth in the US Consumer Appliance Market?
Which regions dominate the US Consumer Appliance Market?
Who are the major players in the US Consumer Appliance Market?
How is the adoption of smart appliances impacting the market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 US Consumer Appliance Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global US Consumer Appliance Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 149.69 billion → 2032: USD 244.54 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 US Consumer Appliance Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. US Consumer Appliance Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 US Consumer Appliance Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 US Consumer Appliance Market Drivers
- 3.3 US Consumer Appliance Market Restraints & Challenges
- 3.4 US Consumer Appliance Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 US Consumer Appliance Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 US Consumer Appliance Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, US Consumer Appliance category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 US Consumer Appliance Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. US Consumer Appliance Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the US Consumer Appliance market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 US Consumer Appliance Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 US Consumer Appliance Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 US Consumer Appliance Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in US Consumer Appliance (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New US Consumer Appliance Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global US Consumer Appliance Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America US Consumer Appliance Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe US Consumer Appliance Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific US Consumer Appliance Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America US Consumer Appliance Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East US Consumer Appliance Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa US Consumer Appliance Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. US Consumer Appliance Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
