
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| U.S. Grid Modernization Market Size 2024 | USD 12,445.02 million |
| U.S. Grid Modernization Market, CAGR | 17.93% |
| U.S. Grid Modernization Market Size 2032 | USD 46,547.14 million |
Market Overview
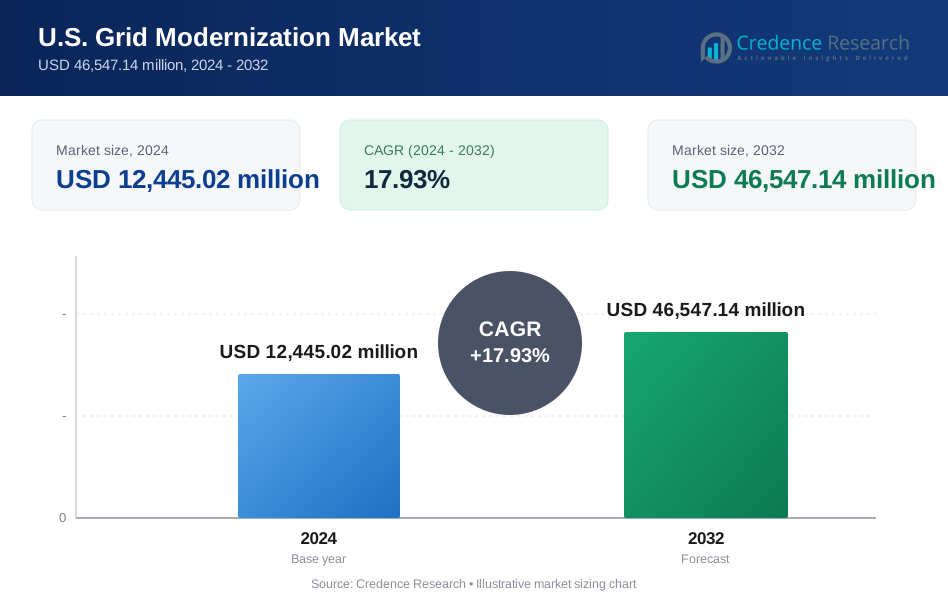
U.S. Grid Modernization market size was valued at USD 12,445.02 million in 2024 and is anticipated to reach USD 46,547.14 million by 2032, at a CAGR of 17.93% during the forecast period (2024-2032).
The U.S. Grid Modernization market is driven by the growing need for reliable, efficient, and resilient power grids to support increasing energy demand and the integration of renewable energy sources. Government initiatives and substantial investments are accelerating the modernization of the power infrastructure, enhancing grid flexibility, and reducing outages. Technological advancements such as smart grids, energy storage solutions, and automation are also contributing to market growth by enabling real-time monitoring, better energy distribution, and improved load management. Additionally, the shift towards decarbonization and sustainability is pushing utilities to adopt more innovative solutions, further propelling the adoption of grid modernization technologies. These trends are expected to drive significant market expansion, positioning the U.S. to meet future energy demands while optimizing grid operations and supporting environmental goals.
The U.S. Grid Modernization market is experiencing significant growth across various regions, each with distinct needs and challenges. Key players such as General Electric, Honeywell International, and Siemens USA are leading the charge in developing and implementing advanced grid technologies, including smart grids, energy storage, and automation systems. These companies are crucial in supporting the modernization of aging infrastructure and facilitating the integration of renewable energy sources. Other notable players like Schneider Electric USA and Eaton Corporation are contributing to enhancing grid resilience and efficiency through innovative solutions. Additionally, Itron, Inc., and S&C Electric Company are actively involved in deploying metering and grid management technologies. These companies, along with several others, are shaping the future of U.S. grid modernization, driving technological advancements, and helping utilities meet growing energy demands while ensuring sustainability and reliability. Their combined efforts are pivotal to transforming the U.S. power grid into a more resilient and efficient system.
Market Insights
- The U.S. Grid Modernization market was valued at USD 12,445.02 million in 2024 and is projected to reach USD 46,547.14 million by 2032, growing at a CAGR of 17.93% from 2024 to 2032.
- Increasing demand for renewable energy sources and the need for grid efficiency are major drivers of market growth.
- Smart grids, energy storage solutions, and advanced automation technologies are key trends shaping the market.
- Competitive players like General Electric, Siemens, and Schneider Electric are driving innovation in grid technologies.
- High capital costs and complex regulatory environments remain significant market restraints.
- Regional demand is led by the Western and Northeastern U.S., where clean energy integration and grid reliability are top priorities.
- The adoption of cybersecurity measures and real-time grid monitoring technologies is critical to ensuring the resilience and security of modernized grids.
Market Drivers
Government Investments and Policy Support
The U.S. government has been actively supporting grid modernization through various initiatives, including the Infrastructure Investment and Jobs Act (IIJA) and the Energy Policy Act. These policies provide funding and incentives for upgrading grid infrastructure, encouraging utilities to adopt advanced technologies. For instance, the State of New York was awarded ~$24 million from the Grid Resilience State and Tribal Formula Grant, with NYSERDA providing a cost share of ~$3.5 million. Additionally, state and federal regulations are pushing for increased grid reliability, security, and resilience, driving utilities to modernize their systems to comply with evolving standards and meet regulatory requirements.
Increasing Energy Demand and Load Management
The growing demand for electricity, driven by population growth and increased industrial activities, is a key driver of grid modernization in the U.S. Traditional grids are struggling to manage peak loads, leading to frequent outages and inefficiencies. For instance, the U.S. Energy Information Administration (EIA) has noted that total energy consumption by end-use sectors includes primary energy use, purchased electricity, and electrical system energy losses, highlighting the need for better load management. Grid modernization enables better load management by implementing real-time monitoring and advanced forecasting technologies. These innovations help balance supply and demand more efficiently, ensuring the grid can handle the increasing energy consumption without compromising reliability.
Integration of Renewable Energy Sources
As the U.S. transitions towards cleaner energy, the integration of renewable sources such as solar, wind, and hydro into the grid is essential. However, these energy sources are intermittent and require an upgraded grid infrastructure to handle fluctuations in energy supply. Grid modernization technologies, including smart grids and energy storage solutions, facilitate this integration by enabling better coordination and storage of renewable energy, reducing dependency on fossil fuels, and supporting sustainability goals.
Technological Advancements in Grid Management
Advancements in grid management technologies are playing a crucial role in the modernization process. The deployment of smart grid solutions, automation, and predictive analytics allows for real-time monitoring and faster response times during disruptions. Energy storage technologies, such as batteries, also support grid stability by storing excess energy generated during off-peak hours. These innovations are transforming the way grids are managed, improving efficiency, reducing downtime, and ensuring reliable electricity distribution across the U.S.
Market Trends
Adoption of Smart Grids
One of the most prominent trends in U.S. grid modernization is the widespread adoption of smart grids. These grids use digital communication technology to enable two-way communication between utilities and consumers. For instance, the U.S. Energy Information Administration (EIA) has noted that in 2022, U.S. electric utilities had about 119 million advanced (smart) metering infrastructure (AMI) installations, showcasing the significant adoption of smart grid technologies. Smart grids facilitate real-time data collection, enabling utilities to optimize energy distribution, detect faults, and enhance grid resilience. They also empower consumers to manage their energy consumption more effectively, leading to greater efficiency and cost savings. The growing focus on smart grid infrastructure is reshaping the energy landscape by providing more visibility and control over the grid’s operation.
Expansion of Energy Storage Solutions
Energy storage systems, particularly battery storage, are becoming increasingly integral to grid modernization efforts. These solutions allow for the storage of excess energy generated during off-peak periods and its redistribution when demand spikes. As renewable energy sources such as wind and solar are intermittent, energy storage helps stabilize the grid and ensure a constant energy supply. The rising demand for energy storage is driving significant investments in battery technologies, with advancements in efficiency, cost reduction, and scalability further boosting their adoption in grid modernization projects.
Increased Focus on Cybersecurity
With the increased digitalization of grid systems, the need for robust cybersecurity measures has become a key trend. The vulnerability of the U.S. power grid to cyber-attacks has prompted utilities to prioritize cybersecurity investments to safeguard critical infrastructure. Modernization efforts now include the implementation of advanced security protocols, including encryption, threat detection, and real-time monitoring. Ensuring the integrity and security of grid systems is essential to prevent disruptions and protect both consumers and utilities from potential cyber threats.
Emphasis on Sustainability and Decarbonization
Sustainability remains a driving force behind grid modernization, with utilities increasingly focused on decarbonization. The transition to cleaner energy sources, such as wind, solar, and hydro, is reshaping grid design to reduce greenhouse gas emissions. Grid modernization enables the seamless integration of these renewable energy sources, helping to achieve national and state-level decarbonization goals. Additionally, sustainability initiatives are pushing for energy-efficient technologies and practices that minimize the environmental impact of grid operations, fostering a cleaner, more resilient energy system.
Market Challenges Analysis
High Capital and Operational Costs
One of the significant challenges facing U.S. grid modernization is the high capital investment required for upgrading existing infrastructure. For instance, the National Council of State Legislatures estimates that the U.S. will have to spend up to $2 trillion on grid modernization by 2030 just to maintain the electric grid's reliability. The cost of implementing advanced technologies such as smart grids, energy storage systems, and grid automation is substantial. Utilities must not only invest in new equipment but also manage the operational costs associated with maintaining and integrating these systems. The financial burden can be particularly challenging for smaller utilities, which may lack the resources to fund large-scale grid modernization projects. As a result, securing funding, whether through government incentives or private investments, remains a critical challenge to achieving widespread grid modernization.
Regulatory and Coordination Complexities
Grid modernization involves coordination across multiple stakeholders, including utility companies, government agencies, and technology providers. However, the regulatory environment can be complex, with varying standards, policies, and incentives across federal, state, and local levels. This patchwork of regulations can slow down the adoption of new technologies and create confusion for stakeholders trying to navigate the legal landscape. Additionally, coordinating the integration of new systems into existing infrastructure without disrupting service or causing inefficiencies presents a significant challenge. Ensuring smooth collaboration and consistent regulatory frameworks is essential for overcoming these hurdles and achieving effective grid modernization at scale.
Market Opportunities
The U.S. Grid Modernization market presents significant opportunities, particularly in the integration of renewable energy sources and the development of energy storage systems. As the demand for cleaner energy increases, utilities are seeking solutions that enable the smooth integration of intermittent renewable resources such as solar and wind into the existing grid infrastructure. The growing emphasis on sustainability provides opportunities for companies involved in renewable energy technologies, grid storage solutions, and smart grid systems to capitalize on this shift. The expansion of energy storage technologies, such as advanced battery systems, can help stabilize the grid and reduce reliance on fossil fuels, positioning these companies at the forefront of grid modernization efforts.
Additionally, the U.S. government's commitment to infrastructure investments, particularly through initiatives like the Infrastructure Investment and Jobs Act, presents a wealth of opportunities for stakeholders in the grid modernization sector. These investments support the development and deployment of smart grid technologies, grid automation, and advanced cybersecurity measures. As utilities increasingly prioritize resilience and security, opportunities arise for cybersecurity firms and technology providers offering innovative solutions to protect the grid from cyber threats. Moreover, the growing need for energy efficiency across industries presents opportunities for energy management and automation companies, offering products and services that help optimize grid performance while reducing operational costs. With a supportive regulatory environment and continued technological advancements, the U.S. grid modernization market is poised for substantial growth and innovation.
Market Segmentation Analysis:
By Component:
The U.S. Grid Modernization market is segmented into three key components: hardware, software, and services. Hardware dominates the market, encompassing advanced technologies such as smart meters, energy storage systems, grid automation equipment, and substations. These hardware components enable real-time monitoring, energy distribution, and load management, all of which are essential for modernizing the grid infrastructure. Software solutions, including grid management systems, analytics platforms, and cybersecurity tools, are also gaining significant traction. These software tools optimize grid performance, enhance security, and improve decision-making processes. Lastly, the services segment, which includes consulting, implementation, and maintenance, plays a critical role in ensuring the successful deployment and ongoing operation of grid modernization projects. As utilities continue to adopt more complex and integrated systems, demand for all three segments will continue to grow, driving the overall market forward.
By Application:
The U.S. Grid Modernization market is further segmented based on application, with three primary categories: residential, commercial, and industrial. The residential segment focuses on integrating smart grid technologies to improve energy efficiency, reduce costs, and enhance reliability for consumers. Commercial applications involve larger-scale energy management solutions that enable businesses to optimize their energy use, enhance operational efficiency, and reduce carbon footprints. The industrial segment, which represents a significant portion of grid modernization, includes energy-intensive sectors that require advanced grid management to ensure continuous operations and prevent disruptions. As the demand for reliable, efficient, and sustainable energy solutions grows across all sectors, these applications will drive substantial growth in the market.
Segments:
Based on Component:
- Hardware
- Software
- Services
Based on Application:
- Residential
- Commercial
- Industrial
Based on End-User:
- Utilities
- Independent Power Producers (IPPs)
- Government and Municipalities
Based on the Geography:
- Western United States
- Midwestern United States
- Southern United States
- Northeastern United States
Regional Analysis
Western United States
The Western United States holds a significant market share of approximately 30%. This region's grid modernization efforts are largely driven by the increasing demand for renewable energy sources such as wind and solar, which necessitate grid upgrades to manage intermittency. States like California and Nevada are leading the charge with strong state policies supporting clean energy integration and grid resilience. The Western U.S. is also focusing on advanced energy storage solutions and smart grid technologies to optimize energy distribution and reduce dependence on fossil fuels, making it a pivotal region for grid modernization.
Northeastern United States
The Northeastern United States follows with a market share of around 25%. This region's grid modernization efforts are primarily driven by the need to upgrade aging infrastructure and enhance grid reliability. With dense populations and high energy consumption, the Northeast requires robust systems to manage energy distribution and prevent outages. States like New York and Massachusetts have set ambitious goals for reducing carbon emissions, leading to increased investments in grid modernization technologies, such as smart meters and advanced grid management systems. The focus in this region is on improving grid resilience to severe weather conditions and integrating renewable energy sources efficiently.
Midwestern United States
In the Midwestern United States, which holds a market share of approximately 20%, grid modernization is driven by a combination of aging infrastructure and a growing push for sustainability. The Midwest, with its significant agricultural and industrial sectors, is seeking solutions to improve energy efficiency and integrate renewable resources. States like Illinois and Michigan are investing heavily in upgrading grid systems to handle renewable energy integration while ensuring that energy-intensive industries remain efficient and cost-effective. This region also sees considerable investments in energy storage systems to balance supply and demand, especially with the increasing role of wind energy.
Southern United States
The Southern United States accounts for around 25% of the U.S. Grid Modernization market share. With a diverse energy mix and rapid population growth, the South is focusing on upgrading grid infrastructure to meet rising electricity demands. States like Texas and Florida are leading in grid modernization initiatives, driven by the need to enhance grid resilience, improve energy security, and accommodate the growing use of renewable energy sources. The Southern U.S. is also investing in smart grid technologies to improve grid efficiency and integrate distributed energy resources, which is expected to contribute to the region's continued growth in the grid modernization market.
Key Player Analysis
- General Electric
- Honeywell International Inc.
- Cisco Systems, Inc.
- Eaton Corporation
- IBM Corporation
- Itron, Inc.
- Siemens USA
- Schneider Electric USA
- S&C Electric Company
- Mitsubishi Electric
Competitive Analysis
The U.S. Grid Modernization market is highly competitive, with several leading players driving innovation in grid infrastructure and technology. General Electric, Honeywell International, Cisco Systems, Eaton Corporation, IBM Corporation, Itron, Inc., Siemens USA, Schneider Electric USA, S&C Electric Company, and Mitsubishi Electric are at the forefront of this market, each contributing advanced solutions to modernize and enhance grid systems. Companies are increasingly focusing on smart grid technologies, automation, and energy storage systems to improve the reliability and flexibility of the grid. Many players are also investing heavily in cybersecurity measures to protect modernized grids from potential threats, as the digitalization of energy systems increases the risk of cyberattacks. Furthermore, partnerships and collaborations are playing a significant role in driving innovation, as companies work together to develop advanced grid solutions and address the challenges posed by aging infrastructure. For example, the California Energy Commission approved incentives for virtual power plants, demonstrating the collaborative efforts between utilities and regulators to integrate new technologies into the grid. The competition is also shaped by the demand for real-time data analytics, which enables utilities to monitor and optimize energy distribution more effectively. As the market continues to evolve, companies are adopting new business strategies, such as expanding product portfolios and targeting emerging applications, to capture a larger share of the growing grid modernization market. This intense competition is expected to fuel further technological advancements and accelerate the transformation of the U.S. energy grid.
Recent Developments
- In October 2024, Hitachi Energy introduced Grid-enSure in India to advance the country's transition to sustainable energy. The company also announced plans to invest around INR 2,000 crore over the next four to five years in capacity expansion and upgrades for various transformer factories.
- In August 2024, Hitachi Energy called for urgent action to expand global power grids, reduce connection bottlenecks, and accelerate the energy transition. They launched Grid-enSure™ at the CIGRE 2024 Paris Session, a portfolio of solutions to enhance grid flexibility, resilience, and stability.
- In May 2024, Siemens revealed the Gridscale X software, a "co-pilot" for flexible low voltage grid management, aiming to reduce outages by up to 30%.
Market Concentration & Characteristics
The U.S. Grid Modernization market exhibits moderate to high concentration, with several large players dominating the industry while smaller, specialized firms contribute to niche areas of innovation. Key players such as General Electric, Siemens USA, Honeywell International, and Schneider Electric USA lead the market by offering comprehensive solutions, including smart grids, automation systems, energy storage, and grid management technologies. These companies possess strong market presence due to their vast product portfolios, technological expertise, and significant investment in research and development. Despite the dominance of these major players, the market also sees a diverse mix of smaller firms that provide specialized solutions like advanced metering, cybersecurity, and energy efficiency tools. The characteristics of this market reflect rapid technological advancements, with a growing emphasis on digitization and integration of renewable energy sources. The increasing complexity of grid systems demands more advanced solutions, driving innovation in automation, data analytics, and real-time monitoring. Additionally, market participants are increasingly adopting business strategies focused on sustainability, resilience, and energy efficiency. The demand for smart grids and energy storage solutions continues to rise, and companies are leveraging strategic partnerships and collaborations to enhance their offerings and address the evolving needs of the energy sector. This dynamic environment makes the U.S. Grid Modernization market highly competitive yet collaborative in nature.
Report Coverage
The research report offers an in-depth analysis based on Component, Application, End-User, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The U.S. Grid Modernization market is expected to grow significantly, driven by the increasing demand for renewable energy integration and grid efficiency.
- Smart grid technologies will continue to evolve, offering improved real-time monitoring, automation, and data analytics capabilities.
- Energy storage systems will play a crucial role in stabilizing the grid and balancing supply and demand, especially with the growing share of renewable energy.
- Cybersecurity will remain a top priority, with increasing investments in protecting grid infrastructure from potential cyber threats.
- Utilities will increasingly focus on grid resilience to withstand natural disasters and unexpected disruptions, leading to higher adoption of advanced grid management solutions.
- The role of artificial intelligence and machine learning will expand in grid optimization, enhancing predictive maintenance and energy forecasting.
- Electric vehicles will drive further demand for grid upgrades to accommodate increased charging infrastructure and manage additional power loads.
- Federal and state-level policies will continue to provide financial incentives and regulatory support, accelerating grid modernization projects.
- Strategic collaborations and partnerships between technology providers and utility companies will become more common to foster innovation and reduce deployment costs.
- The integration of distributed energy resources (DERs) will be a key focus area, requiring advanced grid solutions to manage the decentralized energy generation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Government Investments and Policy Support
Federal and state initiatives, such as the Infrastructure Investment and Jobs Act, are providing substantial funding and regulatory incentives for utilities to upgrade grid infrastructure, accelerating the adoption of advanced grid technologies.
Integration of Renewable Energy Sources
The increasing share of intermittent renewable energy like solar and wind is driving the need for grid modernization technologies, such as smart grids and energy storage, to ensure reliable integration and efficient energy distribution.
Technological Advancements in Grid Management
Innovations in smart grid solutions, automation, and predictive analytics are enabling real-time monitoring, faster response to disruptions, and improved load management, making the grid more efficient and resilient.
Rising Energy Demand and Load Management Needs
Population growth and industrial expansion are increasing electricity demand, necessitating modernized grids that can handle peak loads, reduce outages, and optimize energy flow through advanced management systems.
Emphasis on Cybersecurity and Grid Resilience
As grid systems become more digitalized, utilities are prioritizing cybersecurity investments and resilience measures to protect critical infrastructure from cyber threats and natural disasters, further driving modernization efforts.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the U.S. Grid Modernization market?
What factors are driving the growth of the U.S. Grid Modernization market?
What are the key segments within the U.S. Grid Modernization market?
What are some challenges faced by the U.S. Grid Modernization market?
Who are the major players in the U.S. Grid Modernization market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Utilities
- 1.2.2 Independent Power Producers (IPPs)
- 1.2.3 Government and Municipalities
- 1.3 By Component
- 1.3.1 Hardware
- 1.3.2 Software
- 1.3.3 Services
- 1.4 By Application
- 1.4.1 Residential
- 1.4.2 Commercial
- 1.4.3 Industrial
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12,445.02 million → 2032: USD 46,547.14 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Grid Modernization Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Grid Modernization Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. Grid Modernization Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. Grid Modernization Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Grid Modernization Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Grid Modernization Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Grid Modernization Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Grid Modernization Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12,445.02 million → 2032: USD 46,547.14 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Grid Modernization Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Utilities
- 12.3.7.2 Independent Power Producers (IPPs)
- 12.3.7.3 Government and Municipalities
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hardware
- 12.4.7.2 Software
- 12.4.7.3 Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Residential
- 12.5.7.2 Commercial
- 12.5.7.3 Industrial
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Grid Modernization End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 U.S. Grid Modernization Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 U.S. Grid Modernization Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 U.S. Grid Modernization Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 General Electric
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Honeywell International Inc.
- 18.4 Cisco Systems, Inc.
- 18.5 Eaton Corporation
- 18.6 IBM Corporation
- 18.7 Itron, Inc.
- 18.8 Siemens USA
- 18.9 Schneider Electric USA
- 18.10 S&C Electric Company
- 18.11 Mitsubishi Electric
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
