
Korean skincare moves from niche imports to mass retail
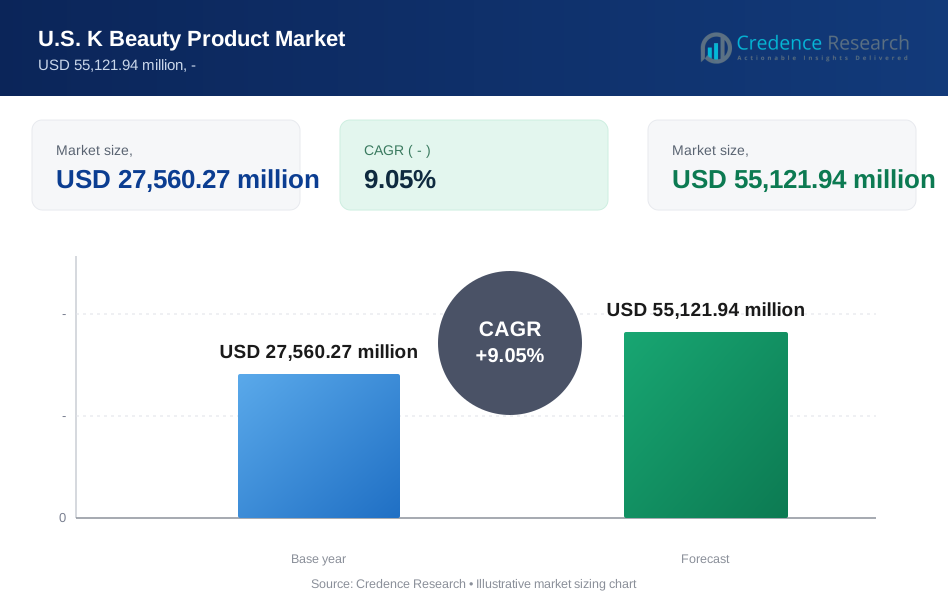
The U.S. K beauty product market was valued at USD 3.60 billion in 2025 and is projected to increase from USD 4.50 billion in 2026 to USD 9.81 billion by 2035, registering a CAGR of 9.05% during 2026–2035. Demand comes from shoppers who buy Korean serums, toners, moisturizers, cleansers and sunscreens for barrier repair, hydration and pore care at prices below most prestige Western skincare. The West held the largest regional share, 37.0% in 2025, because California anchors the largest Korean American community and the first Korean beauty chain stores. The South is the fastest-growing region at 9.7% a year, as national chains carry Korean ranges into Texas, Georgia and Virginia. The main commercial change is the move from online discovery to physical shelves, with Korean brands entering specialty chains, mass merchants and warehouse clubs during 2025 and 2026.
What do American shoppers buy when they buy Korean skincare?
The report counts retail sales in the United States of skincare and hair care products sold under Korean-owned or Korean-origin brands, whether made in Korea or in U.S. plants for those brands. Skin care accounted for USD 8.54 billion, or nearly three-quarters, of all Korean cosmetics exports in 2025, according to the Ministry of Food and Drug Safety, and the U.S. product mix follows the same pattern, led by serums, essences, toner pads and moisturizers. Credence Research models 2026 as a one-time step above the trend rate, because early-2026 import momentum ran far ahead of the long-run pace set for 2027 to 2035.
Korean factories also make products for American-owned brands, and those goods are excluded from the market value even when they ship from Korea. Professional salon treatments, devices and color cosmetics sold alone fall outside the main product groups, although lip and base products of Korean skincare brands sit in the others category. The value chain runs from Korean brand owners and contract makers through U.S. importers and distributors to marketplaces, specialty chains, mass merchants and Korean grocery stores.
U.S. K Beauty Product Market Insights
- The market reached USD 3.60 billion in 2025, steps up once to USD 4.50 billion in 2026 and should reach USD 9.81 billion by 2035 at a 9.05% CAGR.
- Korean cosmetics shipments to the United States rose 15.1% to USD 2.19 billion in 2025, making the country the top destination for the first time.
- Online channels led with 58.0% of 2025 value, as Medicube sales on Amazon rose 432% in 2025, according to APR.
- The FDA added bemotrizinol to the U.S. sunscreen monograph on June 9, 2026, the first new sunscreen active ingredient in about 20 years.
- Olive Young opened its first U.S. store in Pasadena on May 29, 2026, and plans five more California stores by the first half of 2027.
Serums lead while sunscreens grow fastest
Why do serums and essences lead the product mix?
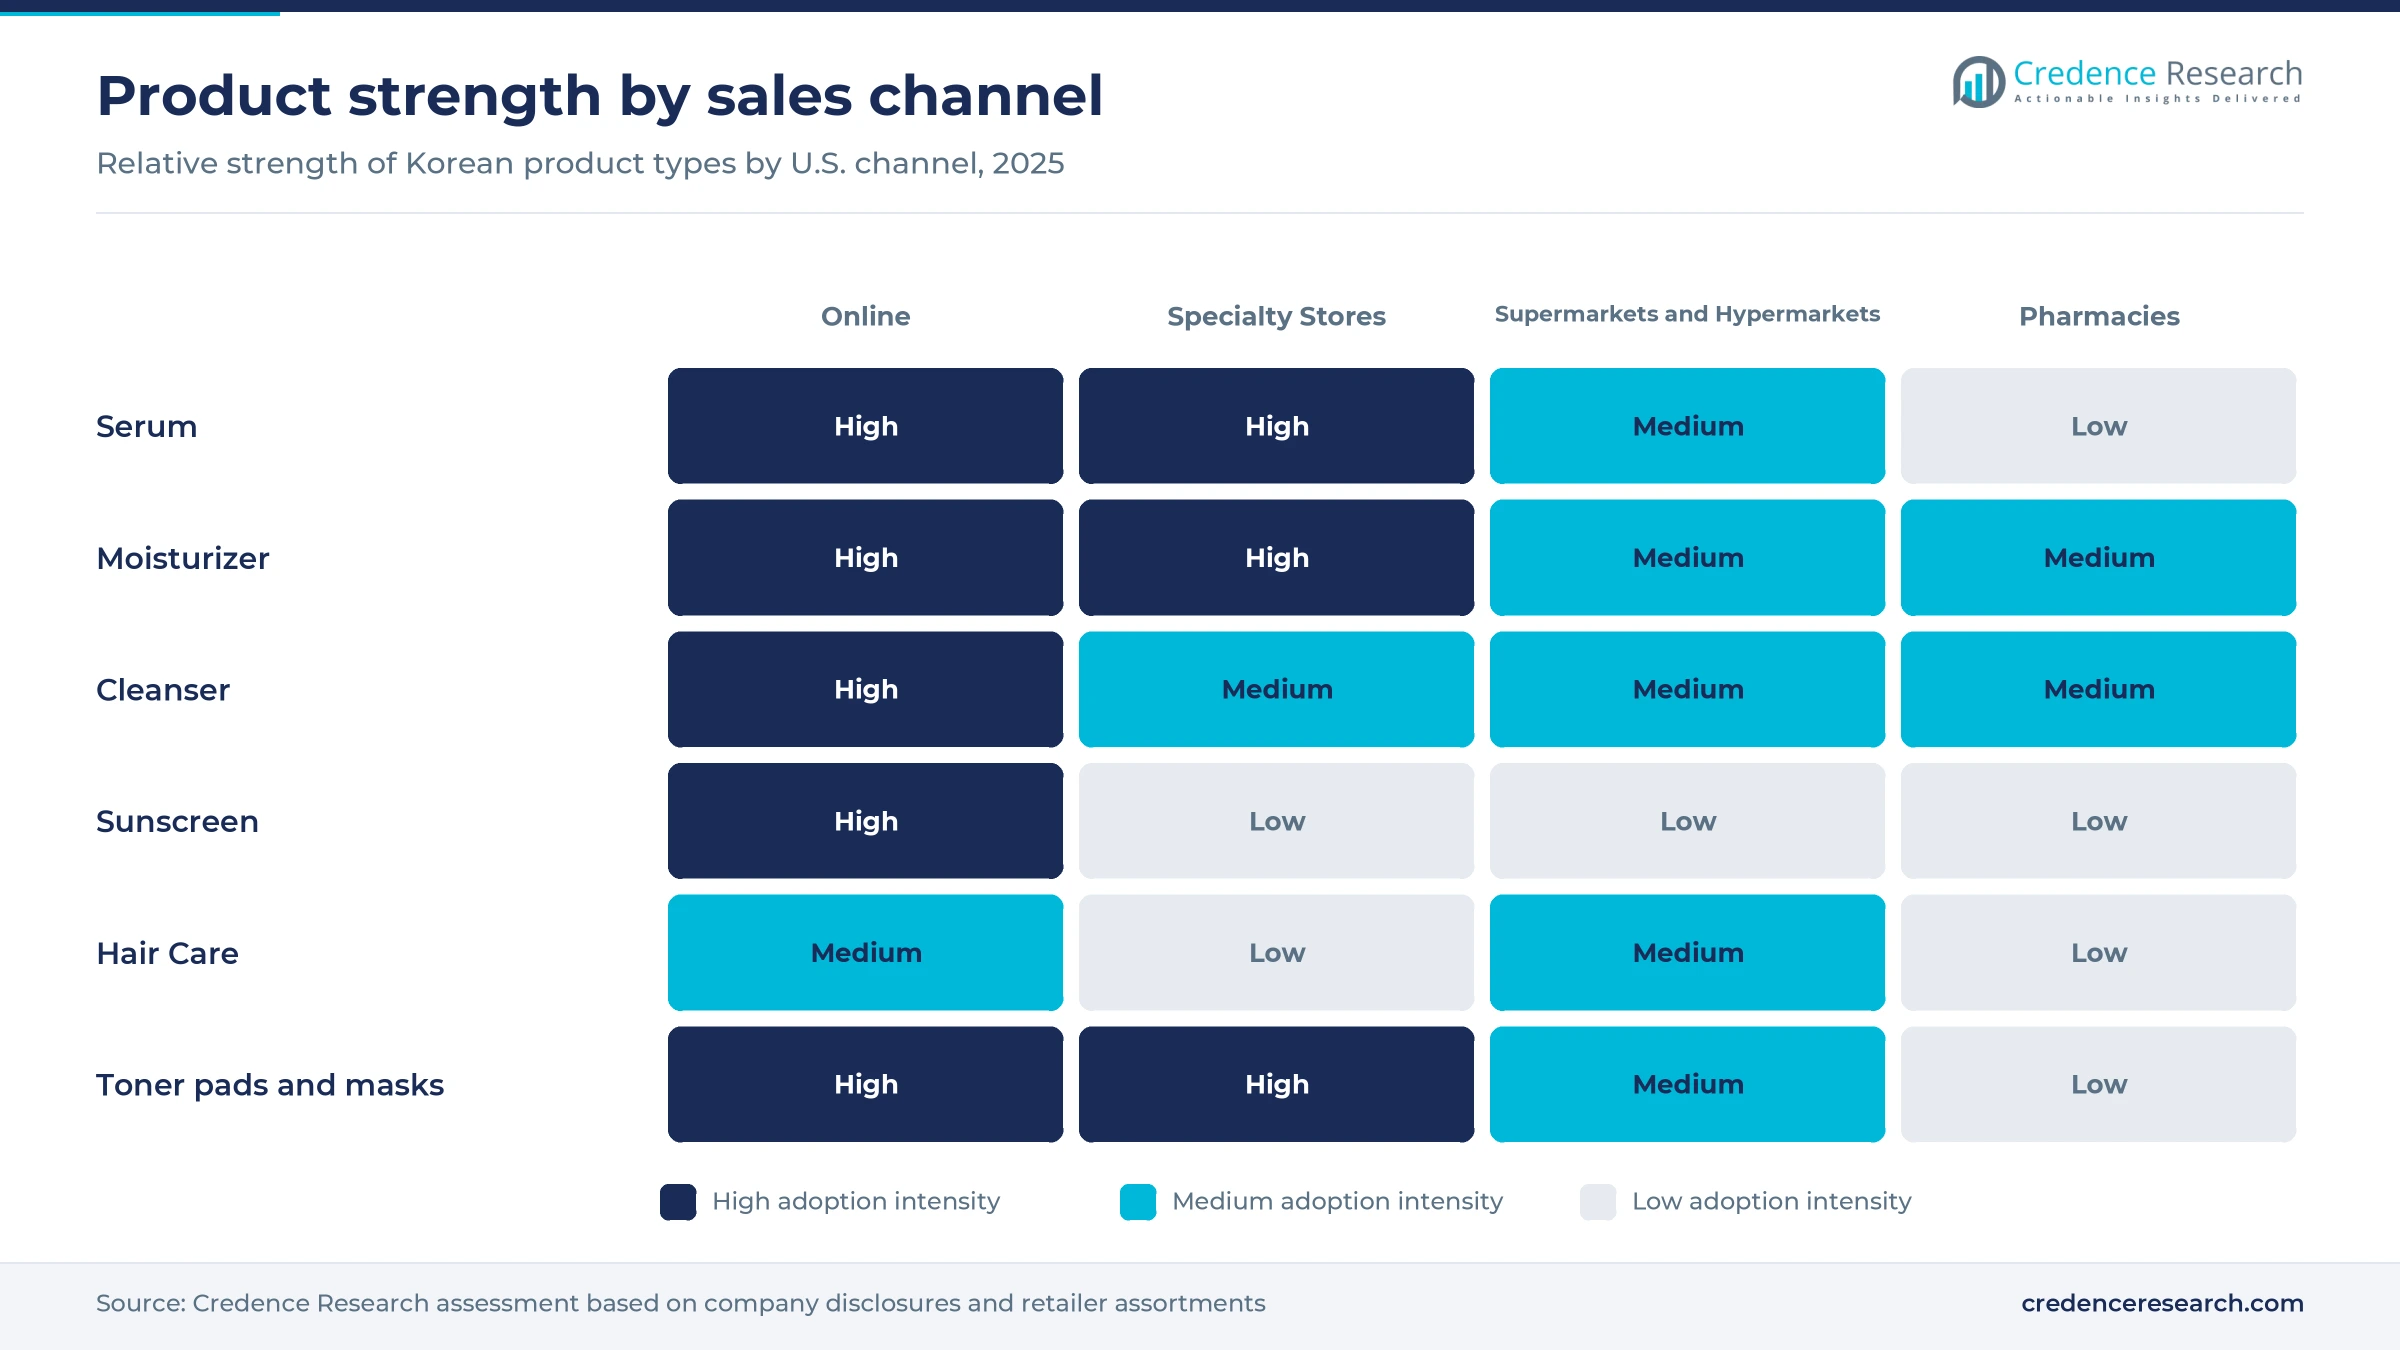
Based on product, the market is categorized into cleanser, moisturizer, serum, sunscreen, hair care and others. Serum led with 25.0% of 2025 value because concentrated essences and ampoules carry the active ingredients that define Korean routines, and Amorepacific said solid sales of the COSRX The Peptide line supported its 20% Americas growth in 2025. Sunscreen grows fastest at 10.9% a year, as Kolmar Korea equipped its new Pennsylvania plant with sunscreen lines in July 2025, giving Korean brands a U.S. route for formulas that must meet American over-the-counter drug rules.
Why do women account for most purchases?
Based on end user, the market is categorized into women and men. Women led with 79.0% of 2025 value because multi-step hydration, lip and eye care routines remain female-led, and Amorepacific cited strong demand for Laneige lip products in the Americas in 2025. Men grow fastest at 10.0% a year, as pore and oil-control formats sell without gendered packaging, and the Medicube Zero Pore Pad has ranked first in U.S. Amazon facial toners since February 2025. No public U.S. data split K-beauty sales by gender, so both shares are Credence Research estimates.
Why does online selling still dominate?
Based on distribution channel, the market is categorized into supermarkets and hypermarkets, specialty stores, online, pharmacies and others. Online led with 58.0% of 2025 value because Amazon, brand sites and TikTok Shop let small Korean brands reach buyers without a distributor, and Medicube beauty sales on Amazon rose 432% in 2025, according to APR. Supermarkets and Hypermarkets grow fastest at 11.1% a year, as Target began rolling out a Beauty Studio format built around Korean brands to more than 600 stores in September 2026, The Korea Herald reported.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product | Serum | 25.0% | Sunscreen | 10.9% |
| By End User | Women | 79.0% | Men | 10.0% |
| By Distribution Channel | Online | 58.0% | Supermarkets and Hypermarkets | 11.1% |
Korean serums sell below prestige prices
Korean brands price most hero items between USD 10 and USD 30, below prestige Western skincare and close to premium drugstore lines. Size ladders let shoppers trial a 30 mL bottle before buying the full size, which supports repeat purchases. Brand owners set list prices on their U.S. sites, while marketplaces and chains run frequent discounts around Amazon events and seasonal sales. The import duty noted in the challenges pushes brands to raise prices on Korean-made items or move production to U.S. contract plants. Brands with U.S. stock hold prices more steadily than cross-border sellers.
| Offer or segment | Typical price or fee | Basis |
|---|---|---|
| COSRX Advanced Snail 96 Mucin Power Essence | USD 9.99 for 30 mL, USD 25 for 100 mL | COSRX U.S. site, November 2026 |
| Laneige Lip Sleeping Mask | USD 24–25 per jar | Laneige U.S. site, November 2026 |
| COSRX The Peptide Collagen Hydrogel Eye Patch | USD 23 single, USD 41.40 for a 2-pack | COSRX U.S. site, November 2026 |
| Olive Young U.S. online store | Free shipping on orders above USD 35 | CJ Olive Young, May 2026 |
| Typical hero serum or toner, mass and specialty chains | About USD 15–30 per item | Credence Research estimate from brand list prices |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Record shipments and shelf access lift U.S. demand
Korean shipments to the United States hit records
American demand now pulls more Korean beauty exports than any other country. Korean cosmetics shipments to the United States rose 15.1% to USD 2.19 billion in 2025, making the country the top destination for the first time, according to Ministry of Food and Drug Safety data reported by The Korea Herald. Shipments had jumped 57% to about USD 1.9 billion in 2024, The Korea Herald reported, and they rose another 41.5% to USD 1.45 billion in the first half of 2026, according to Personal Care Insights citing Ministry of Food and Drug Safety data. That first-half pace explains the one-time step from USD 3.60 billion in 2025 to USD 4.50 billion in 2026, before growth settles at a 9.05% annual rate. Rising reorders favor brands with U.S. warehouses, while parcel shippers carry more cost and delivery risk.
Specialty chains open national shelf space
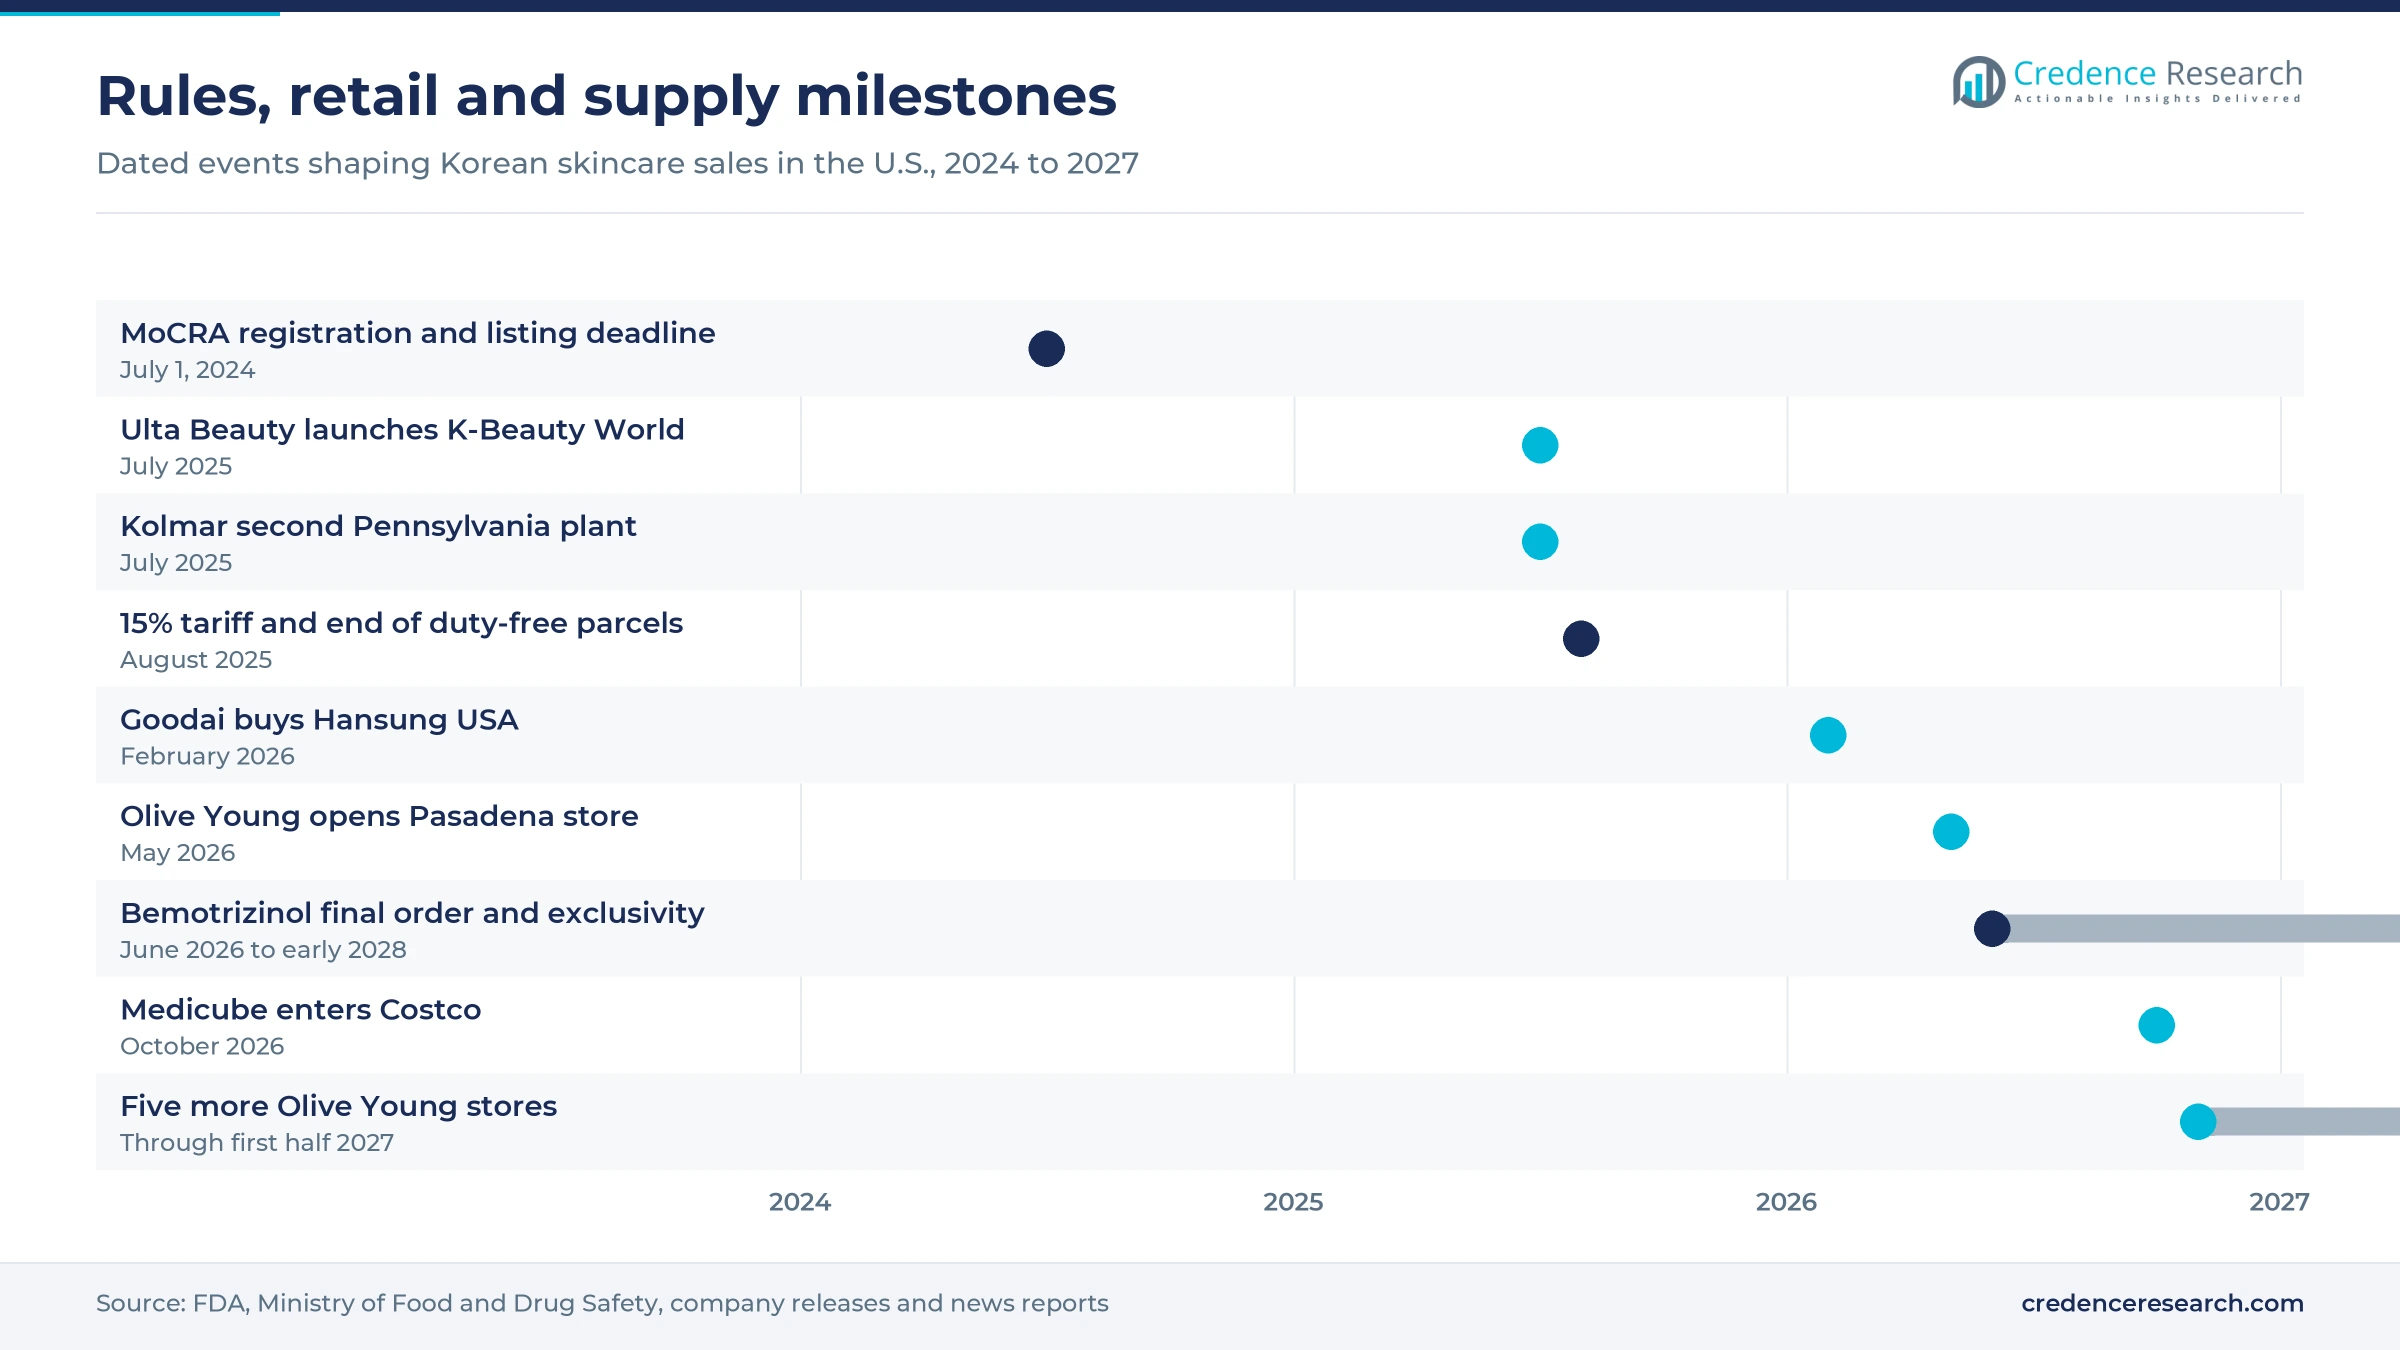
Specialty beauty chains have turned Korean skincare from an online search into an aisle that shoppers can test in person. Ulta Beauty launched K-Beauty World, a curated platform run with Landing International, in stores and online in July 2025 with more than 200 skincare and color products, Retail TouchPoints reported. Anua, owned by The Founders, reached 1,400 Ulta Beauty stores on Feb. 2, 2025, after building demand on social video. Amorepacific named Sephora, Amazon and TikTok Shop as its main U.S. channels in its second-quarter 2026 results. Wider shelf access lowers the cost of trial for new buyers, but it also forces brands to fund testers, displays and retailer promotions.
U.S. plants cut tariff and lead-time exposure
Local manufacturing lets Korean brands keep U.S. shelves stocked while avoiding the import costs and shipping delays that hit goods made in Korea. Kolmar Korea began operating its second Pennsylvania plant in Scott Township in July 2025, raising its U.S. capacity from 180 million to 300 million units a year, The Korea Times reported. The new plant has lines for makeup, basic skincare and sunscreen, and North American capacity, including Ontario, exceeds 470 million units. Brands that move fast-selling items to U.S. contract lines gain margin and shorter replenishment cycles, while smaller brands without U.S. production stay exposed to the import duty described in the challenges.
Korean groups extend more brands into America
Large Korean groups are adding brands to the U.S. portfolio, which multiplies the number of products competing for each shopper. Amorepacific reported 20% Americas revenue growth in 2025, driven by Laneige lip and skincare products, COSRX and new launches of Aestura and Hanyul. In the second quarter of 2026 the group also introduced IOPE and Illiyoon to American buyers. LG Household & Health Care set restructuring, Amazon growth and wider physical retail as its 2025 North American priorities for Belif, The Face Shop and CNP. More brands per group raise marketing efficiency, but they also intensify competition inside the same retail bays.
Flagship stores, clinical actives and new sun filters
Shift from online discovery to Korean flagship stores
Korean retailers are shifting from cross-border websites toward physical stores in the United States to capture shoppers who want to test textures before buying. Olive Young opened its first U.S. store, an 8,647-square-foot site in Pasadena, on May 29, 2026, with about 400 brands and 5,000 items at launch. It opened a second store in Century City on June 13, 2026, and launched a U.S. online store with free shipping on orders above USD 35. The company plans to move from the West Coast to New York and then to Southern and Central regions. Smaller Korean brands gain a curated shelf that national chains rarely offer, while specialty chains face a direct competitor.
Rise of clinical actives such as peptides and PDRN
Product development is shifting toward clinic-style actives, including peptides, polydeoxyribonucleotide and dermatology positioning, to meet buyers who compare ingredient lists. Amorepacific credited the COSRX The Peptide line among its 2025 Americas growth drivers, and the COSRX U.S. site lists a peptide collagen hydrogel eye patch at USD 23. APR said it would add Medicube PDRN products after its launch in about 400 Costco stores, The Korea Times reported in October 2026. Dr.G entered the U.S. through Amazon in April 2026 with dermatology-led hydration and exfoliation skincare, MedEsthetics reported. Amorepacific said its dermatology brand Aestura posted sales growth of more than 100% in the Americas in the second quarter of 2026. Brands with clinical data gain pricing power, while plain moisturizers face more pressure.
Opportunity in U.S.-compliant Korean sunscreens
Sunscreen is the clearest product gap, because many popular Korean sun creams cannot be sold in the U.S. in their home formulas. The U.S. Food and Drug Administration issued a final order adding bemotrizinol to the over-the-counter sunscreen monograph on June 9, 2026, about seven months after its December 2025 proposal. The rule took effect on Aug. 9, 2026, with 18 months of exclusivity for DSM-Firmenich and its licensees, The Korea Herald reported. Brands that license the filter and fill in FDA-registered plants can offer lighter ceramide sunscreens and daily SPF moisturizers to buyers who now order Korean versions from abroad.
Opportunity in Korean hair and body care
Hair and body care give Korean brands a second basket, because shoppers who trust their facial products try scalp serums, shampoos and body washes from the same labels. Korea's body cleansing exports to all markets rose 27.3% to USD 590 million in 2025, faster than skin care at 11.6%, Ministry of Food and Drug Safety data show, a sign that brands are widening ranges beyond facial care. Amorepacific said its Mise-en-Scene Perfect Serum ranked first in hair styling oil during the Amazon Black Friday event in 2025, and its Ryo hair-loss brand performed well in North America. Brands that bundle scalp care with facial routines can lift basket size at low acquisition cost.
Tariffs, sunscreen rules and crowded shelves
A 15% tariff and the end of duty-free parcels
Import costs rose sharply in 2025 and remain the main pressure on margins for Korean-made goods. A 15% U.S. tariff on Korean goods took effect on Aug. 7, 2025, and the duty-free treatment of parcels worth less than USD 800 ended on Aug. 29, 2025, Marie Claire reported. Cross-border sellers and small brands that shipped single orders from Korea are most exposed, because each parcel now pays duty or fees. Larger brands with U.S. stock or U.S. production absorb the cost more easily.
Drug rules force separate U.S. sunscreen formulas
U.S. law treats sunscreen as an over-the-counter drug, so most Korean sun products need new formulas, testing and registration before entering American stores. Even after bemotrizinol, the U.S. allows 17 sunscreen active ingredients against 31 permitted in Korea, The Korea Herald reported in July 2026. Filters such as ethylhexyl triazone remain unapproved, so a direct export of a popular Korean formula is still not possible. Small brands without U.S. drug development budgets are most exposed.
Registration and listing duties raise compliance costs
Federal cosmetic rules now require every brand to document its facilities and products, which adds fixed cost for small exporters. Under the Modernization of Cosmetics Regulation Act, the FDA set July 1, 2024, as the deadline for manufacturers to register facilities and for responsible persons to list each marketed product with its ingredients. Brands with hundreds of items and frequent launches carry the heaviest listing workload. Distributors that handle compliance for several brands gain a service role, while one-product brands face higher costs per item.
Crowded shelves raise promotion and listing costs
Shelf space for Korean skincare is growing, but the number of brands seeking it grows faster, which raises listing and promotion costs. Ulta Beauty added 13 new Korean brands in 2025, and Sephora doubled its Korean product lineup, Personal Care Insights reported in July 2025. Every new brand competes for the same end caps and testers, so slow-selling lines risk losing space at the next shelf reset. Brands without a hero product or strong social video traffic are most exposed to delisting.
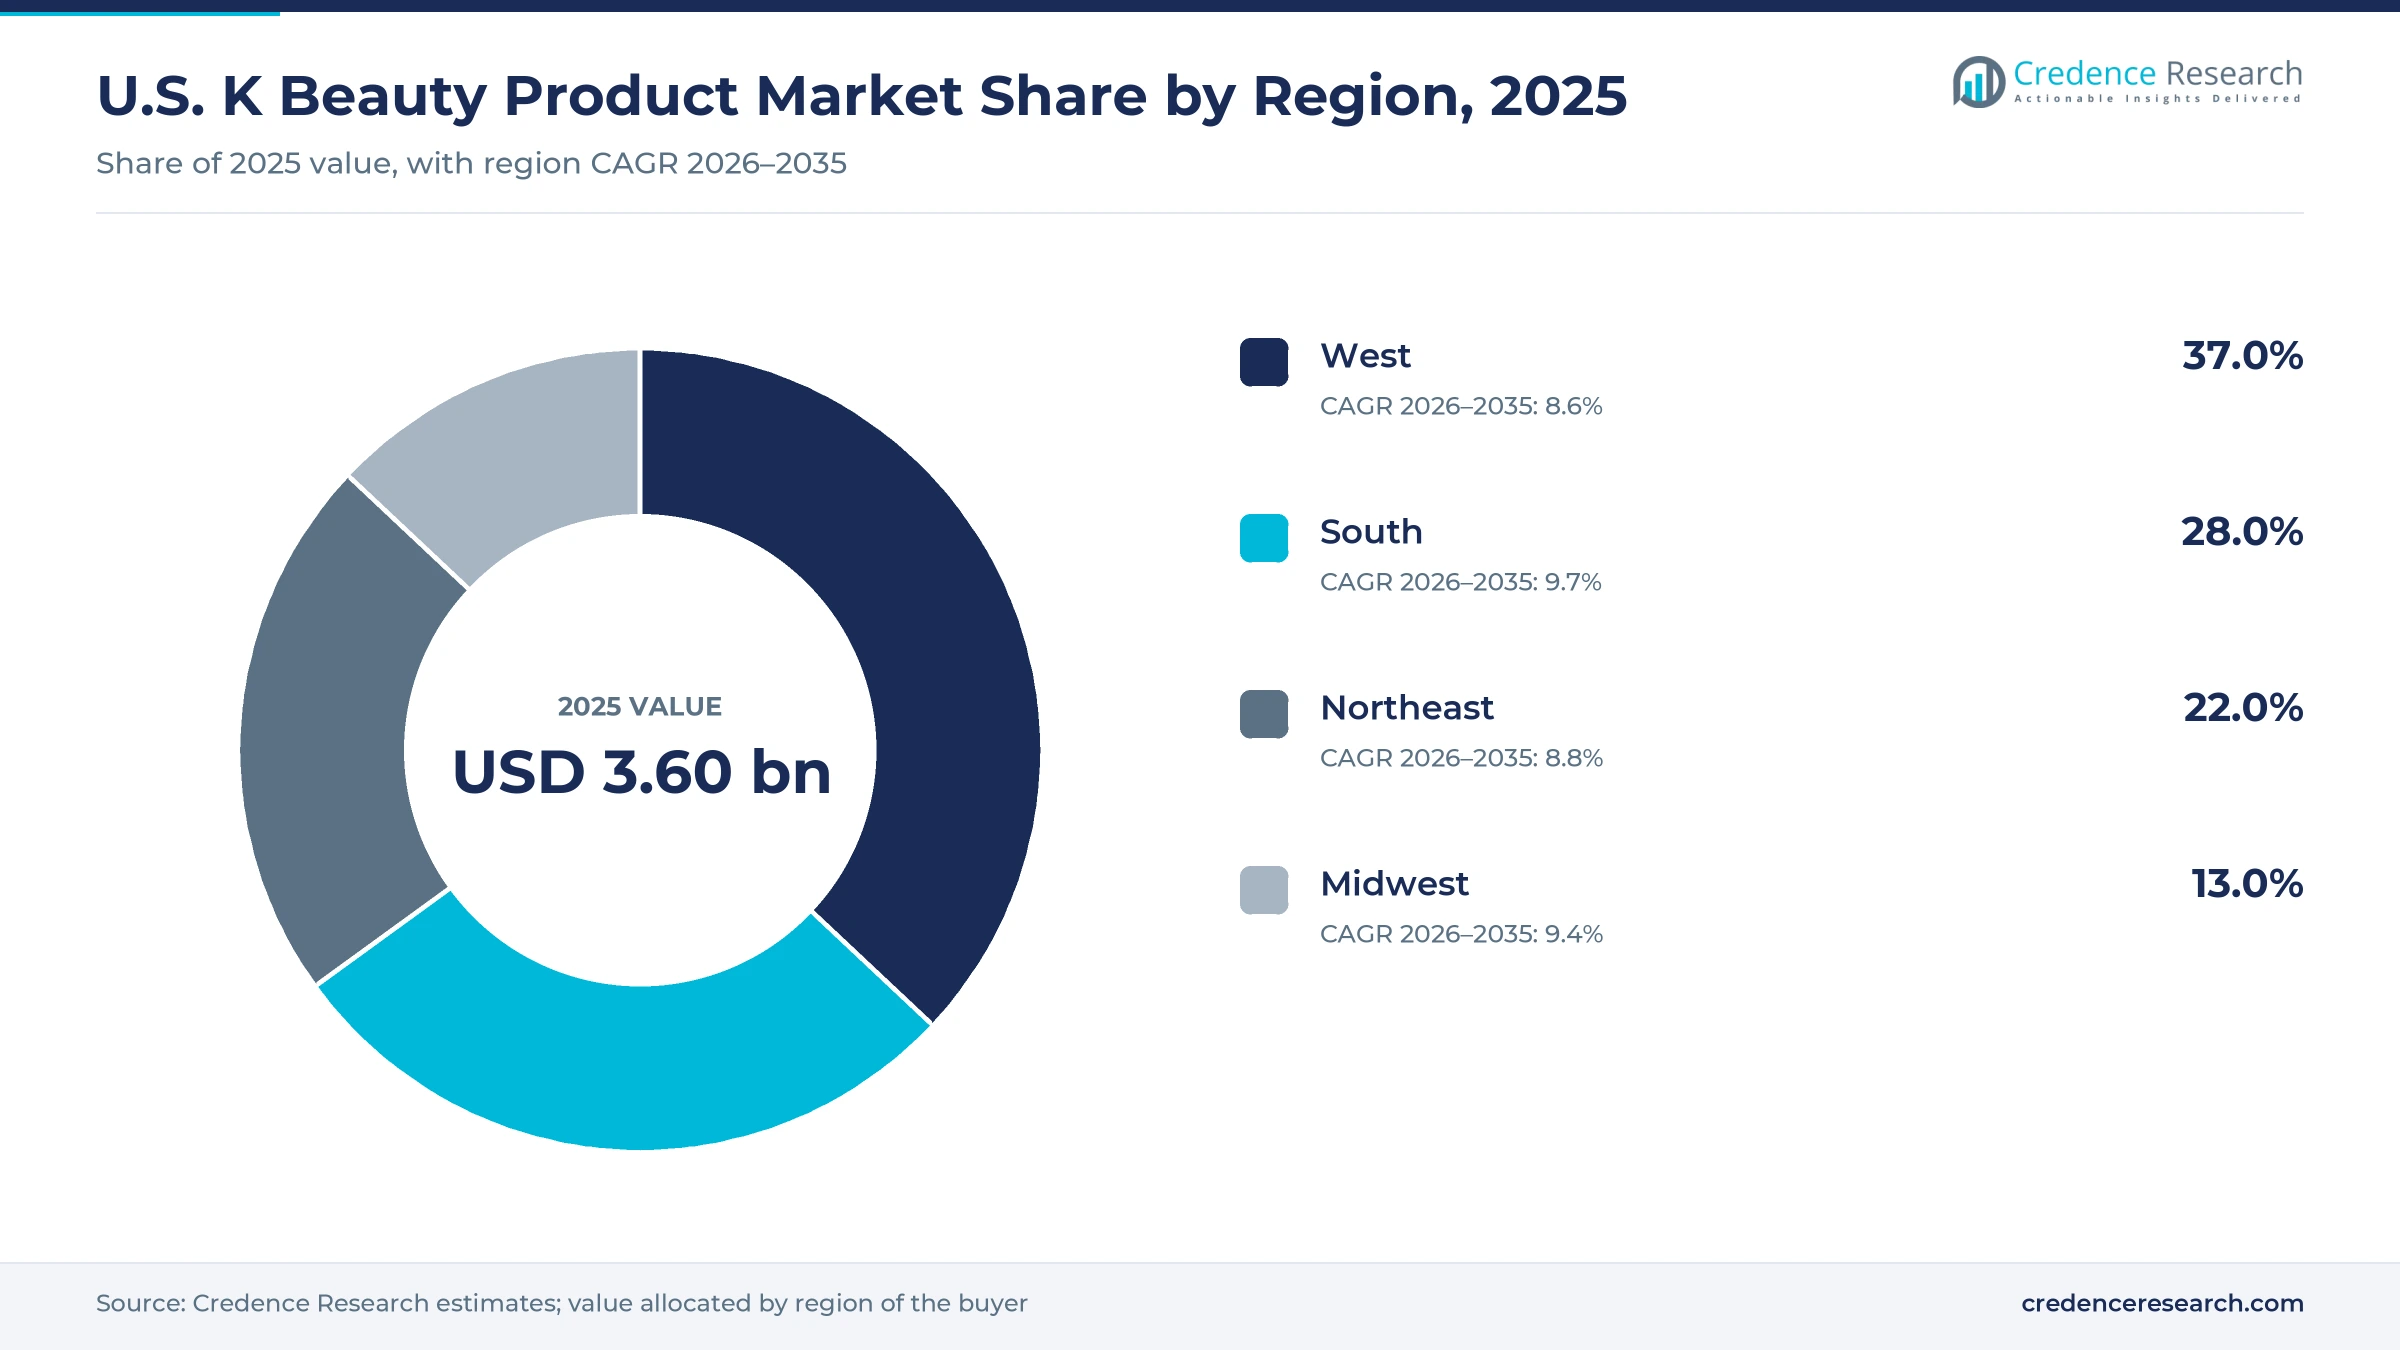
The West leads and the South grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| West | 1.33 | 37.0% | 8.6% |
| South | 1.01 | 28.0% | 9.7% |
| Northeast | 0.79 | 22.0% | 8.8% |
| Midwest | 0.47 | 13.0% | 9.4% |
The West leads on Korean American demand and new stores
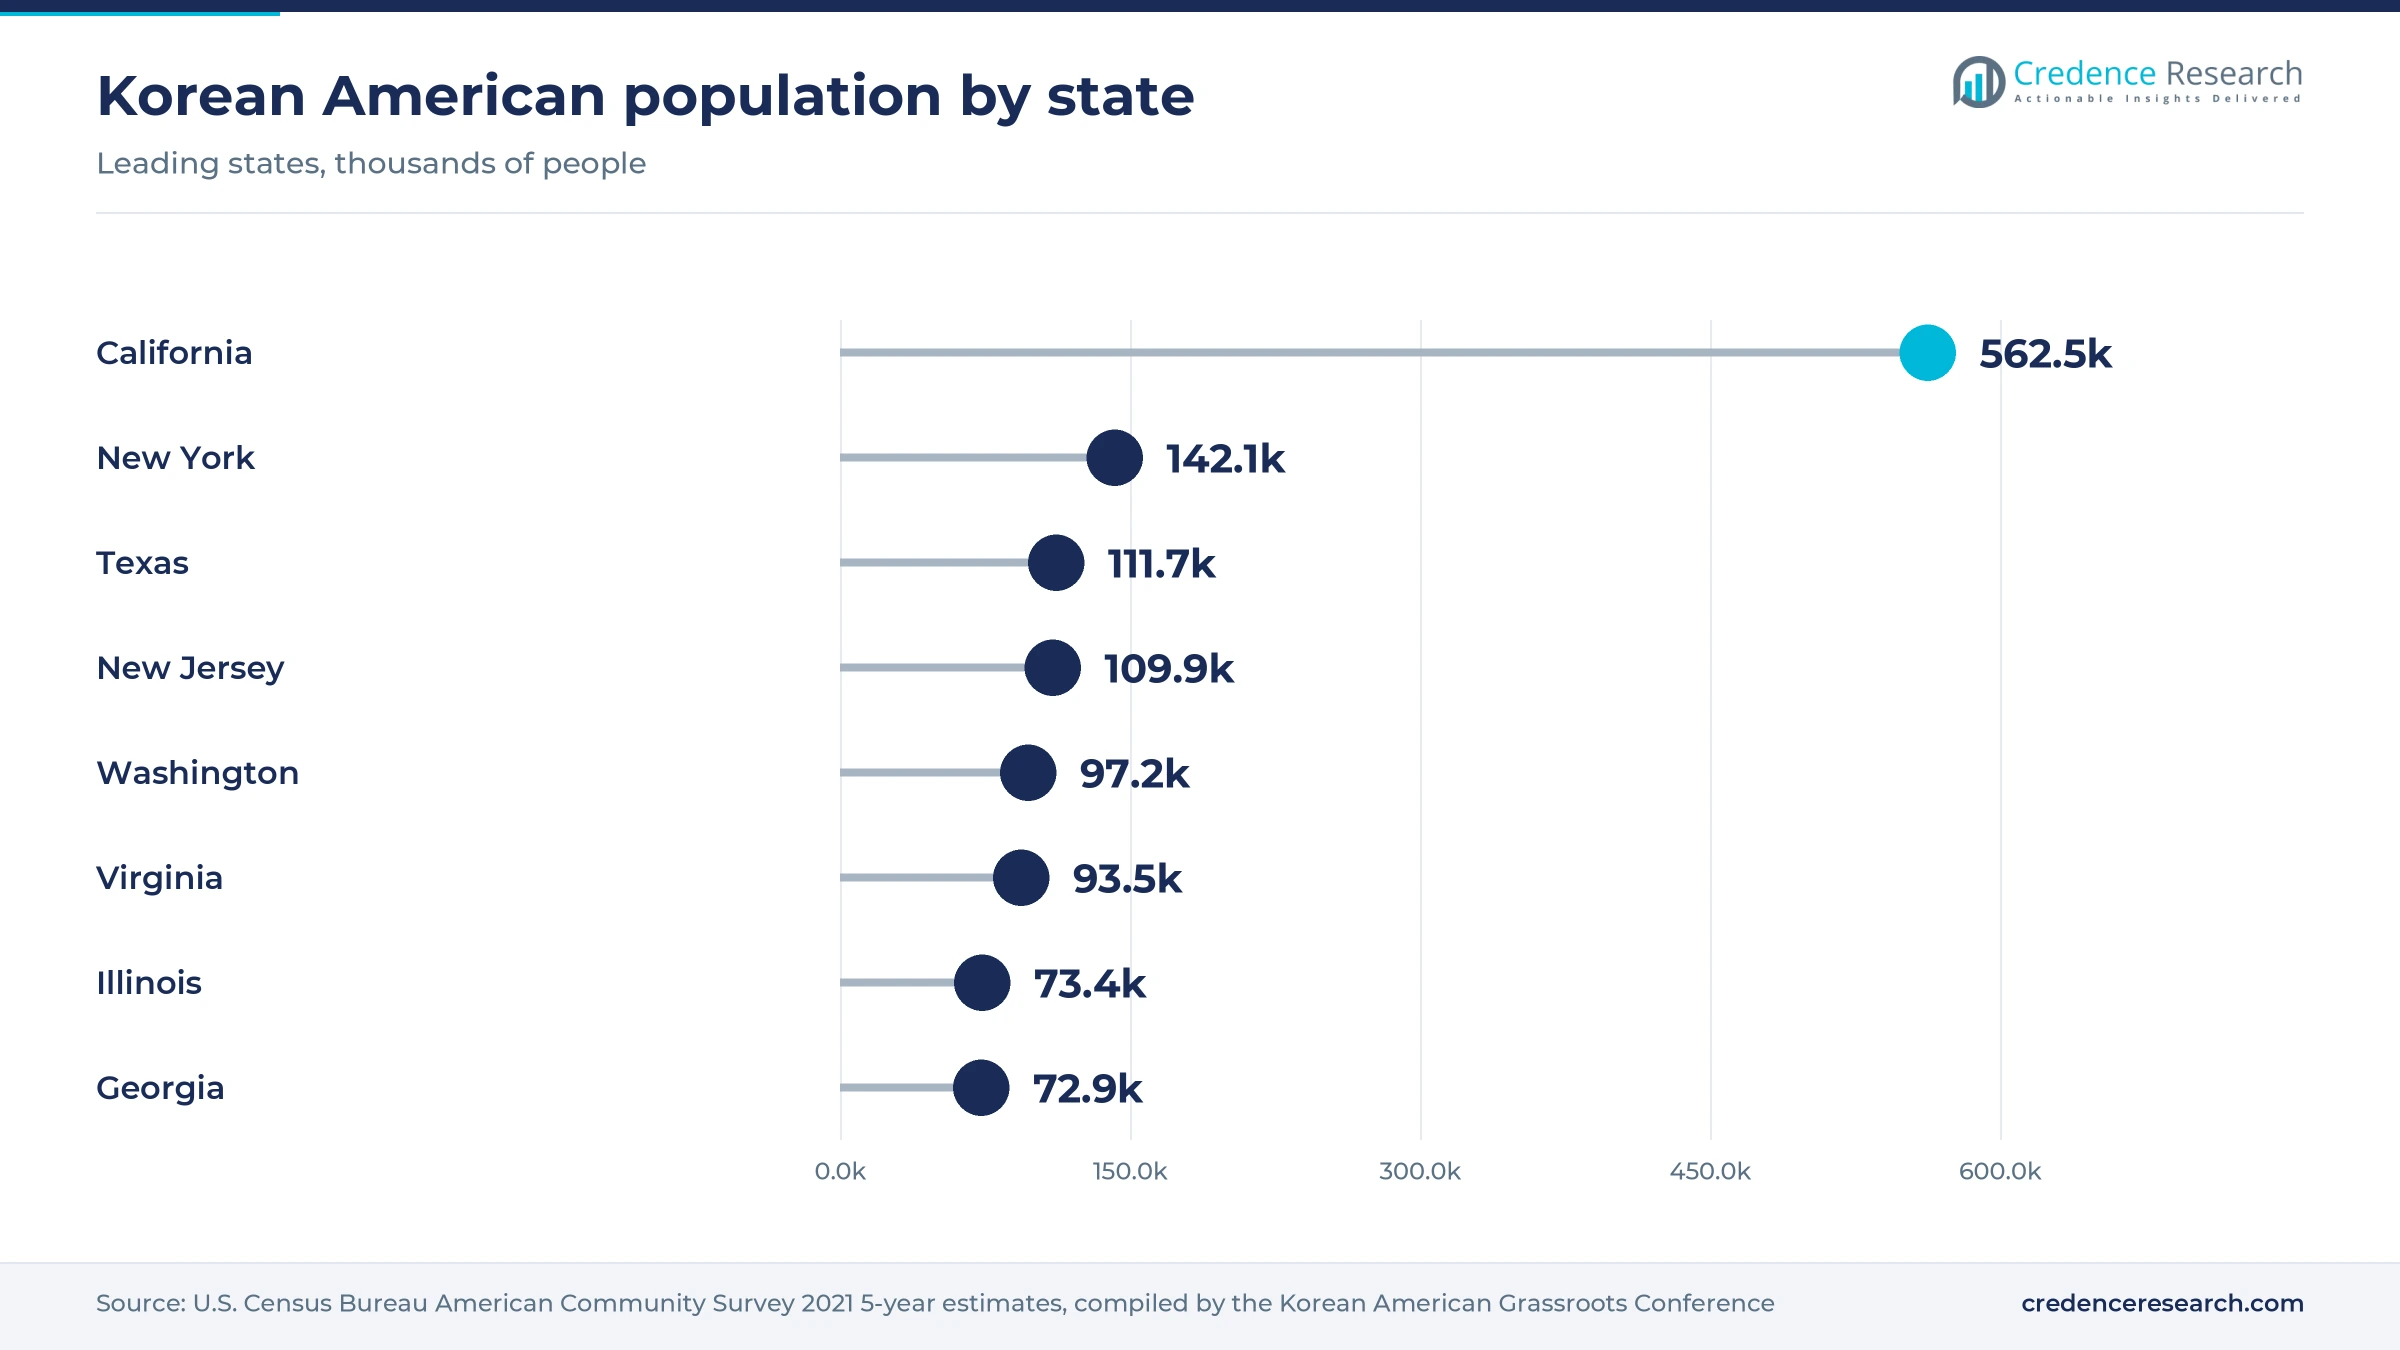
The West held 37.0% of 2025 value and grows at 8.6% a year, the slowest regional rate because its base is already large. California is home to 562,497 Korean Americans and Washington to 97,176, according to Census data compiled by the Korean American Grassroots Conference, so Korean grocery chains and beauty stores have dense local demand. Goodai Global bought Hansung USA, an Irvine distributor that supplies Ulta Beauty, Costco and Target, in February 2026, so distribution control now sits close to the ports.
The South grows fastest as chains widen ranges
The South held a 28.0% share of 2025 value and grows fastest among the four regions at 9.7% a year. Texas counts 111,701 Korean Americans, Virginia 93,481 and Georgia 72,887, giving the region several large communities rather than one dominant city. National chains carry the category into suburban malls and superstores there, and Olive Young names Southern regions as its next stage after the two coasts. Growth depends on mass merchants, so shelf productivity in Target and Costco will decide how fast the gap with the West closes.
The Northeast pairs dense cities with U.S. production
The Northeast held a 22.0% share of 2025 value and grows at 8.8% a year. New York counts 142,143 Korean Americans and New Jersey 109,856, a base that sustains Korean-owned grocery and beauty stores in the region. The Pennsylvania contract production described in the drivers shortens replenishment for East Coast retailers and Korean grocery chains in the New York metro area. Olive Young lists New York as its first East Coast target, which could add specialty store capacity after 2027.
The Midwest relies on mass and drugstore chains
The Midwest held a 13.0% share of 2025 value and grows at 9.4% a year from a smaller base. Illinois counts 73,353 Korean Americans, the largest community in the region, but most buyers outside Chicago reach the category through national chains and Amazon. LG Household & Health Care expanded The Face Shop through Walgreens, CVS and Kroger, CosmeticsDesign-Asia reported in January 2025. Warehouse clubs and supermarket beauty aisles therefore matter more here than Korean specialty stores.
Store openings, retail deals and a new UV filter
| Development | Status and market relevance |
|---|---|
| In February 2026, Goodai Global acquired Hansung USA, an Irvine distributor that supplies Ulta Beauty, Costco and Target. | Acquisition completed; gives a Korean brand group direct control of U.S. retail distribution |
| In May 2026, Olive Young opened its first U.S. store in Pasadena, followed by Century City in June 2026. | Operational launch; first Korean beauty chain stores in the United States |
| In June 2026, the FDA issued a final order adding bemotrizinol to the over-the-counter sunscreen monograph, effective Aug. 9, 2026. | Regulatory approval; opens a route for lighter U.S. sunscreen formulas |
| In October 2026, APR put Medicube on sale in about 400 U.S. Costco stores with a club-only Zero Pore Pad pack. | Commercial launch; APR plans to reach all U.S. Costco locations |
| In November 2026, Olive Young announced five more stores in Greater Los Angeles and San Diego. | Plan announced; construction targeted for completion in the first half of 2027 |
Peptides, PDRN and U.S.-made formulas set the pipeline
- Peptide complexes support firming and eye-care claims, and the COSRX The Peptide line became one of the brand's main U.S. ranges in 2025.
- PDRN, or polydeoxyribonucleotide, brings a clinic-derived repair ingredient into home skincare, and APR plans to add Medicube PDRN products to its Costco range.
- Bemotrizinol gives U.S. sunscreen makers a broad-spectrum filter long used in Korea and Europe, available under license through DSM-Firmenich during the exclusivity period.
- U.S. contract production lines allow Korean formulas to be filled near American retailers, which cuts replenishment time and import duty on fast-selling items.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Korean groups and fast-rising indies fight for shelves
Competition splits into three groups that win shelves in different ways. Amorepacific and LG Household & Health Care use portfolio depth, research centers and established retail accounts, and LG Household & Health Care also owns The Crème Shop, a U.S. brand it bought in 2022. APR, Goodai Global and The Founders compete through hero products that start on social video and Amazon, then move into Ulta Beauty, Target and Costco. APR reported North American sales up more than 260% in the first half of 2026 and plans to take Medicube into Costco in Canada and Europe, using its U.S. club pack as the template for Korean skincare in Canada. The Estée Lauder Companies owns Dr. Jart+, while Able C&C, TONYMOLY and Banila Co sell through U.S. sites and marketplaces.
Who controls supply and where do margins sit?
The supply side combines two Korean conglomerates, a wave of fast-growing brand groups and a deep base of Korean contract makers. Amorepacific and LG Household & Health Care run multi-brand portfolios, while APR, The Founders and Goodai Global grew through viral hero products. Goodai owns Beauty of Joseon, Tirtir, Skinfood and House of Hur, and with Hansung USA it now controls part of its U.S. distribution. Contract makers and cosmetics packaging suppliers keep entry barriers low, so margins sit with brand owners that hold hero products and with retailers that control shelf space.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Amorepacific Corporation | Multi-brand group | Laneige, COSRX, Innisfree, Etude and Aestura skincare sold through Sephora and Amazon |
| LG Household & Health Care | Multi-brand group | Belif, The Face Shop, CNP and The Crème Shop in U.S. retail |
| APR Corporation (Medicube) | Brand owner | Medicube toner pads and serums sold through Amazon, Ulta Beauty and Costco |
| Goodai Global (Beauty of Joseon) | Brand group and distributor | Beauty of Joseon, Tirtir and Skinfood, distributed through Hansung USA |
| The Founders (Anua) | Brand owner | Anua heartleaf toners and cleansing oils in about 1,400 Ulta Beauty stores |
| The Estée Lauder Companies (Dr. Jart+) | Brand owner | Dr. Jart+ Korean-origin skincare in U.S. prestige retail |
| Able C&C (Missha) | Brand owner | Missha Korean skincare and makeup sold through its U.S. site and marketplaces |
| TONYMOLY Co., Ltd. | Brand owner | TONYMOLY Korean skincare and makeup sold through its U.S. site |
| Banila Co | Brand owner | Banila Co Korean cleansing and skincare sold through its U.S. site |
Retail reach now matters more than viral discovery
Credence Research's view is that the U.S. market has moved past the stage where a viral product alone builds a lasting brand. Shelf access in Ulta Beauty, Target and Costco, U.S. stock and compliant formulas now decide who keeps share. Groups with several brands, U.S. warehouses and contract production carry the lowest risk, while cross-border sellers carry the import costs and delivery delays. The main evidence gaps are the lack of an official U.S. sales count for Korean brands and of any public split by gender, so those shares rest on Credence Research estimates.
Shipment data and retail checks anchor the estimate
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. Market values come from the Credence Research model, which replaces the earlier Credence Research estimate after a check against Korean export data, brand list prices and the retail markup on imported cosmetics. The 2026 value reflects a step-up of about 25%, because first-half 2026 shipments to the United States rose 41.5%. Regional and segment splits are Credence Research estimates based on population data, store presence and company disclosures. Sources include the Ministry of Food and Drug Safety, the FDA, company releases and news reports. No interviews or surveys were conducted for this edition of the report.
Mass retail, sunscreen and men set growth to 2035
Growth in the U.S. K beauty product market to 2035 rests on three conditions. Korean brands must turn their first mass retail rollouts into steady sell-through, so that Target, Costco and Ulta Beauty keep expanding the bays. Compliant sunscreens must reach national chains once the 18-month exclusivity period on the new filter ends. Men must move from single pore-care items to full routines. If these hold, mass and specialty chains gain share from online channels, while the South narrows its gap with the West as new stores open beyond California. Supermarkets and hypermarkets grow fastest at 11.1% a year, the clearest sign of that shift toward mass retail.
Tariffs and shelf productivity set the range of outcomes
The range of outcomes depends on whether Korean brands keep converting online demand into lasting shelf space, and on how import costs develop. The base case assumes the current tariff holds, U.S. production grows and mass retail rollouts keep their 2026 pace. The downside assumes higher duties and delistings after weak sell-through, while the upside assumes compliant Korean sunscreens reach national chains and men adopt routines faster.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 7.1% | USD 8.31 billion | Higher duties and weak sell-through cut shelf space in mass and specialty chains |
| Base | 9.05% | USD 9.81 billion | Current tariff holds while U.S. production and mass retail rollouts continue |
| Upside | 10.6% | USD 11.10 billion | Compliant Korean sunscreens reach national chains and male buyers adopt routines faster |
Frequently Asked Questions
How big is the U.S. K beauty product market?
How much Korean beauty does the United States import?
Which Korean skincare products sell best in the United States?
What are the main K-beauty trends in 2025 and 2026?
How is K-beauty expanding offline in the United States?
How do U.S. tariffs affect Korean beauty products?
Why are many Korean sunscreens not sold in U.S. stores?
Which companies lead the U.S. K beauty product market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Serum
- 1.2.2 Moisturizer
- 1.2.3 Cleanser
- 1.2.4 Sunscreen
- 1.2.5 Hair Care
- 1.2.6 Others
- 1.3 By End User
- 1.3.1 Women
- 1.3.2 Men
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 3.60 billion → 2035: USD 9.81 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. K Beauty Product Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. K Beauty Product Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. K Beauty Product Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. K Beauty Product Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. K Beauty Product Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. K Beauty Product Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. K Beauty Product Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. K Beauty Product Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 3.60 billion → 2035: USD 9.81 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. K Beauty Product Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Serum
- 12.3.7.2 Moisturizer
- 12.3.7.3 Cleanser
- 12.3.7.4 Sunscreen
- 12.3.7.5 Hair Care
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Women
- 12.4.7.2 Men
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. K Beauty Product End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 U.S. K Beauty Product Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 U.S. K Beauty Product Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 U.S. K Beauty Product Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amorepacific Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 LG Household & Health Care
- 18.4 APR Corporation (Medicube)
- 18.5 Goodai Global (Beauty of Joseon)
- 18.6 The Founders (Anua)
- 18.7 The Estée Lauder Companies (Dr. Jart+)
- 18.8 Able C&C (Missha)
- 18.9 TONYMOLY Co., Ltd.
- 18.10 Banila Co
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

