
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Stage Lighting Market Size 2024 | USD 729.53 Million |
| U.S. Stage Lighting Market, CAGR | 9.55% |
| U.S. Stage Lighting Market Size 2032 | USD 1,657.63 Million |
Market Overview
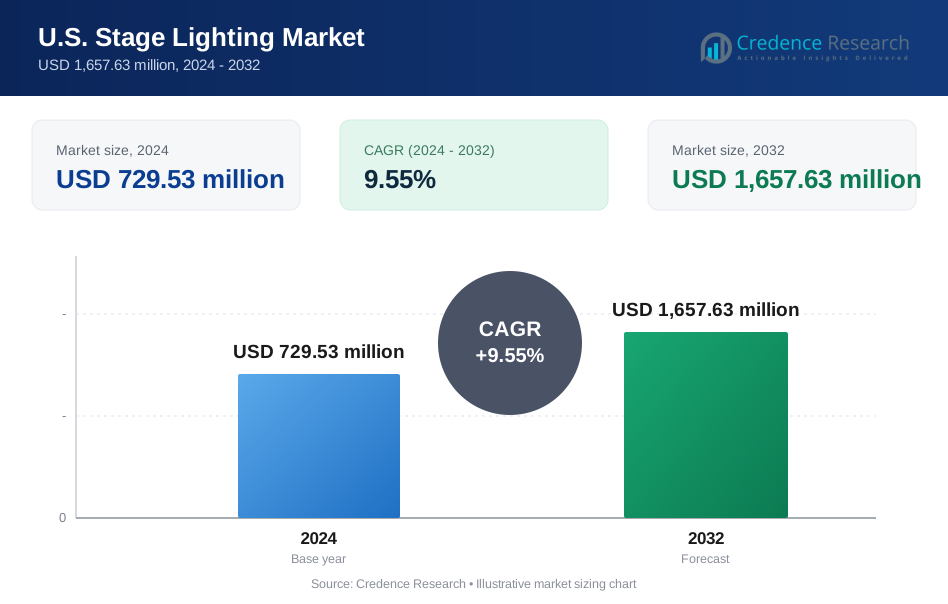
The U.S. Stage Lighting Market is projected to grow from USD 729.53 million in 2024 to an estimated USD 1,657.63 million by 2032, reflecting a compound annual growth rate (CAGR) of 9.55% from 2025 to 2032. This growth is primarily driven by the increasing demand for advanced lighting solutions in various applications, including theater productions, concerts, and corporate events.
Key market drivers include technological advancements in LED lighting, which offer energy efficiency and versatility, and the growing trend of immersive and interactive live performances that require sophisticated lighting setups. Additionally, the rise in live entertainment events and the integration of lighting with digital technologies are contributing to market expansion.
Geographically, the U.S. market dominates, with major players such as Philips Lighting, Osram Licht AG, and General Electric Company leading the sector. These companies are focusing on innovation and strategic partnerships to enhance their market positions. The competitive landscape is characterized by continuous product development and a strong emphasis on customer-centric solutions.
Market Insights
- The U.S. stage lighting market is projected to grow from USD 729.53 million in 2024 to USD 1,657.63 million by 2032, at a CAGR of 9.55% from 2025 to 2032.
- Rising demand for immersive live events and technologically advanced lighting solutions is a key factor propelling market growth.
- Advancements in LED lighting and smart control systems are enhancing energy efficiency and customization in stage lighting setups.
- High initial investment and ongoing maintenance costs limit adoption, especially among small and mid-sized venues.
- A shortage of skilled professionals capable of operating and integrating modern lighting systems hampers full utilization.
- The Western U.S. dominates the market with 34.2% share, led by major entertainment hubs like Los Angeles and Las Vegas.
- The Southern and Northeastern regions are experiencing strong growth due to expanding event industries and increasing investments in fixed installations.
Market Drivers
Integration of Digital Technologies and Automation
The integration of digital technologies with stage lighting has created new opportunities for the U.S. stage lighting market. Modern lighting systems now incorporate digital controls, automation, and synchronization with other performance elements, such as sound and video projections. These capabilities enable event organizers to create intricate lighting designs that can be adjusted in real-time, providing greater creative flexibility and improving the overall production value. For instance, lighting systems can now be programmed to automatically adjust brightness, color, and movement based on the timing of a performance or specific cues. This level of precision is particularly beneficial in high-end productions where every detail matters. Additionally, the integration of cloud-based technologies allows for remote operation and monitoring of lighting systems, which further enhances convenience and efficiency in managing complex setups. The adoption of digital and automated lighting solutions is likely to continue to drive market growth, as it offers significant advantages in terms of flexibility, cost-efficiency, and enhanced performance.
Growing Adoption of Energy-Efficient Lighting Solutions
Sustainability and energy efficiency have become major considerations in the entertainment industry, pushing the demand for eco-friendly and cost-effective stage lighting solutions. Traditional lighting systems, such as incandescent and halogen bulbs, are energy-intensive and require frequent maintenance. In contrast, modern LED-based stage lighting systems consume significantly less power and have a much longer lifespan. This energy efficiency not only reduces operational costs for event organizers but also aligns with the growing focus on environmental sustainability within the entertainment sector. Additionally, LEDs generate less heat, reducing the need for extensive cooling systems and creating a more comfortable environment for performers and audience members alike. The trend toward green lighting solutions is further supported by government regulations and industry standards that encourage the use of energy-efficient technologies. As the push for sustainability continues, the U.S. stage lighting market is expected to experience sustained growth driven by the widespread adoption of energy-efficient lighting systems.
Technological Advancements in Lighting Systems
The U.S. stage lighting market has experienced significant growth due to continuous advancements in lighting technologies. For instance, companies like those in the entertainment sector have widely adopted LED technology, which offers higher energy efficiency, longer lifespan, and superior color quality compared to traditional lighting sources. These features make LEDs an attractive choice for stage lighting in concerts, theater productions, and corporate events, where dynamic and energy-efficient lighting is crucial. Additionally, LEDs provide greater flexibility in terms of design and integration with other technologies, enabling the creation of intricate lighting effects and interactive experiences. The advent of smart lighting, which allows for remote control and automation, further drives the demand for advanced lighting solutions. As the entertainment industry continues to evolve, stage lighting systems equipped with cutting-edge features such as digital controls, wireless connectivity, and real-time feedback are becoming the norm.
Rising Demand for Live Entertainment and Interactive Experiences
The growing popularity of live entertainment events, including concerts, theatrical performances, and festivals, is another key driver for the U.S. stage lighting market. For instance, surveys by government authorities and event organizers have highlighted the increasing consumer preference for immersive and engaging experiences. Event organizers are increasingly seeking innovative lighting solutions to enhance the visual appeal and overall atmosphere of performances. Stage lighting has evolved from simple illumination to an essential tool for storytelling, mood setting, and audience engagement. Interactive lighting systems, which synchronize with sound or other performance elements, are gaining traction as they provide more immersive experiences for attendees. The increased demand for customized, high-quality lighting effects is particularly evident in large-scale events, such as music festivals and Broadway shows, where lighting plays a critical role in creating a memorable and engaging environment. As live events continue to grow in popularity, the demand for advanced stage lighting systems is expected to rise, contributing to the overall market expansion.
Market Trends
Incorporation of Augmented Reality (AR) and Virtual Reality (VR) in Stage Productions
The U.S. stage lighting market is also being influenced by the rising integration of augmented reality (AR) and virtual reality (VR) technologies into live performances and theatrical productions. These immersive technologies are transforming the way lighting is used in storytelling and audience engagement. In AR and VR-enhanced performances, lighting must be intricately coordinated with virtual elements to create seamless, interactive environments. For instance, stage lighting can be programmed to match the mood and spatial dynamics of virtual scenery, ensuring consistency and immersion throughout the performance. This trend is particularly evident in experimental theater, multimedia shows, and high-concept concerts where cutting-edge technology is central to the creative vision. Lighting designers are now required to collaborate closely with digital artists and VR developers to craft dynamic visual experiences that blur the boundaries between physical and virtual realms. The convergence of lighting with AR/VR is still in its early stages, but its potential is vast, especially as audiences seek novel and tech-driven entertainment formats.
Customization and Personalization of Lighting Experiences
Personalized lighting experiences are becoming a key differentiator in the U.S. stage lighting market. As audiences increasingly seek unique and memorable engagements, production teams are investing in highly customizable lighting solutions that can be tailored to individual performances or audience preferences. Advanced lighting control software allows for real-time adjustments, while digital lighting consoles support an extensive range of programmable effects and transitions. Custom lighting design is particularly valued in touring concerts, corporate presentations, and themed productions, where lighting needs vary significantly from one event to another. Furthermore, the use of 3D visualizers and simulation tools in the planning phase allows designers to preview and fine-tune lighting schemes before implementation, ensuring a perfect match with the artistic direction. This trend toward personalization is also evident in smaller venues and independent productions, where distinctive lighting helps to create a signature aesthetic and enhances brand identity. The demand for customized lighting experiences is driving innovation in fixture design, software capabilities, and overall system flexibility, pushing manufacturers and suppliers to deliver more versatile and user-friendly solutions.
Rising Adoption of Smart and Connected Lighting Systems
The U.S. stage lighting market is witnessing a significant shift toward smart and connected lighting technologies, driven by advancements in IoT integration and digital control systems. These systems enable lighting designers to create dynamic, immersive experiences by offering features such as wireless connectivity, automated programming, and real-time monitoring. For instance, companies like GE Lighting have collaborated with platforms such as Samsung SmartThings to deliver innovative solutions tailored for modern stage productions. Such partnerships highlight the growing demand for intelligent lighting that can be remotely controlled and synchronized with other performance elements. Additionally, the widespread adoption of mobile applications and cloud-based platforms has enhanced flexibility, allowing technicians to manage complex setups from remote locations. The entertainment industry’s increasing emphasis on automation and precision in large-scale events-such as concerts and theatrical productions-further accelerates this trend. Government support for energy-efficient technologies also plays a role in promoting smart lighting adoption, as regulatory frameworks encourage innovation in connected systems. As performance venues prioritize technologically sophisticated experiences, the integration of smart lighting solutions will continue to expand across the market.
Emphasis on Energy Efficiency and Sustainable Lighting Solutions
The U.S. stage lighting industry is rapidly transitioning toward energy-efficient technologies, particularly LED systems, which offer reduced energy consumption, longer lifespans, and minimal heat emission. This shift is supported by government initiatives such as the ENERGY STAR program and legislation like the BRIGHT Act, which mandate the use of sustainable lighting solutions in federal buildings. For example, rebates offered by utility companies like Duke Energy incentivize businesses to replace traditional incandescent fixtures with LEDs, making eco-friendly options more accessible. LED technology not only lowers operational costs but also enhances creative flexibility by enabling precise control over color and brightness levels without additional materials like filters or gels. Manufacturers are increasingly producing recyclable components to align with environmental goals, further reducing waste in theatrical productions. Additionally, advancements in high-lumen output LEDs tailored for stage applications ensure superior performance quality while maintaining sustainability standards. The entertainment industry’s focus on green practices is also evident in the adoption of solar-powered systems for outdoor events. As environmental consciousness grows among production companies and venue operators, energy-efficient lighting solutions are set to dominate the market landscape.
Market Challenges
Complexity of System Integration and Technical Skill Requirements
The increasing sophistication of stage lighting systems presents another significant challenge: the need for skilled professionals capable of designing, operating, and maintaining complex lighting setups. As stage productions grow more technologically advanced, lighting professionals must be proficient not only in traditional lighting design but also in programming, networking, and integration with audio-visual systems. The lack of adequately trained technicians can lead to underutilization of advanced systems or technical issues during live performances. Furthermore, integrating lighting with digital platforms, augmented reality (AR), or real-time show control software requires cross-functional expertise that may not be readily available in all production environments. This skills gap can hamper operational efficiency and discourage smaller organizations from investing in cutting-edge lighting solutions, thereby posing a constraint on market growth. Addressing this challenge will require industry-wide efforts in training, certification, and accessible education programs.
High Initial Investment and Maintenance Costs
One of the primary challenges facing the U.S. stage lighting market is the high initial cost of advanced lighting systems. Surveys indicate that smaller theaters and community production companies often cite budget constraints as a significant obstacle to adopting modern lighting technologies. For instance, implementing LED systems, which are valued for their energy efficiency and longevity, requires substantial upfront investment in equipment like specialized consoles and wireless control systems. Additionally, the integration of these systems with existing infrastructure often necessitates skilled technicians, further increasing costs. Maintenance is another critical factor; regular upkeep, such as cleaning, lubrication, and software updates, requires both time and expertise. Theaters typically allocate around 10% of the original purchase price annually for maintenance, with older or heavily used equipment requiring even more frequent attention. These financial demands can deter smaller venues or budget-sensitive organizations from upgrading their systems, limiting market penetration of advanced lighting technologies. While government incentives and rebates have helped reduce costs for some adopters, the high initial investment remains a considerable barrier for many stakeholders in the performing arts industry.
Market Opportunities
Expanding Demand Across Non-Traditional Venues
A significant growth opportunity in the U.S. stage lighting market lies in the increasing adoption of professional lighting solutions across non-traditional venues. Beyond conventional theaters and concert halls, there is rising demand from sectors such as corporate events, houses of worship, theme parks, museums, and educational institutions. These venues are incorporating advanced lighting to enhance presentations, create immersive environments, and deliver engaging visual experiences. As hybrid and in-person events gain momentum post-pandemic, the need for dynamic, adaptable lighting systems has become more pronounced. This shift offers lighting manufacturers and service providers a broader customer base and the potential to deliver customized solutions to a diverse range of clients seeking both aesthetic impact and technical efficiency.
Technological Innovation and Integration with Emerging Media
The ongoing evolution of lighting technology presents substantial market opportunities, particularly in the integration of stage lighting with emerging media formats such as augmented reality (AR), virtual reality (VR), and projection mapping. These innovations enable the creation of visually compelling, immersive experiences that appeal to modern audiences and performers alike. Moreover, developments in automation, AI-based lighting control, and wireless connectivity are opening doors for streamlined operations and cost-effective setups. As live entertainment producers seek to differentiate their shows with cutting-edge effects, companies that offer innovative, scalable lighting solutions will be well-positioned to lead the market. This trend is expected to drive investments in R&D, collaboration with tech firms, and the development of smart lighting ecosystems tailored for live and hybrid performance environments.
Market Segmentation Analysis
By Application
The market demonstrates diverse growth across segments. Concerts and Theatres lead in adoption due to the need for sophisticated and dynamic lighting effects. The Broadcast Industry also presents strong demand, driven by the necessity of professional-grade lighting for high-quality video production. Additionally, Weddings/Events, Houses of Worship, and the Hospitality Industry are emerging as growth areas, adopting customizable and atmospheric lighting solutions. Architectural and Commercial Installs, Fitness Sports, Night Clubs, and DJ Retail/Rec DJ are contributing to market expansion, highlighting the versatile applications of stage lighting across non-traditional environments.
By End User
The market is segmented into Touring Rental and Fixed Installation. Touring rental dominates due to the frequent and high-scale lighting needs of traveling concerts and live shows. However, fixed installations in venues such as theatres, churches, and corporate spaces are gaining momentum due to long-term lighting investments and the shift toward hybrid event formats.
Segments
Based on Product
- Lighting Fixture
- Lighting Controller
Based on Application
- Concerts 5
- Broadcast Industry
- Weddings/Events
- Hospitality Industry
- Architectural and Commercial Installs
- Houses of Worship
- DJ Retail/Rec DJ
- Theatres
- Fitness Sports
- Night Clubs
Based on End User
- Touring Rental
- Fixed Installation
Based on Lighting Control System
- Stage Lighting Controllers
- Stage Lighting Visualizers
Based on Distribution Channel
- Manufacturer and Channel Partners
- Retail Distribution
- Online Distribution
- Others
Based on Region
- New York
- Los Angeles
- Las Vegas
Regional Analysis
Western U.S. (34.2%)
The Western U.S. holds the largest market share at 34.2%, driven by the presence of prominent entertainment and cultural centers such as Los Angeles, Las Vegas, and San Francisco. These cities host a high volume of concerts, live performances, theatrical productions, and corporate events. Las Vegas, in particular, stands out as a global hub for live shows and large-scale events, necessitating sophisticated lighting systems. The region also benefits from a strong concentration of production companies and rental services, which actively invest in technologically advanced lighting solutions to stay competitive.
Southern U.S. (27.5%)
The Southern U.S. accounts for 27.5% of the market, fueled by rising demand from growing entertainment industries in cities like Nashville, Austin, Atlanta, and Orlando. Nashville’s music industry, along with the increasing number of festivals and large events across the region, contributes significantly to the adoption of stage lighting. Additionally, the expanding presence of mega-churches and worship centers, particularly in Texas and Georgia, has led to higher investment in professional lighting installations.
Key players
- Golden Sea (SGM)
- HARMAN International
- ETC (Electronic Theatre Controls) Lighting
- CHAUVET Lighting
- Altman Lighting Co.
Competitive Analysis
The U.S. stage lighting market is highly competitive, characterized by both established global players and specialized lighting solution providers. Golden Sea (SGM) maintains a strong presence through its advanced product portfolio and strategic business expansions, particularly in intelligent lighting systems. HARMAN International leverages its strong brand reputation and broad technological capabilities across audio and lighting solutions, giving it a competitive edge in integrated performance systems. ETC Lighting holds a dominant position in the theatrical lighting segment, renowned for its high-quality fixtures and control consoles tailored to performance arts. CHAUVET Lighting excels in the event and entertainment segment, offering innovative and user-friendly products that cater to a wide range of professional and semi-professional users. Altman Lighting Co., with a legacy in the industry, continues to serve niche markets with durable, customizable lighting solutions. These companies compete on innovation, product reliability, customer support, and the ability to meet diverse application requirements.
Recent Developments
- On September 2, 2024, Golden Sea, a Chinese lighting company, acquired Denmark-based SGM Light AS. This acquisition aligns with Golden Sea's strategy to expand its portfolio in entertainment and architectural IP65 solid-state lighting products. SGM's patented technology, known for its low maintenance and consistent performance, will enhance Golden Sea's offerings in stage and architectural lighting.
- In April 2024, HARMAN Professional Solutions launched the Martin Lighting Spring Roadshow across the U.S., showcasing innovations like the Martin Viper XIP, a weatherproof moving head fixture with advanced features for stage lighting. The event included free learning sessions and hands-on product demonstrations for lighting professionals.
Market Concentration and Characteristics
The U.S. stage lighting market exhibits a moderate to high market concentration, with a few key players such as HARMAN International, ETC Lighting, CHAUVET Lighting, and Golden Sea (SGM) holding substantial market shares. These companies dominate through extensive product portfolios, strong distribution networks, and continuous technological innovation. The market is characterized by a high degree of technological sophistication, driven by increasing demand for smart, energy-efficient, and customizable lighting solutions across diverse applications. It also reflects rapid product development cycles, as companies strive to meet evolving industry needs, particularly in immersive entertainment, live events, and hybrid performance environments. Moreover, there is a growing emphasis on integration with digital platforms, automation, and sustainability, which shapes purchasing decisions and long-term investments. While large players benefit from brand recognition and R&D capabilities, niche manufacturers find opportunities by catering to specialized applications and regional demands.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, End User, Lighting Control System, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The U.S. stage lighting market is projected to experience steady growth, driven by increasing demand for advanced lighting solutions in live events and entertainment sectors.
- Ongoing innovations in LED technology are enhancing energy efficiency and performance, leading to widespread adoption across various stage lighting applications.
- The incorporation of programmable and automated control systems is enabling more dynamic and customizable lighting designs, enhancing the overall audience experience.
- There is a growing focus on energy-efficient lighting solutions, with manufacturers developing products that reduce power consumption and align with sustainability initiatives.
- Stage lighting solutions are increasingly being adopted in non-traditional venues such as corporate events, houses of worship, and educational institutions, broadening the market scope.
- The demand for immersive and interactive experiences is driving the development of advanced lighting technologies that can seamlessly integrate with augmented and virtual reality platforms.
- Clients are seeking more personalized lighting solutions tailored to specific events and performances, prompting manufacturers to offer customizable products and services.
- The complexity of modern lighting systems necessitates skilled professionals for design and operation, highlighting the need for specialized training programs in the industry.
- Fluctuations in raw material prices and supply chain disruptions pose challenges, encouraging companies to explore alternative sourcing and production strategies.
- The market is witnessing heightened competition, driving companies to invest in research and development to introduce innovative and differentiated lighting solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Technological Advancements in LED and Smart Lighting
Continuous innovation in LED technology and smart lighting control systems is enabling more energy-efficient, versatile, and customizable stage lighting solutions, which are increasingly adopted for their superior performance and cost savings.
Integration of Digital Technologies and Automation
The adoption of digital controls, automation, and synchronization with audio-visual elements allows for real-time adjustments and intricate lighting designs, enhancing creative flexibility and production value in live events.
Rising Demand for Immersive and Interactive Experiences
Live entertainment producers are seeking advanced lighting systems that can create immersive, interactive environments, driving demand for programmable and responsive lighting solutions that enhance audience engagement.
Expansion into Non-Traditional Venues
The use of professional stage lighting is growing in non-traditional venues such as corporate events, houses of worship, and educational institutions, broadening the market and increasing the need for adaptable and scalable lighting systems.
Emphasis on Energy Efficiency and Sustainability
Growing environmental awareness and regulatory support are pushing the adoption of energy-efficient lighting solutions, particularly LEDs, which reduce operational costs and align with sustainability initiatives in the entertainment industry.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the market size of the U.S. stage lighting market in 2023, and what is it expected to be by 2032?
What factors are driving growth in the U.S. stage lighting market?
Which applications are contributing most to the stage lighting market in the U.S.?
Who are the major players in the U.S. stage lighting market?
How is digital integration influencing the stage lighting market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Lighting Fixture
- 1.2.2 Lighting Controller
- 1.3 By End User
- 1.3.1 Touring Rental
- 1.3.2 Fixed Installation
- 1.4 By Application
- 1.4.1 Concerts
- 1.4.2 Broadcast Industry
- 1.4.3 Weddings/Events
- 1.4.4 Hospitality Industry
- 1.4.5 Houses of Worship
- 1.4.6 Theatres
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 729.53 million → 2032: USD 1,657.63 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Stage Lighting Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Stage Lighting Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. Stage Lighting Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. Stage Lighting Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Stage Lighting Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Stage Lighting Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Stage Lighting Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Stage Lighting Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 729.53 million → 2032: USD 1,657.63 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Stage Lighting Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Lighting Fixture
- 12.3.7.2 Lighting Controller
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Touring Rental
- 12.4.7.2 Fixed Installation
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Concerts
- 12.5.7.2 Broadcast Industry
- 12.5.7.3 Weddings/Events
- 12.5.7.4 Hospitality Industry
- 12.5.7.5 Houses of Worship
- 12.5.7.6 Theatres
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Stage Lighting End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 U.S. Stage Lighting Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 U.S. Stage Lighting Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 U.S. Stage Lighting Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 HARMAN International
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 ETC (Electronic Theatre Controls) Lighting
- 18.4 CHAUVET Lighting
- 18.5 Golden Sea (SGM)
- 18.6 Altman Lighting Co.
- 18.7 Philips Lighting
- 18.8 Osram Licht AG
- 18.9 General Electric Company
- 18.10 ADJ Lighting
- 18.11 Martin Professional
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

