
Market Overview:
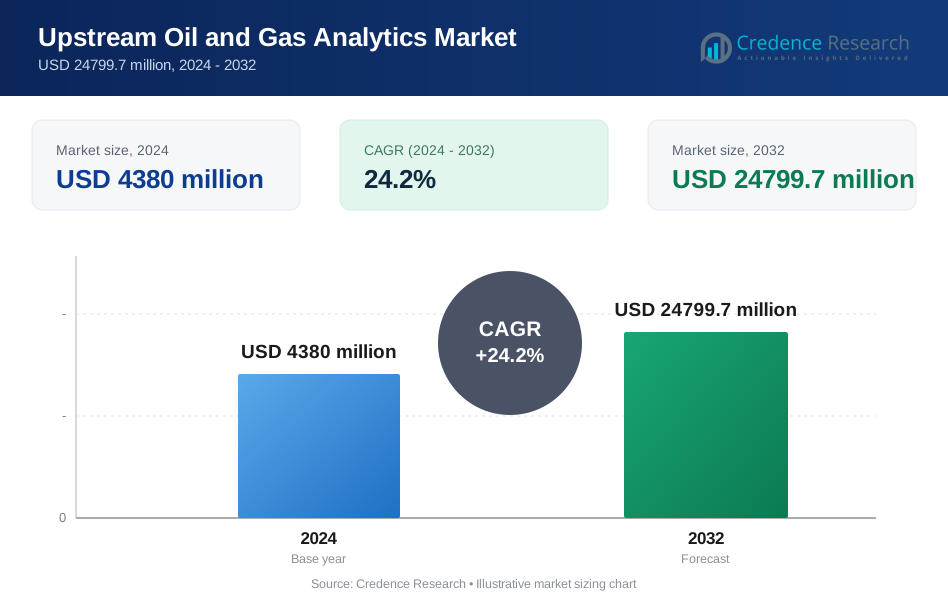
The Upstream Oil and Gas Analytics Market size was valued at USD 4380 million in 2024 and is anticipated to reach USD 24799.7million by 2032, at a CAGR of 24.2% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Upstream Oil and Gas Analytics Market Size 2024 | USD 4380 million |
| Upstream Oil and Gas Analytics Market, CAGR | 24.2% |
| Upstream Oil and Gas Analytics Market Size 2032 | USD 24799.7million |
Market growth is supported by the rising adoption of digital technologies such as cloud computing, artificial intelligence, real-time data analysis, and machine learning. These solutions improve operational efficiency, reduce costs, enable predictive maintenance, and strengthen decision-making across complex upstream operations. Furthermore, the growing need to maximize production recovery and optimize performance in challenging oil and gas fields continues to drive the demand for advanced analytics platforms.
Regionally, North America maintains a dominant position, underpinned by advanced oilfield infrastructure and rapid digital transformation initiatives among major operators. The Asia-Pacific region is emerging as a fast-growing market, fueled by large-scale upstream projects and the adoption of smart technologies to enhance productivity. Europe also shows steady growth as energy producers accelerate digital strategies to remain competitive and meet efficiency and sustainability targets. Growing regulatory emphasis on safety, sustainability, and carbon reduction further accelerates analytics adoption across all major regions.

Market Insights:
- The Upstream Oil and Gas Analytics Market was valued at USD 4380 million and is projected to reach USD 24799.7 million by 2032, growing at a CAGR of 24.2%.
- Rising adoption of cloud computing, artificial intelligence, and real-time data analysis is transforming upstream operations into more efficient and cost-effective processes.
- Predictive analytics and machine learning are enabling operators to extend asset life, reduce downtime, and optimize drilling performance.
- Volatile oil prices and high production costs are increasing demand for analytics solutions that enhance efficiency and ensure profitability under uncertain market conditions.
- North America leads the market with 38% share, supported by advanced infrastructure and strong investments in shale exploration and predictive platforms.
- Asia-Pacific holds 27% share and is expanding rapidly due to large-scale upstream projects, growing energy demand, and government-driven digital initiatives.
- Europe accounts for 22% share, driven by strict regulations, sustainability goals, and rising adoption of IoT-based monitoring and digital twin solutions.
Market Drivers:
Rising Integration of Digital Technologies in Exploration and Production
The Upstream Oil and Gas Analytics Market is experiencing strong growth due to the increasing use of digital technologies. Cloud computing, real-time data analysis, and artificial intelligence are enabling operators to handle large volumes of complex data more effectively. It allows faster decision-making, predictive maintenance, and optimized drilling operations. Machine learning tools are also improving asset performance and extending equipment life cycles. These digital solutions are now considered critical for competitive advantage.
- For instance, SLB's Neuro autonomous solutions successfully drilled a well offshore Brazil, achieving a 1.58-meter center-to-target distance.
Growing Focus on Cost Optimization and Operational Efficiency
Volatile oil prices and rising production costs continue to pressure operators. The Upstream Oil and Gas Analytics Market benefits from solutions that reduce downtime, streamline workflows, and enhance resource allocation. It helps operators achieve significant savings through predictive asset management and performance monitoring. Companies are investing in analytics to lower risks associated with exploration and to maintain profitability in uncertain market conditions. The focus on efficiency supports steady adoption across the industry.
- For instance, in an offshore project in Eastern Canada, Halliburton's integrated project management led to the completion of the project with 194 days of simultaneous operations, reducing the total delivery time by one full year.
Increasing Complexity of Oilfields Driving Advanced Analytics Adoption
Mature reservoirs and deep-water fields require advanced solutions for performance optimization. The Upstream Oil and Gas Analytics Market gains traction as operators rely on predictive models to maximize recovery rates. It supports enhanced reservoir management, drilling precision, and production forecasting in challenging environments. Analytics platforms are now central to addressing operational risks in complex oilfields. This trend highlights the strategic importance of data-driven tools in upstream operations.
Regulatory Emphasis on Sustainability and Safety Standards
Stricter environmental regulations and safety requirements are accelerating adoption of analytics solutions. The Upstream Oil and Gas Analytics Market is responding with tools that track emissions, monitor safety compliance, and improve reporting accuracy. It enables operators to align with global sustainability goals while reducing operational risks. Governments and industry bodies are pushing for better resource efficiency and transparency. This regulatory momentum reinforces the role of analytics in driving responsible growth.
Market Trends:
Expansion of Advanced Analytics, Artificial Intelligence, and Cloud-Based Platforms
The Upstream Oil and Gas Analytics Market is witnessing rapid expansion through the integration of artificial intelligence, cloud platforms, and automation tools. Operators are using advanced analytics for predictive maintenance, production forecasting, and improved reservoir modeling. It allows companies to manage large datasets in real time, ensuring faster insights and better operational decisions. Cloud adoption is rising, offering scalable solutions that reduce capital expenditure while enhancing collaboration across geographically dispersed teams. Automation of data processing is also streamlining workflows and reducing human error. This trend is creating a strong foundation for higher productivity in upstream activities.
- For instance, Rockwell Automation utilizes Microsoft's IoT platform to monitor its oil and gas assets, saving up to $300,000 in production value per day by proactively identifying pump issues.
Adoption of Sustainability-Oriented Analytics and Real-Time Decision Support Systems
The shift toward low-carbon operations and regulatory compliance is shaping technology investment in the sector. The Upstream Oil and Gas Analytics Market is focusing on sustainability, with platforms designed to track emissions, optimize resource utilization, and support transparent reporting. It is becoming increasingly important for operators to meet environmental targets while maintaining production efficiency. Real-time analytics solutions are enabling faster responses to drilling and production challenges, reducing downtime, and improving safety standards. The integration of digital twins and IoT sensors is further advancing decision support systems in upstream operations. These innovations are positioning analytics as a central tool for aligning profitability with sustainability.
- For instance, Schlumberger has committed to the "Aiming for Zero Methane Emissions Initiative" to support energy companies in reducing the warming impact of their operational methane emissions.
Market Challenges Analysis:
High Implementation Costs and Limited Digital Readiness Among Operators
The Upstream Oil and Gas Analytics Market faces obstacles due to high initial costs of deployment and integration. Many operators struggle with budget constraints, especially during periods of oil price volatility. It becomes difficult for smaller firms to justify investments in advanced platforms when returns are uncertain. Limited digital readiness and a shortage of skilled professionals further slow adoption. Companies often face challenges in aligning legacy infrastructure with modern analytics solutions. These barriers restrict widespread implementation despite the clear benefits of digital transformation.
Data Security Concerns and Complexity of Integration Across Systems
Cybersecurity risks and data privacy remain critical challenges for analytics adoption in upstream operations. The Upstream Oil and Gas Analytics Market is exposed to threats due to the reliance on interconnected platforms and cloud systems. It raises concerns about unauthorized access, operational disruptions, and loss of sensitive exploration data. Integration of diverse data sources across drilling, production, and maintenance processes also increases complexity. Operators often struggle to create seamless interoperability between legacy and modern technologies. These issues highlight the need for stronger safeguards and standardization to build trust and accelerate adoption.
Market Opportunities:
Expansion of Digital Twin Technology and Predictive Analytics in Upstream Operations
The Upstream Oil and Gas Analytics Market is creating opportunities through the adoption of digital twin technology and predictive analytics. Operators can simulate field conditions, optimize drilling, and extend equipment life by leveraging advanced models. It provides actionable insights that reduce risks and improve production planning. Predictive analytics is also enabling early identification of equipment failures, minimizing downtime, and improving cost control. Companies that embrace these technologies can enhance operational efficiency and achieve higher recovery rates. This opportunity strengthens the role of analytics as a core driver of transformation in upstream activities.
Rising Demand for Sustainable Operations and Carbon Management Solutions
Global energy transition initiatives are opening new opportunities for analytics platforms in upstream operations. The Upstream Oil and Gas Analytics Market is focusing on sustainability by supporting emission tracking, energy efficiency, and regulatory compliance. It enables operators to align with carbon reduction goals while maintaining profitability. Growing demand for transparency in reporting and resource optimization is creating value for solutions that balance production efficiency with environmental responsibility. Adoption of advanced analytics allows firms to integrate sustainability into their operating models. This direction positions analytics providers to play a central role in shaping responsible upstream development.
Market Segmentation Analysis:
By Deployment
The Upstream Oil and Gas Analytics Market is segmented into on-premises and cloud-based deployment. On-premises deployment remains significant among operators handling sensitive exploration and production data, offering strong control and security. It requires higher capital expenditure and longer integration time. Cloud-based deployment is expanding quickly due to scalability, cost efficiency, and ease of collaboration. It supports real-time data processing across dispersed locations, making it an attractive choice for modern upstream operations.
- For instance, to enhance its high-performance computing (HPC) for upstream applications like seismic processing, Shell upgraded its Houston data center with 864 new immersion-cooled servers to more effectively analyze decades of accumulated data.
By Service
The market includes professional services, integration and implementation, and support and maintenance. Professional services hold a strong position as companies rely on expert consultation for tailored analytics strategies. Integration and implementation services play a crucial role in aligning legacy systems with modern platforms. It enables seamless adoption and improved workflow management. Support and maintenance are growing steadily, ensuring system reliability and long-term operational efficiency for upstream operators.
- For instance, the data and analytics company TGS supports upstream clients with its professional services by creating a suite of interpretive geological products which includes 21 distinct models of North American basins.
By Application
The market covers exploration, drilling, asset management, reservoir management, and production optimization. Exploration and drilling benefit from predictive analytics that enhance accuracy and reduce risks in complex environments. Asset management and reservoir management are becoming vital as companies focus on maximizing recovery rates. It also drives growth in production optimization, where real-time monitoring reduces downtime, enhances safety, and improves operational efficiency. Each segment underscores the increasing dependence on analytics to strengthen upstream performance.
Segmentations:
By Deployment
- On-Premises
- Cloud-Based
By Service
- Professional Services
- Integration and Implementation
- Support and Maintenance
By Application
- Exploration
- Drilling
- Asset Management
- Reservoir Management
- Production Optimization
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America Leading Adoption with Strong Digital Infrastructure
North America accounted for 38% of the global Upstream Oil and Gas Analytics Market. The region’s leadership is driven by advanced digital infrastructure and strong adoption of analytics platforms. The United States and Canada continue to invest in predictive tools, automation, and cloud solutions for unconventional fields. It benefits from established service providers and government programs supporting digital transformation. The focus on optimizing shale production and managing operational risks ensures steady growth in adoption.
Asia-Pacific Emerging as a High-Growth Market with Expanding Investments
Asia-Pacific held 27% of the global Upstream Oil and Gas Analytics Market. The region is witnessing strong expansion due to large-scale upstream projects and rapid energy demand growth. China, India, and Australia are leading adopters of advanced analytics for drilling precision and resource optimization. It is gaining momentum through government-led initiatives encouraging digital transformation in energy operations. Investments by national oil companies in predictive and cloud-based platforms are accelerating regional market growth.
Europe Advancing with Focus on Efficiency and Sustainability
Europe represented 22% of the global Upstream Oil and Gas Analytics Market. The region’s steady growth reflects strict regulations, environmental goals, and emphasis on efficient resource management. Operators in the North Sea are leveraging analytics to maximize mature field output and enhance safety standards. It is witnessing increased adoption of IoT-based monitoring, digital twins, and emission tracking tools. Continued investment in sustainability and low-carbon operations strengthens the region’s position as a competitive market.
Key Player Analysis:
- Cisco Systems
- SAP
- SAS Institute
- Cognizant
- Deloitte
- Schlumberger NV
- Tableau Software
- Hewlett Packard Enterprise
- Hitachi
- IBM
- Teradata
- TIBCO Software
- Microsoft
- Oracle
Competitive Analysis:
The Upstream Oil and Gas Analytics Market is highly competitive, with global players focusing on digital innovation, partnerships, and advanced service portfolios. Key companies such as IBM Corporation, Oracle Corporation, Microsoft Corporation, Accenture, and SAP SE are expanding their presence through cloud-based solutions and AI-driven platforms. It is marked by strategic collaborations between oilfield operators and technology providers to improve drilling efficiency, asset performance, and predictive maintenance capabilities. Companies like Schlumberger, Halliburton, and Baker Hughes are integrating analytics into broader oilfield services, creating value-added solutions for operators. Regional players are also emerging with specialized offerings tailored to local market needs, particularly in Asia-Pacific and the Middle East. Competition is intensifying as vendors invest in sustainability-focused analytics tools that support emission tracking and regulatory compliance. The market rewards firms that combine domain expertise with advanced digital technologies to deliver measurable performance improvements in upstream operations.
Recent Developments:
- In June 2025, Cisco Systems introduced a new secure network architecture to speed up AI adoption in the workplace, launching new smart switches, secure routers, and expanding its Wi-Fi 7 and industrial networking portfolios.
- In July 2025, Cognizant launched Agent Foundry, a platform that enables enterprises to design, implement, and manage autonomous AI agents at scale, thereby improving business operations and decision-making by integrating human and AI agents.
- In June 2025, Hitachi Energy introduced a Compact Line Voltage Regulator, an all-in-one solution that merges voltage regulation and power transformation to improve the manageability of distribution grids.
Report Coverage:
The research report offers an in-depth analysis based on Deployment, Service, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Adoption of artificial intelligence and machine learning will expand, enabling advanced predictive capabilities and faster decision-making across upstream operations.
- Cloud-based platforms will gain greater traction, offering scalable solutions that support collaboration and reduce operational costs for oilfield operators.
- Integration of digital twins with analytics tools will transform exploration, drilling, and production optimization by simulating real-world conditions in real time.
- Demand for sustainability-focused analytics will rise, with operators relying on platforms that track emissions and align with carbon reduction targets.
- Cybersecurity will remain a priority, pushing vendors to strengthen data protection measures and build trust among energy producers.
- Emerging markets in Asia-Pacific and the Middle East will create growth opportunities as national oil companies accelerate digital transformation strategies.
- Advanced reservoir and asset management solutions will be widely adopted to maximize recovery rates from mature and complex oilfields.
- Partnerships between oilfield service providers and technology firms will intensify, driving innovation and integrated digital solutions.
- Real-time data monitoring will become standard, reducing downtime and improving safety performance in challenging upstream environments.
- Continuous regulatory pressure on sustainability and transparency will drive wider adoption of analytics platforms that support compliance and operational accountability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Upstream Oil and Gas Analytics, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Upstream Oil and Gas Analytics market projected to grow between 2024 and 2032?
What are the primary factors fueling the growth of the Upstream Oil and Gas Analytics market?
Who are the leading companies in the Upstream Oil and Gas Analytics market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Upstream Oil and Gas Analytics Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Upstream Oil and Gas Analytics Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 4380 million → 2032: USD 24799.7 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Upstream Oil and Gas Analytics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Upstream Oil and Gas Analytics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Upstream Oil and Gas Analytics Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Upstream Oil and Gas Analytics Market Drivers
- 3.3 Upstream Oil and Gas Analytics Market Restraints & Challenges
- 3.4 Upstream Oil and Gas Analytics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Upstream Oil and Gas Analytics Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Upstream Oil and Gas Analytics Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Upstream Oil and Gas Analytics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Upstream Oil and Gas Analytics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Upstream Oil and Gas Analytics Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Upstream Oil and Gas Analytics market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Upstream Oil and Gas Analytics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Upstream Oil and Gas Analytics Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Upstream Oil and Gas Analytics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Upstream Oil and Gas Analytics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Upstream Oil and Gas Analytics Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Upstream Oil and Gas Analytics Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Upstream Oil and Gas Analytics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Upstream Oil and Gas Analytics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Upstream Oil and Gas Analytics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Upstream Oil and Gas Analytics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Upstream Oil and Gas Analytics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Upstream Oil and Gas Analytics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Upstream Oil and Gas Analytics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
