
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Digital Signature Market Size 2023 | USD 1,636.40 million |
| U.S. Digital Signature Market, CAGR | 33.02% |
| U.S. Digital Signature Market Size 2032 | USD 16,037.56 million |
Market Overview:
The U.S. Digital Signature Market is projected to grow from USD 1,636.40 million in 2024 to an estimated USD 16,037.56 million by 2032, with a compound annual growth rate (CAGR) of 33.02% from 2024 to 2032.
Several factors are propelling the growth of the U.S. digital signature market. The increasing inclination of BFSI companies towards digitization has significantly transformed their processes, enhancing efficiency and transparency. Processes such as loan approvals and investment authorizations, which traditionally required physical signatures, are now being streamlined through digital signatures. Additionally, the implementation of regulations like the U.S. Government Paperwork Elimination Act (GPEA) encourages federal agencies to use electronic forms and signatures, further driving market adoption. The rise of remote work arrangements has amplified the need for secure and legally binding digital workflows. Moreover, enterprises are adopting cloud-based digital signature platforms to enable seamless multi-device access and reduce infrastructure costs.
Within the United States, the adoption of digital signatures is widespread across various regions, with significant growth observed in sectors such as BFSI, healthcare, and government. The BFSI sector, in particular, is the largest and fastest-growing category in the market, accounting for a substantial revenue share. This is attributed to the increasing acceptance of digital signature hardware and associated software tools, such as biometric systems and smart cards, which facilitate faster online transactions. Furthermore, the government's preference for digital signatures to reduce forgery and enhance public confidence in documentation has led to their widespread use in public offices, ensuring the integrity and authenticity of documents. States with large administrative and financial hubs, such as New York and California, are leading in terms of enterprise-grade implementation. In addition, academic institutions and legal bodies are embracing digital signatures to accelerate workflows and maintain document validity.
Market Insights:
- The U.S. Digital Signature Market is projected to grow from USD 1,636.40 million in 2024 to USD 16,037.56 million by 2032, registering a CAGR of 33.02%.
- The Global Digital Signature Market is projected to grow significantly, from USD 7,885.08 million in 2024 to USD 76,046.14 million by 2032, reflecting a strong CAGR of 32.75% during the forecast period.
- The BFSI sector is the leading adopter, streamlining operations like loan approvals and account management through secure digital signature solutions.
- Regulatory support from ESIGN, UETA, and GPEA enhances the legal validity of electronic signatures, accelerating adoption across sectors.
- Remote work models have significantly boosted the need for cloud-based digital signatures, enabling secure, multi-device access.
- Cybersecurity concerns and regulatory fragmentation pose challenges, requiring ongoing investment in secure and compliant technologies.
- States like California and New York are leading in enterprise-grade adoption, supported by strong financial and administrative infrastructures.
- Academic institutions, legal bodies, and healthcare providers are increasingly adopting digital signatures to streamline workflows and ensure document authenticity.
Report Scope
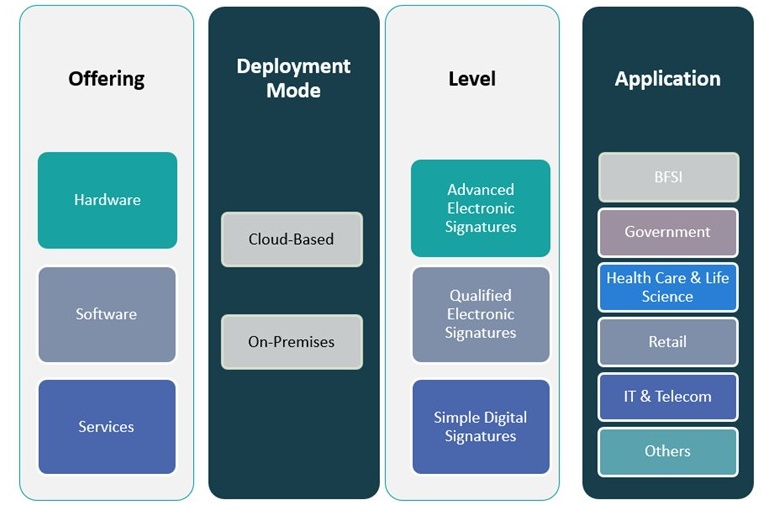
This report segments U.S. Digital Signature Market as follow
Market Drivers:
Regulatory Support and Legal Validity
The U.S. digital signature market benefits significantly from strong regulatory frameworks that validate the use of electronic signatures in both public and private sector transactions. Legislation such as the Electronic Signatures in Global and National Commerce (ESIGN) Act and the Uniform Electronic Transactions Act (UETA) has provided the foundational legal support, granting digital signatures the same enforceability as traditional handwritten signatures. For example, DocuSign reports that 83% of e-signature adopters believe digital signatures are more secure than traditional paper signatures, reinforcing business and consumer confidence in the technology. This legal recognition has accelerated adoption, especially in sectors that demand compliance and record integrity, such as legal services, insurance, and government agencies. The structured framework has not only reduced operational risks but has also instilled confidence among businesses and consumers regarding the legitimacy and security of digital signing processes.
Increased Digitization Across Key Industries
Digitization trends across banking, financial services, insurance (BFSI), and healthcare sectors are acting as strong catalysts for the growth of the digital signature market in the U.S. Companies are rapidly automating workflows to improve turnaround time, reduce paperwork, and enhance customer experience. In the BFSI sector, digital signatures are streamlining document-intensive operations such as loan processing, account opening, and investment approvals. Similarly, healthcare providers are using electronic signatures to manage consent forms, patient documentation, and internal compliance procedures. The shift toward end-to-end digital transformation has prompted enterprises to adopt secure, scalable digital signature solutions to meet rising efficiency demands and maintain competitive advantage.
Remote Work and Cloud Integration
The transition to remote and hybrid work environments following the COVID-19 pandemic has significantly boosted the adoption of digital signature technologies. Organizations that once relied heavily on physical document handling have migrated to digital workflows to support distributed teams and ensure business continuity. Cloud-based digital signature platforms offer remote access, multi-device support, and secure integration with other enterprise software tools such as document management systems and CRM platforms. This has allowed employees and stakeholders to sign, verify, and track documents from any location, reducing delays and maintaining legal compliance. As remote work persists as a long-term model, businesses are expected to further invest in flexible, cloud-native digital signing solutions.
Security and Risk Mitigation
Security remains a top concern for organizations handling sensitive data and contractual obligations. Digital signatures provide a tamper-evident and encrypted solution that ensures the integrity of documents and the authenticity of the signer. Advanced features such as multi-factor authentication, biometric verification, and audit trails are now integrated into leading digital signature solutions to prevent fraud and unauthorized access. Proofpoint, for example, employs AES-256 encryption and ECDSA algorithms to protect digital signatures from forgery and identity theft5. Biometric authentication, including fingerprint and facial recognition, is increasingly integrated to further strengthen identity verification and prevent unauthorized access. In industries like legal, real estate, and government, where document accuracy and identity verification are critical, these capabilities significantly mitigate risks. The growing incidence of cyber threats has further elevated the demand for robust digital signature platforms as part of a comprehensive cybersecurity strategy.
Market Trends:
Cloud-First Adoption Models
The U.S. digital signature market is undergoing a major transformation driven by the adoption of cloud-first strategies across enterprises. Organizations are increasingly deploying cloud-native digital signature solutions to replace traditional on-premise models, recognizing the benefits of scalability, lower upfront investment, and remote accessibility. This shift has been especially prominent among small to mid-sized enterprises (SMEs) that seek rapid deployment and flexible subscription models without the burden of maintaining extensive IT infrastructure. Cloud-based platforms also support seamless integration with existing enterprise systems such as CRMs and document management tools, making them attractive for firms aiming to digitize end-to-end processes. This growing demand for agile cloud solutions continues to reshape the vendor landscape, prompting providers to offer customizable, SaaS-based digital signature packages.
Expansion of API-Driven Ecosystems
Another notable trend is the proliferation of API-based integration frameworks that allow digital signature solutions to be embedded directly within enterprise applications. DocuSign’s eSignature API, for instance, allows organizations to integrate electronic signing, document tracking, and identity verification into existing platforms such as Salesforce, Microsoft 365, and custom apps. These integrations enable real-time document authentication and signing, without switching between applications, significantly improving operational efficiency. Furthermore, API-enabled platforms allow companies to develop bespoke workflows that meet industry-specific compliance and user interface requirements. The push toward automation and the streamlining of business operations are compelling IT departments to embrace digital signature technologies that are adaptable, programmable, and ecosystem-friendly.
Mobile-Responsive Platforms and Biometric Enhancements
The rise in mobile usage among professionals has prompted providers to develop mobile-first digital signature applications with robust functionality. These mobile-optimized solutions enable users to securely sign, send, and manage documents via smartphones and tablets. For instance, financial institutions, logistics firms, and legal services are capitalizing on mobile solutions to execute time-sensitive contracts in transit or during remote consultations. In parallel, there is a growing integration of biometric authentication features-such as fingerprint recognition and facial scanning-to ensure secure user validation. These technologies not only add a layer of security but also align with the growing user expectation for frictionless digital experiences, contributing to faster decision-making and higher client satisfaction.
Sustainability and Paperless Transformation
Digital signature adoption is increasingly tied to broader organizational sustainability initiatives. As companies aim to minimize their environmental footprint, transitioning to paperless operations is gaining momentum. Digital signatures eliminate the need for physical documentation, mailing, and storage, thereby reducing paper waste and energy consumption. In sectors like government administration, education, and human resources, where documentation is voluminous and recurring, digital workflows support eco-friendly practices while enhancing productivity. The alignment of digital signature usage with Environmental, Social, and Governance (ESG) goals is driving further investment, positioning the technology not just as a business enabler, but also as a contributor to long-term sustainability strategies.
Market Challenges Analysis:
Regulatory Fragmentation and Compliance Complexity
One of the primary challenges in the U.S. digital signature market is the lack of a universally harmonized legal and regulatory framework across all states and industries. While federal laws such as the ESIGN Act and the UETA offer legal recognition of electronic signatures, interpretations and implementations can vary at the state level and among different sectors. New York, for example, has not adopted the Uniform Electronic Transactions Act (UETA) but instead enforces its own Electronic Signatures and Records Act (ESRA), which establishes legal equivalence for electronic and handwritten signatures but also creates unique compliance requirements for government agencies and regulated documents. This regulatory fragmentation complicates compliance for organizations operating across multiple jurisdictions. Enterprises must often invest in legal consultations and tailor their digital signature practices to align with diverse regulatory requirements, increasing operational costs and slowing adoption, particularly for smaller businesses.
Cybersecurity Threats and Data Integrity Concerns
As digital signatures become more integrated into critical enterprise workflows, concerns about cybersecurity risks and data breaches are intensifying. Sophisticated cyberattacks targeting digital signature infrastructure such as private key theft, identity spoofing, and document tampering pose a significant threat to trust and data integrity. Although advanced encryption protocols and authentication layers are in place, the evolving nature of cyber threats demands continuous investment in secure technologies. Companies that fail to implement rigorous security protocols risk reputational damage, regulatory penalties, and operational disruption, acting as a restraint to wider adoption.
Technological Integration and User Resistance
Integrating digital signature solutions with legacy systems remains a technical and logistical hurdle for many organizations, especially those with complex document workflows and outdated infrastructure. Customization and compatibility issues can result in extended implementation timelines and higher integration costs. Additionally, resistance to change among internal stakeholders especially in industries where manual processes have long been the norm can hinder adoption. Employees may require extensive training or exhibit reluctance to trust digital alternatives, further slowing organizational transition. Overcoming these barriers necessitates strong change management strategies and ongoing user education.
Market Opportunities:
The U.S. digital signature market holds substantial growth opportunities as enterprises increasingly embrace comprehensive digital transformation strategies. The surge in remote work, digital onboarding, and paperless documentation across sectors such as legal, real estate, education, and healthcare presents a fertile ground for widespread adoption of digital signature solutions. Businesses are seeking tools that enhance workflow efficiency, accelerate transaction cycles, and maintain compliance-all of which digital signatures facilitate. The rising demand for seamless integrations with enterprise platforms like customer relationship management (CRM), enterprise resource planning (ERP), and cloud-based document management systems is creating space for solution providers to offer value-added, tailored services. Moreover, as organizations adopt more mobile and cross-platform solutions, vendors that prioritize user-centric design and flexible deployment models are poised to gain competitive advantage.
Another key area of opportunity lies within public sector institutions and heavily regulated industries, where trust, traceability, and compliance are paramount. Government agencies at the federal, state, and municipal levels are increasingly transitioning to digital processes to improve transparency, reduce fraud, and lower administrative overhead. Simultaneously, sectors such as banking, insurance, and pharmaceuticals are under pressure to modernize operations while adhering to stringent regulatory standards, making digital signature platforms critical components of their compliance infrastructure. Additionally, the growing focus on environmental sustainability and corporate social responsibility encourages organizations to reduce paper dependency, further driving market demand. These trends present significant room for innovation and market expansion in both product development and service delivery.
Market Segmentation Analysis:
The U.S. digital signature market exhibits a diverse segmentation landscape, offering tailored solutions across various industries and technological preferences.
By offering segment, the market is divided into hardware, software, and services. While software solutions hold the dominant share due to their scalability and ease of integration, the demand for complementary services such as implementation, training, and technical support is steadily growing. Hardware-based digital signature tools, including biometric verification devices and smart cards, also maintain relevance in high-security environments such as government and defense.
By deployment mode, cloud-based solutions are rapidly gaining traction, driven by their flexibility, cost-efficiency, and remote accessibility-particularly suitable for small and mid-sized enterprises. On-premises deployment continues to find favor among large organizations with strict data control policies, especially in sectors handling sensitive client or national data.
By level, including simple digital signatures, advanced electronic signatures, and qualified electronic signatures. Simple digital signatures are commonly adopted for internal documentation, while advanced and qualified signatures are increasingly used for transactions requiring strong legal backing and identity verification-especially within the BFSI and healthcare sectors.
By application segment, BFSI remains the leading adopter of digital signature solutions, followed closely by government and healthcare & life sciences, which require compliance with stringent regulations. The IT & telecom and retail sectors are also showing strong momentum, driven by the need for secure digital transaction processes. The market’s multi-segmented structure enables providers to customize offerings, ensuring continued growth across industry verticals.
Segmentation:
By Offering Segment:
- Hardware
- Software
- Services
By Deployment Mode Segment:
- Cloud-Based
- On-Premises
By Level Segment:
- Advanced Electronic Signatures
- Qualified Electronic Signatures
- Simple Digital Signatures
By Application Segment:
- BFSI (Banking, Financial Services, and Insurance)
- Government
- Healthcare & Life Sciences
- Retail
- IT & Telecom
- Others
Regional Analysis:
The U.S. digital signature market exhibits regional variations influenced by factors such as technological infrastructure, regulatory frameworks, and industry-specific adoption rates. These differences contribute to the overall growth and development of the market across various states and regions.
Northeast Region
The Northeast, encompassing states like New York, Massachusetts, and Pennsylvania, is a significant contributor to the digital signature market. This region benefits from a concentration of financial institutions, legal firms, and healthcare organizations that require secure and efficient digital transaction solutions. The presence of these industries drives the demand for digital signature technologies, fostering market growth in the area.
Midwest Region
In the Midwest, states such as Illinois, Ohio, and Michigan are experiencing steady growth in the adoption of digital signatures. The manufacturing and automotive sectors, prevalent in this region, are increasingly integrating digital signature solutions to streamline supply chain operations and enhance document security. Additionally, educational institutions in the Midwest are adopting digital signatures for administrative processes, contributing to market expansion.
Southern Region
The Southern states, including Texas, Florida, and Georgia, are witnessing a surge in digital signature adoption, particularly in the real estate, healthcare, and government sectors. The region's growing emphasis on digital transformation and e-governance initiatives supports the implementation of digital signature solutions. Furthermore, the increasing number of small and medium-sized enterprises (SMEs) in the South adopting digital tools for business operations contributes to the market's growth.
Western Region
The Western region, notably California, Washington, and Colorado, leads in the adoption of digital signature technologies. This area is characterized by a robust technology sector and a high concentration of startups and tech companies that prioritize digital solutions for operational efficiency. The region's progressive regulatory environment and emphasis on innovation further accelerate the adoption of digital signatures across various industries.
Key Player Analysis:
- DocuSign
- HelloSign
- OneSpan
- Notarize
- PandaDoc
Competitive Analysis:
The U.S. digital signature market features a competitive landscape characterized by the presence of well-established players and emerging technology firms striving to innovate and capture market share. Key companies such as DocuSign, Adobe Inc., Entrust, Zoho Corporation, and SignNow dominate the market by offering scalable, secure, and user-friendly digital signature solutions tailored to various industries. These players consistently invest in research and development to enhance product capabilities, focusing on cloud integration, mobile accessibility, and advanced authentication features. Strategic partnerships, mergers, and acquisitions are common tactics employed to expand service portfolios and reach new customer segments. Additionally, several niche providers are entering the market with specialized offerings that cater to sector-specific compliance requirements. Competitive intensity is further driven by the rising demand for API-enabled platforms and customizable workflows. As organizations continue to prioritize digital transformation, market players are expected to differentiate through innovation, regulatory alignment, and superior customer experience.
Recent Developments:
- In April 2025, DocuSign introduced a redesigned Partner Program aimed at accelerating partner growth and customer value in the era of Intelligent Agreement Management (IAM). This new program features specializations, tailored tracks, and advanced go-to-market support, empowering partners to better serve customers across eSignature and contract lifecycle management solutions.
- on April 18, 2025, DocuSign expanded its strategic partnership with Cognizant to enhance customer support and drive digital transformation. This collaboration focuses on optimizing customer service management and streamlining agreement processes globally, leveraging Cognizant’s expertise in AI and digital transformation to advance the DocuSign IAM platform.
- In March, OneSpan launched several significant updates to its digital agreement products. These enhancements included new eSignature integrations with major platforms like Workday and Salesforce, SMS notifications, FIDO passkeys for signers, and improved analytics. OneSpan also released features such as ad hoc signing groups, OAuth 2.0 support, and enhanced transaction dashboards, all aimed at improving flexibility, security, and user experience for digital agreements.
Market Concentration & Characteristics:
The U.S. digital signature market exhibits a moderately concentrated structure, with a few dominant players holding substantial market share alongside a growing number of specialized vendors. Companies like DocuSign and Adobe command strong brand recognition and extensive customer bases, benefiting from early market entry, robust security infrastructure, and comprehensive service offerings. Despite this dominance, the market continues to attract new entrants due to low entry barriers in software development and rising demand across diverse sectors. The market is characterized by rapid innovation, frequent technological upgrades, and a focus on interoperability with enterprise software ecosystems. As digital transformation accelerates, scalability, ease of integration, and regulatory compliance have become critical product attributes. While large enterprises favor feature-rich, enterprise-grade platforms, small and medium-sized businesses seek cost-effective, flexible solutions. The presence of both global providers and niche startups creates a dynamic environment where product differentiation and customer-centric strategies play vital roles in shaping competitive success.
Report Coverage:
The research report offers an in-depth analysis based on Offering, Deployment Mode, Level and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising demand for secure digital workflows will continue to drive adoption across finance, healthcare, and legal sectors.
- Cloud-native digital signature platforms will dominate, offering scalability and seamless remote access.
- Integration with blockchain and AI will enhance verification accuracy and fraud detection capabilities.
- Mobile-optimized solutions will gain traction as workforce mobility and smartphone usage increase.
- Regulatory developments will standardize compliance requirements, encouraging broader adoption.
- Sustainability goals will promote paperless operations, aligning digital signatures with corporate ESG strategies.
- Small and medium-sized enterprises will emerge as a key customer segment, adopting cost-efficient SaaS models.
- Government digitization initiatives will expand usage across federal, state, and municipal agencies.
- Competitive pressure will intensify, leading to feature-rich, user-centric innovations by market leaders and startups alike.
- Strategic collaborations between software vendors and enterprise tech platforms will streamline adoption and integration.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Regulatory Support and Legal Validity
Federal laws such as the ESIGN Act and UETA provide digital signatures with the same legal standing as handwritten signatures, boosting confidence and accelerating adoption in sectors requiring compliance and record integrity.
Digitization Across Key Industries
BFSI, healthcare, and government sectors are rapidly digitizing workflows to improve efficiency and customer experience, driving demand for secure and scalable digital signature solutions.
Remote Work and Cloud Integration
The shift to remote and hybrid work models has increased the need for cloud-based digital signature platforms, enabling secure, multi-device access and supporting distributed teams.
Security and Risk Mitigation
Growing concerns over data integrity and cyber threats are prompting organizations to adopt digital signatures with advanced encryption, biometric authentication, and audit trails to ensure document authenticity and prevent fraud.
Sustainability and Paperless Transformation
Corporate sustainability initiatives and ESG goals are encouraging organizations to reduce paper usage, making digital signatures a key enabler of paperless, environmentally friendly operations.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the U.S. Digital Signature Market?
What factors are driving the growth of the U.S. Digital Signature Market?
What are some challenges faced by the U.S. Digital Signature Market?
Who are the major players in the U.S. Digital Signature Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Level
- 1.2.1 Simple Digital Signatures
- 1.2.2 Advanced Electronic Signatures
- 1.2.3 Qualified Electronic Signatures
- 1.3 By Offering
- 1.3.1 Hardware
- 1.3.2 Software
- 1.3.3 Services
- 1.4 By Application
- 1.4.1 BFSI (Banking, Financial Services, and Insurance)
- 1.4.2 Government
- 1.4.3 Healthcare & Life Sciences
- 1.4.4 Retail
- 1.4.5 IT & Telecom
- 1.4.6 Others
- 1.5 By Deployment Mode
- 1.5.1 Cloud-Based
- 1.5.2 On-Premises
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,636.40 million → 2032: USD 16,037.56 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Digital Signature Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Digital Signature Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. Digital Signature Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. Digital Signature Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Digital Signature Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Digital Signature Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Digital Signature Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Digital Signature Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,636.40 million → 2032: USD 16,037.56 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Digital Signature Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Level - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Simple Digital Signatures
- 12.3.7.2 Advanced Electronic Signatures
- 12.3.7.3 Qualified Electronic Signatures
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Offering - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hardware
- 12.4.7.2 Software
- 12.4.7.3 Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 BFSI (Banking, Financial Services, and Insurance)
- 12.5.7.2 Government
- 12.5.7.3 Healthcare & Life Sciences
- 12.5.7.4 Retail
- 12.5.7.5 IT & Telecom
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Deployment Mode - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Cloud-Based
- 12.6.7.2 On-Premises
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Digital Signature End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 U.S. Digital Signature Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 U.S. Digital Signature Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 U.S. Digital Signature Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 DocuSign
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Adobe
- 18.4 OneSpan
- 18.5 HelloSign
- 18.6 PandaDoc
- 18.7 Entrust
- 18.8 SignNow
- 18.9 Zoho Corporation
- 18.10 Notarize
- 18.11 SignEasy
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

