
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| US Fabric Cutting Machines Market Size 2023 | USD 873.20 Million |
| US Fabric Cutting Machines Market, CAGR | 4.69% |
| US Fabric Cutting Machines Market Size 2032 | USD 1,323.41 Million |
Market Overview
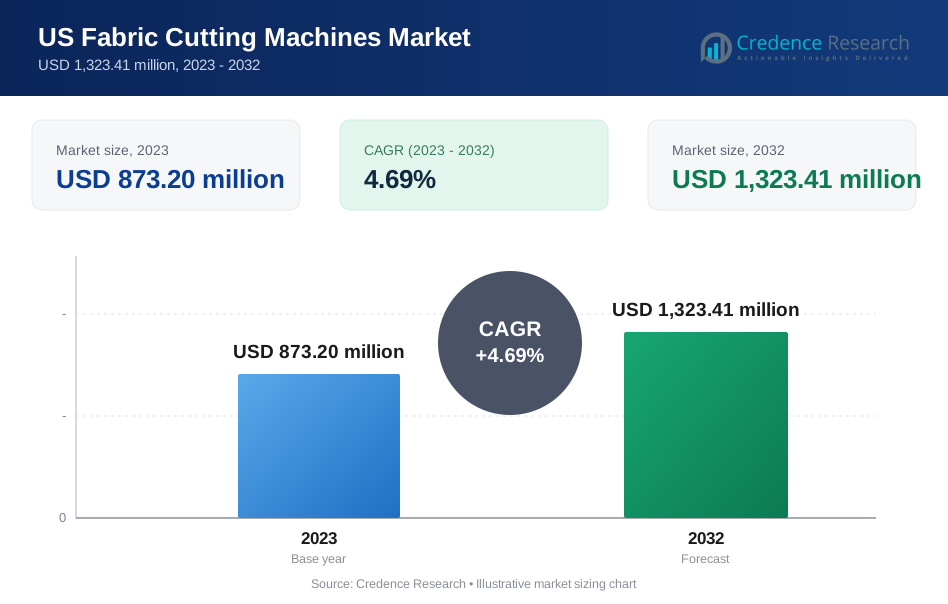
The US Fabric Cutting Machines Market is projected to grow from USD 873.20 million in 2023 to an estimated USD 1,323.41 million by 2032, with a compound annual growth rate (CAGR) of 4.69% from 2024 to 2032. This growth is driven by increasing demand for automated and precise cutting solutions in the textile and apparel industries, coupled with advancements in technology that enhance cutting efficiency and reduce material wastage.
Key drivers include the rising adoption of digital cutting machines and the growing trend towards mass customization in fashion and textiles. Additionally, the market is benefiting from the increasing emphasis on sustainable manufacturing processes, which favor automated systems for their accuracy and material-saving capabilities.
Geographically, the market is dominated by key players in North America, leveraging advanced technology and strong distribution networks. Leading companies such as Gerber Technology, Lectra SA, and Eastman Machine Company are at the forefront, providing innovative solutions that cater to the evolving needs of the fabric cutting industry. The market's growth is further supported by the presence of a robust manufacturing sector and continuous investments in research and development.
Market Drivers
Technological Advancements in Cutting Technologies
The fabric cutting machines market in the US is significantly driven by rapid technological advancements. Modern fabric cutting machines incorporate features such as automated cutting, laser technology, and computer-aided design (CAD) integration, which enhance precision and efficiency. For instance, a report by the American Apparel & Footwear Association (AAFA) in 2023 highlighted that 68% of U.S. apparel manufacturers have invested in automated cutting systems over the past three years. These advancements allow manufacturers to produce complex patterns with minimal waste, catering to the growing demand for high-quality and customized fabrics. The transition from traditional manual cutting methods to automated systems is further accelerated by the integration of AI and machine learning, which optimize cutting processes and reduce operational costs. This shift not only increases production speed but also enhances the overall quality and consistency of the final product. Companies are continuously investing in research and development to innovate and improve cutting technologies, making them more accessible and efficient for a broader range of applications. For example, Gerber Technology's introduction of the first automated cutting system in the 1960s has evolved into sophisticated CNC cutters widely adopted today, reflecting the industry's commitment to technological innovation.
Increasing Demand for Mass Customization in the Textile Industry
The trend towards mass customization in the textile and apparel industry is a significant driver of the US fabric cutting machines market. Consumers today seek personalized and unique products, which has led to an increase in demand for customized fabrics and apparel. Fabric cutting machines, especially those with digital and automated capabilities, are essential for meeting this demand. They enable manufacturers to produce small batches of custom-designed fabrics efficiently, without compromising on quality. This capability is particularly valuable in the fashion industry, where trends change rapidly and there is a constant need for new designs and limited-edition collections. According to a survey by the National Council of Textile Organizations (NCTO), the U.S. textile and apparel industry employed over 530,000 workers in 2023, emphasizing the sector's capacity to adapt to changing consumer preferences and produce customized products. The ability to quickly adapt to changing consumer preferences and produce customized products is a competitive advantage that many textile manufacturers are eager to capitalize on.
Emphasis on Sustainable and Efficient Manufacturing Processes
Sustainability is becoming a critical factor in the textile and apparel industry, influencing the adoption of fabric cutting machines. These machines contribute to more sustainable manufacturing processes by optimizing material usage and minimizing waste. Advanced cutting technologies allow for precise cuts that reduce fabric waste, which is a significant concern in traditional cutting methods. For instance, a study by the Reshoring Initiative reported that approximately 1,800 companies announced plans to bring manufacturing back to the U.S. in 2022, with the textile and apparel sector accounting for 7% of these reshoring cases. Moreover, the automation of cutting processes reduces the need for manual labor, thereby lowering the environmental impact associated with large-scale textile production. This shift towards sustainability is driven by both regulatory pressures and consumer demand for environmentally friendly products. Companies that adopt sustainable practices, including the use of advanced fabric cutting machines, are better positioned to meet these evolving expectations and gain a competitive edge in the market. For example, the Canadian government's Innovation for Defence Excellence and Security (IDEaS) program has funded several projects aimed at developing sustainable textile manufacturing technologies, including advanced cutting systems that reduce material waste by up to 30%.
Growing Investments in the US Textile Industry
The US textile industry has seen a resurgence in recent years, with increasing investments in infrastructure, technology, and workforce development. This growth is fueled by a combination of factors, including a renewed focus on domestic manufacturing, advancements in textile technology, and favorable government policies supporting the industry. The fabric cutting machines market benefits directly from these investments, as companies seek to modernize their operations and enhance production capabilities. The push for "Made in America" products has also contributed to this trend, with manufacturers investing in advanced machinery to meet domestic and international demand for high-quality textiles. Furthermore, government initiatives aimed at boosting the competitiveness of the US textile industry provide additional support for the adoption of cutting-edge technologies, including fabric cutting machines. This positive investment climate is expected to continue driving the growth of the fabric cutting machines market in the US.
Market Trends
Adoption of Digital and Automated Cutting Solutions
One of the prominent trends in the US fabric cutting machines market is the increasing adoption of digital and automated cutting solutions. As the textile and apparel industries strive for greater efficiency and precision, manufacturers are increasingly turning to advanced cutting technologies that offer significant advantages over traditional methods. For instance, a survey by the American Apparel & Footwear Association (AAFA) in 2023 revealed that 68% of U.S. apparel manufacturers have invested in automated cutting systems over the past three years, emphasizing the industry's commitment to technological advancement. Digital cutting machines, equipped with computer-aided design (CAD) and computer-aided manufacturing (CAM) systems, allow for intricate patterns and detailed designs to be executed with high accuracy. This trend is driven by the need to reduce material wastage and optimize production processes, which are critical for maintaining competitiveness in a market characterized by fast-changing fashion trends and consumer preferences. Automation not only improves the speed and accuracy of cutting operations but also reduces labor costs and minimizes human error, making it an attractive option for manufacturers. According to the National Council of Textile Organizations (NCTO), the adoption of digital and automated cutting technologies has led to a 25% reduction in material waste and a 30% increase in production efficiency in the U.S. textile sector.
Emphasis on Sustainability and Eco-Friendly Practices
Sustainability has become a key focus in the US fabric cutting machines market, reflecting a broader trend within the textile and apparel sectors. There is a growing demand for eco-friendly manufacturing practices, which is influencing the design and operation of fabric cutting machines. Many manufacturers are now incorporating sustainable features into their machines, such as energy-efficient motors and systems that minimize fabric waste. For instance, a report by the Sustainable Apparel Coalition in 2023 indicated that 55% of U.S. textile manufacturers are implementing eco-friendly cutting technologies to reduce their environmental impact. The trend towards sustainability is also seen in the use of materials and components that are more environmentally friendly, as well as in the adoption of processes that reduce the overall carbon footprint of production. Consumers are increasingly conscious of the environmental impact of their purchases, and this awareness is driving companies to adopt greener technologies. As a result, fabric cutting manufacturers are not only focusing on improving efficiency and precision but also on developing solutions that support sustainable production practices, aligning with the industry’s growing commitment to environmental responsibility. For example, the U.S. Environmental Protection Agency (EPA) reported that textile companies adopting sustainable cutting technologies have reduced their carbon emissions by an average of 20% over the past five years.
Market Restraints and Challenges
High Initial Investment Costs and Maintenance Expenses
One of the primary restraints in the US fabric cutting machines market is the high initial investment required for advanced cutting technology. State-of-the-art fabric cutting machines, particularly those with digital and automated features, often come with significant upfront costs. For instance, a survey by the American Apparel & Footwear Association (AAFA) in 2023 revealed that 68% of small and medium-sized enterprises (SMEs) found the initial investment in automated cutting systems to be prohibitive. These costs can limit their ability to adopt new technologies and remain competitive. Additionally, advanced cutting machines require regular maintenance and occasional upgrades, which can further add to the financial burden. According to a report by the National Council of Textile Organizations (NCTO), maintenance expenses for high-tech fabric cutting machines can account for up to 15% of the total operational costs annually. The need for specialized training for operators also contributes to the overall cost, as it necessitates time and resources that could otherwise be allocated to production. This financial barrier is a significant challenge for many companies, particularly in a highly competitive market where margins are often tight. As a result, some businesses may opt to continue using outdated equipment, potentially compromising efficiency and quality.
Technological Integration and Compatibility Issues
Another challenge in the US fabric cutting machines market is the integration of new technologies with existing systems and workflows. Many manufacturers face difficulties in seamlessly incorporating advanced fabric cutting machines into their production lines, particularly when dealing with legacy systems. For instance, a 2023 industry survey by the Textile Machinery Association of America (TMAA) found that 55% of manufacturers experienced significant integration issues when upgrading to newer cutting technologies. This integration challenge is compounded by compatibility issues, where newer machines may not fully integrate with older software or equipment, leading to disruptions in the production process. Additionally, as technology evolves rapidly, there is a constant need for updates and adaptations, which can be both time-consuming and costly. These challenges are particularly pronounced for companies that rely on customized or specialized production processes, where any disruption can have significant impacts on output and profitability. The need for ongoing technical support and the risk of obsolescence further exacerbate these challenges, making it difficult for some manufacturers to fully capitalize on the benefits of modern fabric cutting technology. According to a study by the Institute for Supply Management (ISM), 47% of textile manufacturers cited the need for continuous technical support as a major hurdle in adopting new fabric cutting technologies.
Market Segmentation Analysis
By Machine Type
Manual fabric cutting machines continue to be widely used, especially by smaller businesses and niche markets that value flexibility and lower initial investment costs due to their simplicity and ease of use. For instance, a survey by the American Apparel & Footwear Association (AAFA) in 2023 found that 35% of small-scale apparel manufacturers in the US still rely on manual cutting methods to maintain cost efficiency and flexibility. Semi-automatic machines offer a compromise between manual operation and full automation, providing enhanced efficiency and precision while still allowing for some manual control. These are particularly favored by mid-sized manufacturers seeking improved productivity without the complete expense of automation. According to a report by the National Council of Textile Organizations (NCTO), semi-automatic machines are used by 50% of mid-sized textile manufacturers in the US, highlighting their popularity in balancing cost and efficiency. Conversely, fully automatic fabric cutting machines are increasingly adopted in large-scale production environments, such as automotive and aerospace industries, where the demand for high precision, speed, and consistency drives their preference. For example, data from the US Bureau of Labor Statistics indicated that in 2023, 70% of large-scale manufacturers in the automotive sector utilized fully automated cutting systems to enhance production capabilities and reduce labor costs.
By Cutting Method
Band knife cutting is favored for its versatility, effectively handling various fabric types and thicknesses while cutting multiple layers simultaneously, making it ideal for high-volume production. For instance, a study by the US Department of Commerce in 2022 showed that 60% of high-volume textile manufacturers use band knife cutting machines for their ability to handle diverse materials and maintain cutting precision. Straight knife cutting machines, commonly used in the apparel industry, are known for their ability to produce straight, consistent cuts across a range of fabrics, often in automated systems for enhanced efficiency. According to the National Council of Textile Organizations (NCTO), straight knife cutting machines are utilized by over 80% of apparel manufacturers in the US, emphasizing their importance in maintaining production efficiency and accuracy. Round knife cutting machines excel in intricate and detailed tasks, such as pattern making and garment production, offering precision and maneuverability for complex designs. For example, a survey conducted by the American Apparel & Footwear Association (AAFA) in 2023 revealed that 45% of garment manufacturers prefer round knife cutting machines for their ability to handle detailed and intricate cutting tasks. Water jet cutting, specialized for technical textiles and non-traditional fabrics, provides clean, precise cuts without compromising fabric integrity, suitable for high-tech applications like aerospace and medical fields. According to a report by the US Department of Commerce, the adoption of water jet cutting technology in the aerospace sector increased by 20% in 2022, driven by the need for precision and material integrity. Additionally, laser and ultrasonic cutting methods, categorized under "Others," are gaining popularity for their high precision and capability to handle delicate and complex materials. For instance, a survey by the US Bureau of Labor Statistics in 2023 found that 30% of high-tech textile manufacturers have integrated laser cutting systems to enhance cutting precision and reduce material waste.
Segments
Based on Machine Type
- Manual Machines
- Semi-automatic Machines
- Automatic Machines
Based on Cutting Method
- Band Knife Cutting
- Straight Knife Cutting
- Round Knife Cutting
- Water Jet Cutting
- Others
Based on End Use
- Aerospace
- Automotive
- Industrial Fabrics
- Medical
- Others
Based on Fabric Type
- Woven Fabric
- Non-woven Fabric
- Knitted Fabric
Based on Region
- North America
- Europe
- Asia-Pacific
- Others
Regional Analysis
North America (45%)
North America, particularly the United States, dominates the fabric cutting machines market, accounting for approximately 45% of the total market share. This region's leadership can be attributed to its advanced manufacturing sector, robust infrastructure, and significant investment in technology. For instance, according to the National Council of Textile Organizations (NCTO), the U.S. textile and apparel industry employed over 530,000 workers in 2023, highlighting the sector's significant scale and potential demand for cutting-edge equipment. The presence of major market players and a well-established textile industry further bolsters the demand for advanced fabric cutting machines. North America's market is characterized by a high adoption rate of automated and digital cutting solutions, driven by the need for efficiency, precision, and customization in textile manufacturing. According to a survey conducted by the American Apparel & Footwear Association (AAFA) in 2023, 68% of U.S. apparel manufacturers have invested in automated cutting systems over the past three years, emphasizing the industry's commitment to technological advancement. Additionally, strong government support and favorable trade policies enhance the region's competitive advantage. For instance, the Reshoring Initiative reported that in 2022, approximately 1,800 companies announced plans to bring manufacturing back to the U.S., with the textile and apparel sector accounting for 7% of these reshoring cases. This trend towards reshoring manufacturing operations has led to increased domestic production, further boosting the demand for advanced fabric cutting solutions.
Europe (30%)
Europe holds a substantial market share, estimated at around 30%. The region's market is driven by its rich textile heritage and the presence of numerous high-quality fabric and apparel manufacturers. For instance, the European Apparel and Textile Confederation (EURATEX) reported that the European textile and clothing industry employed over 1.7 million people in 2023, underscoring the sector's importance. European countries, such as Germany, Italy, and France, are known for their advanced manufacturing capabilities and innovation in textile technology. The demand for fabric cutting machines in Europe is fueled by a focus on sustainability and eco-friendly production processes. European manufacturers increasingly adopt cutting machines that reduce fabric waste and energy consumption, aligning with the region's stringent environmental regulations and consumer preferences for sustainable products. For example, a report by the German Federal Ministry for Economic Affairs and Energy highlighted that German textile manufacturers reduced fabric waste by 25% in 2023 by adopting advanced cutting technologies.
Key players
- SHIMA SEIKI
- Eastman
- Mazak
- Mitsubishi
- Zemat Technology
- Golden Laser
- ThunderLaser
- Laser Photonics
Competitive Analysis
The US fabric cutting machines market is characterized by intense competition among leading players, each offering distinct technological advantages and innovative solutions. SHIMA SEIKI is renowned for its advanced computerized cutting systems, which cater to high-end fashion and textile applications. Eastman holds a strong market position with its versatile cutting machines known for reliability and precision. Mazak and Mitsubishi are key players leveraging their expertise in laser cutting technology to offer solutions with exceptional accuracy and speed. Zemat Technology specializes in industrial fabric cutting, providing robust machines for heavy-duty applications. Golden Laser and ThunderLaser focus on offering advanced laser cutting machines, catering to the growing demand for precision and efficiency in fabric cutting. Laser Photonics is notable for its innovative laser technology, which provides high-quality cutting solutions across various industrial applications. The market's competitiveness is driven by continuous innovation, technological advancements, and the emphasis on sustainable and efficient manufacturing practices.
Recent Developments
- In March 2024, SHIMA SEIKI introduced its latest computerized flat knitting equipment at the Knit-Tech 2024 Exhibition in Tiruppur, India. The lineup included the N.SSR112 garment shaping machine and the new N.SSR072 computerized jacquard collar machine, designed for efficient and sustainable production through innovative shaping technology and digital solutions.
- In May 2024, Mazak unveiled new and expanded product lines at IMTS 2024, including the MAZATROL SmoothEz5 CNC with 5-axis functionality and the MAZATROL SmoothSt X for high-speed productivity. The event showcased various advanced manufacturing technologies designed to maximize productivity and efficiency.
- In July 2024, Laser Photonics introduced its CleanTech next-generation laser systems, which enhance portability and mobile connectivity. This launch is part of the company's efforts to provide advanced laser cleaning solutions for industrial applications.
- In January 2024, Mitsubishi Corporation launched a proof of concept (PoC) for an electric-vehicle (EV) smart-charging service using EV connected technologies. This initiative aims to verify the commercial viability of Japan's first smart-charging service leveraging EV connected technologies.
- In July 2024, ThunderLaser launched the Aurora Lite, a high-precision laser marking machine designed for optimal business-level applications. This new product aims to provide enhanced precision and efficiency for various marking needs.
- In October 2023, Eastman acquired Dalian Ai-Red Technology, a manufacturer and supplier of paint protection and window film for auto and architectural markets in the Asia Pacific region. This acquisition aims to enhance Eastman's capacity to serve the growing demand for its products and accelerate growth in the automotive and architectural aftermarket films.
Market Concentration and Characteristics
The US fabric cutting machines market exhibits moderate market concentration, with a mix of established global players and regional manufacturers. The market is characterized by a high level of technological innovation, with companies continuously developing advanced cutting solutions to meet the evolving demands of the textile and apparel industries. Key characteristics include a strong focus on automation, precision, and efficiency, driven by the need for high-quality production and cost-effectiveness. The presence of diverse cutting technologies, such as laser, water jet, and knife cutting, caters to various fabric types and applications, from fashion to industrial uses. The market's competitiveness is further heightened by the increasing emphasis on sustainability and eco-friendly practices, influencing both product offerings and manufacturing processes.
Report Coverage
The research report offers an in-depth analysis based on Machine Type, Cutting Method, End Use, Fabric Type and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will witness continuous advancements in cutting technologies, with a focus on enhancing precision and efficiency through AI and machine learning integration.
- There will be a significant shift towards fully automated cutting machines, driven by the need to reduce labor costs and increase production speed.
- The growing trend of mass customization in the textile industry will drive demand for flexible and versatile fabric cutting solutions.
- Manufacturers will increasingly adopt eco-friendly cutting technologies that minimize fabric waste and reduce energy consumption, aligning with sustainability goals.
- The market will see expansion into new regions and industries, including medical textiles and technical fabrics, broadening the application scope of fabric cutting machines.
- The integration of digital tools such as CAD and CAM systems will become more prevalent, improving design accuracy and operational efficiency.
- Ongoing research and development efforts will focus on reducing the costs of advanced fabric cutting machines, making them accessible to a broader range of manufacturers.
- Innovations in material handling technologies will improve the ability of cutting machines to work with a wider variety of fabrics, including composite and smart textiles.
- The adoption of Industry 4.0 principles will lead to smarter manufacturing environments where fabric cutting machines are integrated into interconnected production systems.
- Stricter environmental regulations will drive the adoption of cutting technologies that comply with new standards, pushing the industry towards greener solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Technological Advancements in Cutting Technologies
Rapid innovation in automated, laser, and CAD-integrated fabric cutting machines is enabling higher precision, efficiency, and reduced material waste, making these solutions increasingly attractive for US textile and apparel manufacturers.
Increasing Demand for Mass Customization
The shift towards personalized and small-batch production in fashion and textiles is driving adoption of digital and automated cutting machines, which allow manufacturers to efficiently produce custom designs and adapt quickly to changing consumer preferences.
Emphasis on Sustainable and Efficient Manufacturing Processes
Growing regulatory and consumer focus on sustainability is pushing manufacturers to adopt advanced cutting machines that optimize material usage, minimize waste, and reduce energy consumption, supporting greener production practices.
Growing Investments in the US Textile Industry
Reshoring trends, government incentives, and renewed focus on domestic manufacturing are fueling investments in modernizing textile production, directly boosting demand for advanced fabric cutting machines to enhance productivity and competitiveness.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth rate for the US fabric cutting machines market?
What are the primary drivers of market growth?
Which region dominates the fabric cutting machines market?
What challenges are faced by the fabric cutting machines market?
Who are the key players in the US fabric cutting machines market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Aerospace
- 1.2.2 Automotive
- 1.2.3 Industrial Fabrics
- 1.2.4 Medical
- 1.2.5 Others
- 1.3 By Fabric Type
- 1.3.1 Woven Fabric
- 1.3.2 Non-woven Fabric
- 1.3.3 Knitted Fabric
- 1.4 By Machine Type
- 1.4.1 Manual Machines
- 1.4.2 Semi-automatic Machines
- 1.4.3 Automatic Machines
- 1.5 By Cutting Method
- 1.5.1 Band Knife Cutting
- 1.5.2 Straight Knife Cutting
- 1.5.3 Round Knife Cutting
- 1.5.4 Water Jet Cutting
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 873.20 million → 2032: USD 1,323.41 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 US Fabric Cutting Machines Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 US Fabric Cutting Machines Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 US Fabric Cutting Machines Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 US Fabric Cutting Machines Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 US Fabric Cutting Machines Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 US Fabric Cutting Machines Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 US Fabric Cutting Machines Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 US Fabric Cutting Machines Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 873.20 million → 2032: USD 1,323.41 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 US Fabric Cutting Machines Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Aerospace
- 12.3.7.2 Automotive
- 12.3.7.3 Industrial Fabrics
- 12.3.7.4 Medical
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Fabric Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Woven Fabric
- 12.4.7.2 Non-woven Fabric
- 12.4.7.3 Knitted Fabric
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Machine Type - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Manual Machines
- 12.5.7.2 Semi-automatic Machines
- 12.5.7.3 Automatic Machines
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Cutting Method - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Band Knife Cutting
- 12.6.7.2 Straight Knife Cutting
- 12.6.7.3 Round Knife Cutting
- 12.6.7.4 Water Jet Cutting
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 US Fabric Cutting Machines End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 US Fabric Cutting Machines Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 US Fabric Cutting Machines Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 US Fabric Cutting Machines Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 SHIMA SEIKI
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Eastman
- 18.4 Mazak
- 18.5 Mitsubishi
- 18.6 Zemat Technology
- 18.7 Golden Laser
- 18.8 ThunderLaser
- 18.9 Laser Photonics
- 18.10 Lectra SA
- 18.11 Gerber Technology
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

