
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Fresh Processed Meat Product Market Size 2023 | USD 89,119.17 Million |
| U.S. Fresh Processed Meat Product Market, CAGR | 3.94% |
| U.S. Fresh Processed Meat Product Market Size 2032 | USD 126,221.13 Million |
Market Overview
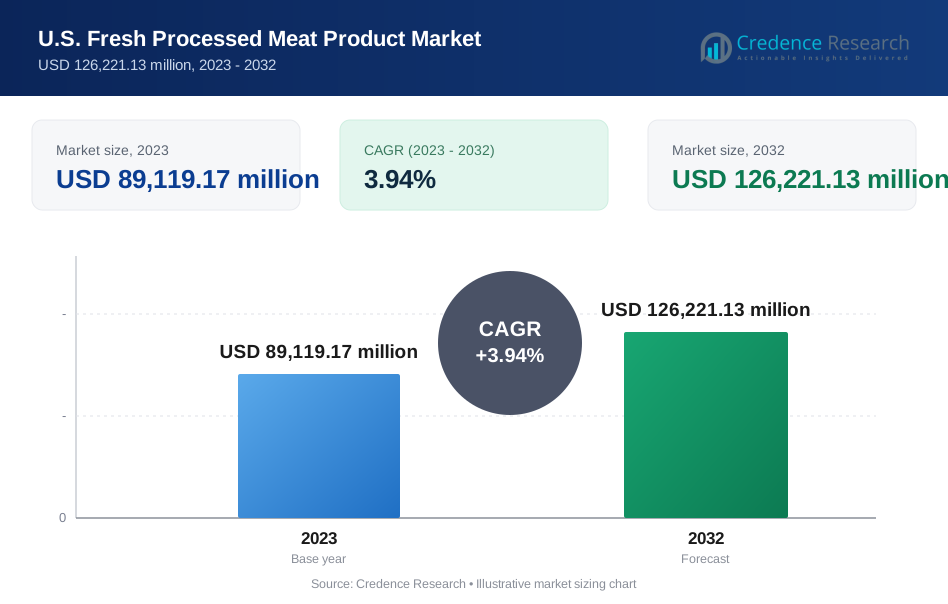
The U.S. Fresh Processed Meat Product Market is projected to grow from USD 89,119.17 million in 2023 to an estimated USD 126,221.13 million by 2032, with a compound annual growth rate (CAGR) of 3.94% from 2024 to 2032. This growth is driven by increasing consumer preference for convenient, high-protein, and longer shelf-life meat products.
Key market drivers and trends include the rising demand for protein-rich diets, particularly among health-conscious consumers, and expanding consumption of ready-to-eat and frozen meat products. Technological advancements in food preservation and packaging are enhancing product safety and extending shelf life. Moreover, the growing popularity of organic and clean-label processed meat is shaping industry dynamics as consumers seek natural, minimally processed options.
Geographically, the market is dominated by key metropolitan regions, with California, Texas, and New York being major consumption hubs due to high urbanization and busy lifestyles. The Midwest remains a strong production region, benefiting from large-scale meat processing facilities. Leading players in the market include Tyson Foods, JBS USA, Cargill, Smithfield Foods, and Hormel Foods, continuously investing in product innovation, sustainable practices, and supply chain optimization to maintain a competitive edge.
Market Insights
- The U.S. Fresh Processed Meat Product Market is projected to grow from USD 89,119.17 million in 2023 to USD 126,221.13 million by 2032, with a CAGR of 3.94% from 2024 to 2032, driven by evolving consumer preferences and technological advancements.
- Increasing demand for ready-to-eat, high-protein, and frozen meat products fuels market growth, as consumers prioritize easy meal solutions amid busy lifestyles.
- The shift towards organic, nitrate-free, and minimally processed meat products is shaping market dynamics, with consumers seeking healthier and transparent ingredient options.
- Stringent USDA food safety regulations, fluctuating raw material costs, and labor shortages create operational challenges for meat processors, impacting production efficiency.
- Technologies such as Modified Atmosphere Packaging (MAP) and High-Pressure Processing (HPP) are extending shelf life, improving food safety, and reducing waste.
- The Midwest dominates production, while California, Texas, and New York lead in consumption, driven by urbanization and strong foodservice demand.
- Major players like Tyson Foods, JBS USA, Cargill, and Smithfield Foods continue to expand their product offerings, invest in sustainability, and optimize supply chain operations to maintain market leadership.
Market Drivers
Rising Consumer Demand for Convenience and Ready-to-Eat Products
The growing preference for convenient and ready-to-eat (RTE) meat products significantly drives the U.S. fresh processed meat product market. Consumers, especially in urban areas, seek quick meal solutions due to increasingly hectic lifestyles, demanding products that require minimal preparation. The expansion of supermarkets, hypermarkets, and online grocery platforms has made these products more accessible, further accelerating their consumption. Advancements in food preservation technologies like vacuum packaging and modified atmosphere packaging (MAP) have enhanced the shelf life of fresh processed meat, making them more appealing to consumers who prioritize convenience and freshness. The rise of dual-income and single-person households has also contributed to demand for microwaveable, pre-cooked, and marinated options. Foodservice providers, including fast-food chains and meal delivery services, are also fueling the demand for bulk fresh processed meats. For instance, the expansion of supermarkets and online grocery platforms has significantly increased the accessibility of convenient meat products. This is evident as major retailers like Walmart generate a substantial portion of their food sales from dedicated shelf space for ready-to-eat products, highlighting the growing importance of this category in mainstream retail.
Growing Health Awareness and Demand for Protein-Rich Diets
Health-conscious consumers are increasingly incorporating high-protein, low-fat, and functional processed meat options into their diets, driving innovation in the fresh processed meat segment. The shift toward high-protein diets, influenced by fitness trends and wellness awareness, has led manufacturers to introduce leaner meat options, nitrate-free products, and organic fresh processed meats. As ketogenic, paleo, and high-protein diets gain popularity, fresh processed meats such as lean turkey slices, grass-fed beef patties, and uncured bacon are becoming staples in many households. Clean-label and organic trends have encouraged industry players to reduce artificial preservatives, sodium, and chemical additives in their products, catering to a segment of consumers concerned about processed food additives and health risks. Companies are leveraging natural curing methods to maintain food safety while meeting the demand for healthier choices. Fortified processed meat options enriched with omega-3 fatty acids, probiotics, and vitamins are also gaining traction. For instance, the growing interest in plant-based protein sources and expanding awareness of protein’s importance for health and wellness are fueling the demand for protein-rich foods. This trend is supported by data from Innova Market Insights, which shows consumers continue to prioritize protein in their diets.
Expansion of Retail and E-Commerce Channels
The widespread availability of fresh processed meat products across retail stores, supermarkets, club stores, and online grocery platforms is a crucial market driver. Traditional brick-and-mortar retailers like Walmart, Kroger, and Costco continue to dominate the market by offering bulk purchase discounts, exclusive brands, and extended shelf-life products. E-commerce and direct-to-consumer (DTC) platforms such as Amazon Fresh, Instacart, and ButcherBox have revolutionized the way consumers shop for fresh processed meat. The rise of subscription-based meat delivery services has further fueled market expansion, providing consumers with customized, pre-packaged fresh processed meat selections delivered directly to their doorsteps. This shift in purchasing behavior is largely driven by younger consumers, particularly Millennials and Gen Z, who prefer online shopping convenience and doorstep delivery. Advancements in cold chain logistics and temperature-controlled packaging have strengthened consumer trust in online fresh meat purchases. Retailers are also capitalizing on private-label processed meat offerings, and supermarkets are investing in premium and organic fresh processed meat sections. For instance, the rise of subscription-based meat delivery services like ButcherBox has further fueled market expansion by providing consumers with customized, pre-packaged fresh processed meat selections delivered directly to their doorsteps. This shift is largely driven by younger consumers who prefer the convenience of online shopping and doorstep delivery.
Technological Innovations in Processing and Preservation
Technological advancements in meat processing, food safety, and preservation techniques have played a pivotal role in enhancing product quality, extending shelf life, and ensuring compliance with stringent regulatory standards. High-pressure processing (HPP), modified atmosphere packaging (MAP), and vacuum sealing technologies have revolutionized the fresh processed meat industry by reducing the reliance on synthetic preservatives while maintaining food safety. Smart packaging solutions embedded with time-temperature indicators and freshness sensors are gaining traction, helping both retailers and consumers track the quality of fresh processed meat in real time. Companies are also investing in automated processing and precision-cutting technologies, enabling higher efficiency, reduced wastage, and improved meat texture and consistency. Sustainability initiatives have led to the development of eco-friendly meat processing solutions. Regulatory bodies such as the USDA and FSIS are imposing stricter guidelines, compelling manufacturers to adopt advanced food safety protocols. For instance, advancements in food preservation technologies such as vacuum packaging and modified atmosphere packaging (MAP) have enhanced the shelf life of fresh processed meat, making them more appealing to consumers who prioritize both convenience and freshness. Additionally, smart packaging solutions embedded with time-temperature indicators and freshness sensors are helping both retailers and consumers track the quality of fresh processed meat in real time.
Market Trends
Rising Demand for Clean-Label and Organic Processed Meats
Consumers are increasingly prioritizing clean-label, organic, and minimally processed meat products, moving away from conventional options with artificial additives and high sodium. This shift is fueled by growing health awareness and concerns about synthetic preservatives like nitrates and nitrites. Leading market players are responding by launching nitrate-free, antibiotic-free, and hormone-free fresh processed meat products to cater to health-conscious consumers. Brands are also incorporating natural curing agents like celery powder and sea salt to maintain freshness. Grass-fed and free-range options are gaining traction as consumers seek higher nutritional value and ethical sourcing. The organic segment benefits from increasing consumer trust in USDA-certified organic labels. For instance, supermarkets have expanded their organic meat sections to include a variety of USDA-certified organic deli meats, pre-seasoned poultry, and grass-fed beef patties, reflecting the growing consumer preference for natural and ethically sourced processed meats. Premium brands highlight sustainability and farm-to-table transparency, further reinforcing consumer preferences for natural, ethically sourced processed meats.
Expansion of Plant-Based and Hybrid Meat Alternatives
The growing acceptance of plant-based and flexitarian diets is fueling demand for plant-based and hybrid meat alternatives in the fresh processed meat segment. While traditional meat products remain dominant, an increasing number of consumers, particularly Millennials and Gen Z, are seeking blended meat options that combine animal protein with plant ingredients. This reduces environmental impact while maintaining familiar taste and texture. Companies are developing hybrid processed meat products that integrate ingredients like mushroom, soy, pea protein, and lentils with conventional meat to enhance fiber content, reduce fat levels, and minimize carbon footprints. For example, companies are developing hybrid processed meat products that integrate mushroom, soy, pea protein, and lentils with conventional meat, enhancing fiber content and reducing fat levels. This innovation is gaining traction among health-conscious consumers seeking meat options with improved nutritional profiles. Fast-food chains and QSRs are also incorporating blended patties, plant-based sausages, and hybrid chicken products into their menus. Advances in plant-based meat technology, including cell-based and lab-grown meat, are expected to further impact the market.
Innovations in Packaging and Extended Shelf Life Solutions
The fresh processed meat industry is witnessing significant advancements in packaging and preservation techniques, driven by increasing demand for longer shelf life, reduced food waste, and enhanced product safety. Traditional plastic packaging is being replaced by biodegradable, recyclable, and vacuum-sealed alternatives, aligning with consumer demand for eco-friendly packaging solutions. Technologies such as Modified Atmosphere Packaging (MAP) and High-Pressure Processing (HPP) are gaining prominence, as they allow manufacturers to extend product shelf life without the need for artificial preservatives. For instance, Modified Atmosphere Packaging (MAP) involves adjusting the gas composition within the packaging to slow bacterial growth and oxidation, ensuring freshness for an extended period. This technology allows manufacturers to extend product shelf life without the need for artificial preservatives. Smart packaging solutions, including time-temperature indicators (TTI) and freshness sensors, are also being integrated into processed meat packaging to enhance transparency and improve food safety. Retailers and online grocery platforms are focusing on pre-portioned and single-serving packaging, catering to the rising number of single-person households and busy professionals.
Growth of E-Commerce and Direct-to-Consumer (DTC) Meat Delivery Services
The U.S. fresh processed meat product market has experienced a major shift toward e-commerce and direct-to-consumer (DTC) sales channels, driven by changing consumer shopping habits, digitalization, and subscription-based meal solutions. The expansion of online grocery platforms such as Amazon Fresh, Instacart, and Walmart+ has made fresh processed meat products more accessible to a broader audience, particularly in urban areas where convenience is a priority. Subscription-based meat delivery services have also gained popularity, offering customized fresh processed meat boxes that cater to specific dietary needs, including organic, grass-fed, and high-protein selections. For example, subscription-based meat delivery services like ButcherBox and Crowd Cow offer customized fresh processed meat boxes that cater to specific dietary needs, including organic, grass-fed, and high-protein selections. These services leverage advanced cold-chain logistics to ensure meat freshness and prevent spoilage. E-commerce platforms are leveraging advanced cold-chain logistics and AI-driven inventory management to ensure meat freshness, prevent spoilage, and streamline last-mile delivery operations. Digital innovations such as QR code scanning and blockchain-based supply chain traceability are helping consumers verify the origin, quality, and sustainability credentials of their fresh processed meat purchases.
Market Challenges
Regulatory Compliance and Food Safety Concerns
The U.S. fresh processed meat product market operates under strict regulatory frameworks imposed by the U.S. Department of Agriculture (USDA) and the Food Safety and Inspection Service (FSIS). Compliance with food safety regulations is a significant challenge for manufacturers, as they must adhere to rigorous standards for processing, labeling, and contamination prevention. The industry faces increasing scrutiny regarding the use of preservatives, sodium content, and artificial additives, prompting companies to reformulate products while maintaining flavor, texture, and shelf stability. Moreover, foodborne illnesses and contamination risks pose significant concerns, necessitating continuous investment in advanced food safety protocols, traceability systems, and high-pressure processing (HPP) technologies. The risk of recalls due to contamination from E. coli, Salmonella, or Listeria can lead to severe financial losses, reputational damage, and declining consumer trust. Additionally, meeting evolving organic, antibiotic-free, and clean-label product standards increases operational complexity, requiring frequent modifications in processing techniques and ingredient sourcing. These challenges demand continuous innovation in food safety technology and stringent quality control measures to ensure compliance and consumer safety.
Rising Costs and Supply Chain Disruptions
Fluctuating raw material costs, labor shortages, and supply chain disruptions are key obstacles for the fresh processed meat market. The cost of livestock feed, transportation, and energy has surged in recent years, leading to higher production expenses that manufacturers struggle to offset without significantly increasing consumer prices. Additionally, labor shortages in meat processing plants have exacerbated operational inefficiencies, compelling companies to invest in automation and workforce training programs to maintain productivity. Supply chain vulnerabilities, including disruptions in cold storage logistics, transportation bottlenecks, and packaging material shortages, further challenge market stability. Rising concerns over sustainability and carbon emissions in meat production also push companies to adopt eco-friendly practices, which require significant capital investment. Balancing cost efficiency, sustainability, and product affordability remains a persistent challenge for industry players navigating an increasingly complex market landscape.
Market Opportunities
Expansion of Health-Focused and Clean-Label Products
The growing consumer preference for clean-label, organic, and health-conscious processed meat options presents a significant opportunity for market expansion. Consumers are actively seeking nitrate-free, antibiotic-free, and minimally processed meat products, driving demand for premium and organic offerings. Manufacturers can capitalize on this trend by innovating with natural preservatives, reducing sodium content, and introducing functional meat products enriched with omega-3s, probiotics, and plant-based ingredients. The rise of high-protein diets, including keto and paleo, further supports the potential for leaner, healthier processed meat alternatives. As retailers dedicate more shelf space to organic and specialty processed meats, brands that invest in transparent labeling and sustainable sourcing will gain a competitive edge.
Digitalization and E-Commerce Growth in Meat Retailing
The expansion of online grocery platforms, direct-to-consumer (DTC) meat delivery services, and subscription-based meal solutions is transforming the way consumers purchase fresh processed meat. Companies can leverage this shift by optimizing their digital presence, expanding partnerships with e-commerce retailers, and investing in cold-chain logistics to ensure product freshness during transit. The rise of AI-driven inventory management, blockchain-based traceability, and personalized meat subscription boxes allows brands to differentiate themselves in a highly competitive market. As consumers increasingly prefer the convenience of online shopping and home delivery, companies that enhance their e-commerce capabilities, digital marketing strategies, and sustainable packaging solutions will capture new market segments and drive long-term growth.
Market Segmentation Analysis
By Product Type:
The market is divided into four main product categories: Fresh Meat, Poultry, Seafood, and Others. Among these, Fresh Meat holds the largest share due to its widespread use in daily meals and the increasing demand for protein-rich diets. Poultry products, including chicken, turkey, and duck, are also highly popular due to their affordability and versatility. Seafood, though a smaller segment, is growing steadily as consumers seek healthier alternatives to red meat. The Others category includes specialty meats such as game meat and processed products made from blends of different animal proteins.
By Application:
The market is further segmented based on application into Home Cooking, Foodservice, Ready-to-Eat Meals, Pet Food, and Others. Home Cooking remains a dominant segment as more consumers are cooking at home, often looking for fresh, high-quality meats. Foodservice, encompassing restaurants and catering services, is another significant sector, driven by the demand for processed meat in various cuisines. The Ready-to-Eat Meals segment is expanding rapidly due to increasing consumer preference for convenience foods. Pet Food is a growing application segment as pet owners look for high-protein, nutritious food options for their pets.
Segments
Based on Product Type
- Fresh Meat
- Poultry
- Seafood
- Others
Based on Application
- Home Cooking
- Foodservice
- Ready-to-Eat Meals
- Pet Food
- Others
Based on Packaging type
- Modified Atmosphere Packaging
- Vacuum Packaging
- Tray Packaging
- Others
Based on Certification
- Organic
- Halal
- Kosher
- BRC
- Others
Based on Distribution channel
- Supermarkets/Hypermarkets
- Convenience Stores
- Online Retailers
- Butcher Shops
- Others
Based on Region
- Northeast
- Midwest
- South
- West
Regional Analysis
Midwest (35.2%)
The Midwest holds the largest market share, accounting for 35.2% of the U.S. fresh processed meat product market. This dominance is driven by the presence of large-scale meat processing facilities, livestock farming, and well-established supply chains. States such as Iowa, Nebraska, and Illinois are key contributors, benefiting from high livestock production and strong agricultural infrastructure. The region is home to major meat processing companies and accounts for a significant portion of beef and pork production. Additionally, the proximity of production facilities to retail and foodservice distribution networks reduces supply chain costs and enhances efficiency, further strengthening the Midwest’s market position.
South (31.7%)
The South represents 31.7% of the market, making it the second-largest region in terms of market share. This region exhibits strong consumer demand for fresh processed meat, driven by a rich barbecue culture, a preference for high-protein diets, and an expanding foodservice industry. Texas, Florida, and Georgia lead in consumption, fueled by urbanization, increasing disposable income, and a strong presence of quick-service restaurants (QSRs). Additionally, poultry-based processed meats, such as marinated chicken and turkey cuts, are particularly popular in the Southern states. The region also benefits from a diverse retail landscape, with both large supermarkets and independent butcher shops catering to varying consumer preferences.
Key players
- Tyson Foods, Inc.
- Hormel Foods Corporation
- Smithfield Foods
- Maple Leaf Foods
- ConAgra Brands
- Oscar Mayer (Kraft Heinz Company)
- Pilgrim's Pride Corporation
- Perdue Farms (Perdue Foods)
- Johnsonville
- Farmland Foods
- Westfleisch SCE
- JBS USA
- Cargill
Competitive Analysis
The U.S. fresh processed meat product market is highly competitive, with key players focusing on product innovation, strategic acquisitions, and sustainability initiatives to strengthen their market position. Tyson Foods, JBS USA, and Cargill dominate the industry due to large-scale production, extensive distribution networks, and diversified product portfolios. Companies like Hormel Foods and Smithfield Foods leverage brand recognition and premium product offerings to maintain a strong foothold. Innovation in clean-label, organic, and plant-based processed meats is a key competitive strategy, with brands such as Maple Leaf Foods and Perdue Farms investing in sustainable and antibiotic-free meat products. Meanwhile, Oscar Mayer and Johnsonville focus on convenience-driven, ready-to-eat meat solutions to cater to evolving consumer preferences. Retail and e-commerce expansion remains a crucial growth avenue, with companies enhancing their direct-to-consumer sales channels and digital marketing strategies to sustain long-term market growth.
Recent Developments
- In February 2025, Tyson Foods raised its annual sales forecast for fiscal 2025, expecting sales to be flat to up 1%, driven by strong demand for beef and chicken products. The company also reported year-over-year growth in both revenue and profitability during the first quarter of 2025.
- In January 2025, Hormel Foods announced the retirement of its CEO, James Snee, after 36 years with the company. This leadership change comes as Hormel prepares for future growth.
Market Concentration and Characteristics
The U.S. Fresh Processed Meat Product Market is characterized by high market concentration, with a few dominant players such as Tyson Foods, JBS USA, Cargill, and Smithfield Foods controlling a significant share of the industry. These companies benefit from large-scale production, extensive supply chain networks, and strong brand portfolios, allowing them to maintain competitive pricing and distribution advantages. The market is driven by technological advancements in processing, increasing demand for convenience foods, and shifting consumer preferences toward clean-label and organic meat products. Additionally, regulatory compliance, sustainability initiatives, and innovation in packaging and preservation technologies play a crucial role in shaping market dynamics. While major corporations dominate national and international distribution, regional and niche players compete by offering specialized, locally sourced, or premium meat products, catering to the growing demand for organic, halal, and antibiotic-free options.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, Packaging type, Certification, Distribution channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Consumers will continue prioritizing nitrate-free, antibiotic-free, and minimally processed meat products, driving innovation in natural preservation and clean-label formulations.
- The market will witness increased production of organic and grass-fed processed meats, as brands focus on sustainability, ethical sourcing, and environmentally friendly packaging.
- Companies will invest in high-pressure processing (HPP), smart packaging, and cold-chain logistics to enhance shelf life, food safety, and product freshness.
- The integration of plant-based ingredients with traditional meat products will gain traction, catering to the rising flexitarian and health-conscious consumer base.
- Online grocery platforms and subscription-based meat delivery services will expand, offering consumers personalized, high-quality fresh processed meat options.
- Consumers will seek protein-enriched, omega-3-fortified, and probiotic-infused processed meats, aligning with fitness and wellness trends.
- Stricter USDA and FDA regulations will drive investment in advanced traceability systems, blockchain-based supply chain management, and AI-driven quality control.
- Brands will focus on gourmet, marinated, and internationally flavored processed meats, appealing to diverse taste preferences and premium-segment consumers.
- Companies will increasingly implement carbon footprint reduction strategies, water-efficient processing, and biodegradable packaging to meet sustainability goals.
- Major meat processors will expand their portfolios, while supermarket private labels will introduce competitive, high-quality processed meat options, reshaping market dynamics.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the U.S. Fresh Processed Meat Product Market in 2023 and 2032?
What factors are driving the growth of the fresh processed meat market in the U.S.?
Which regions in the U.S. have the highest consumption of fresh processed meat?
How are technological advancements influencing the fresh processed meat market?
Who are the key players in the U.S. Fresh Processed Meat Product Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 U.S. Fresh Processed Meat Product Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 U.S. Fresh Processed Meat Product Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 89,119.17 million → 2032: USD 126,221.13 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 U.S. Fresh Processed Meat Product Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. U.S. Fresh Processed Meat Product Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 U.S. Fresh Processed Meat Product Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 U.S. Fresh Processed Meat Product Drivers
- 3.3 U.S. Fresh Processed Meat Product Restraints & Challenges
- 3.4 U.S. Fresh Processed Meat Product Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 U.S. Fresh Processed Meat Product Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 U.S. Fresh Processed Meat Product Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, U.S. Fresh Processed Meat Product category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 U.S. Fresh Processed Meat Product Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. U.S. Fresh Processed Meat Product Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2023)
- 5.1.2 Export Volume by Destination Country (2023) (Where Applicable)
- 5.1.3 Import Value by Source Country (2023)
- 5.1.4 Import Volume by Source Country (2023) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to U.S. Fresh Processed Meat Product in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 U.S. Fresh Processed Meat Product Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 U.S. Fresh Processed Meat Product Share Analysis – 2023
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 U.S. Fresh Processed Meat Product Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in U.S. Fresh Processed Meat Product (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in U.S. Fresh Processed Meat Product
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. U.S. Fresh Processed Meat Product – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. U.S. Fresh Processed Meat Product – Priority Domestic Market 1
Chapter 10. U.S. Fresh Processed Meat Product – Priority Domestic Market 2
Chapter 11. U.S. Fresh Processed Meat Product – Priority Domestic Market 3
Chapter 12. U.S. Fresh Processed Meat Product – Priority Domestic Market 4
Chapter 13. U.S. Fresh Processed Meat Product Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
