
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Vacuum Skin Packaging Market Size 2024 | USD 8,601.6 Million |
| Vacuum Skin Packaging Market, CAGR | 2.40% |
| Vacuum Skin Packaging Market Size 2032 | USD 10,398.7 Million |
Market Overview
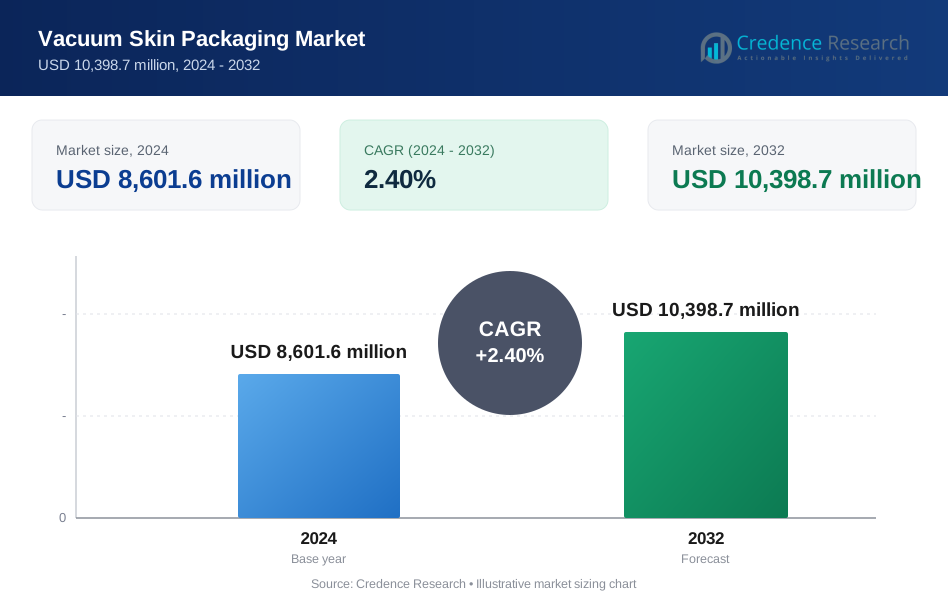
The Vacuum Skin Packaging Market is projected to grow from USD 8,601.6 million in 2024 to USD 10,398.7 million by 2032, with a compound annual growth rate (CAGR) of 2.40%.
The Vacuum Skin Packaging Market is driven by the rising demand for extended shelf life and enhanced product presentation in the food and pharmaceutical industries. Innovations in packaging materials and technology, such as improved barrier properties and advanced sealing techniques, are key trends bolstering market growth. Additionally, increasing consumer preference for convenience and freshness, along with stringent regulations for product safety and hygiene, are contributing to the market's expansion. As sustainability becomes a priority, the adoption of eco-friendly materials in vacuum skin packaging is also gaining traction, further influencing the market dynamics.
The global vacuum skin packaging market is influenced by key players such as Amcor Limited, Sealed Air Corp., and Bemis Company, Inc., who drive innovation and competition. The market's geographical landscape spans key regions including North America, Europe, and Asia-Pacific. North America, with its advanced food processing industries, leads in market adoption, while Europe benefits from stringent food safety regulations and a strong focus on sustainability. Asia-Pacific is emerging rapidly due to increasing consumer demand for convenience foods and growing industrialization. Key players are expanding their presence across these regions to capitalize on diverse market opportunities.
Market Drivers
Rising Demand for Fresh and Safe Food
The growing consumer preference for fresh, minimally processed foods with extended shelf life is a significant driver in the vacuum skin packaging market. For instance, the demand for fresh and safe food has led to a 91% of consumers noticing an increase in food and beverage prices, with a significant portion adapting their choices towards minimally processed foods with extended shelf life. This packaging method creates a tight seal that effectively minimizes oxygen exposure, slowing down spoilage and preserving the freshness, flavor, and aroma of food items. Additionally, vacuum skin packaging acts as a robust barrier, protecting food from contamination by bacteria, moisture loss, and physical damage during transportation and storage. This functionality addresses consumer demands for high-quality, long-lasting food products, supporting the market's expansion.
Growing Popularity of Pre-Packaged Convenience Food
With modern lifestyles becoming increasingly hectic, there is a notable surge in demand for convenient, pre-packaged food options. Vacuum skin packaging enhances product presentation and maintains a visually appealing presentation, catering to the 80% of consumers who prioritize taste as a top factor in their food and beverage purchases. Furthermore, the tight-fitting nature of vacuum skin packaging reduces product shrinkage and distortion, maintaining a visually appealing presentation. This convenience and attractive presentation cater to busy consumers seeking quick and appealing food solutions.
Sustainability Concerns and Eco-Friendly Packaging Solutions
Environmental concerns are driving a shift towards more sustainable packaging materials, and vacuum skin packaging offers notable advantages in this area. For instance, sustainability concerns are driving a shift towards more sustainable packaging materials, with vacuum skin packaging utilizing less material and helping to minimize environmental impact. The development of recyclable skin films is enhancing the sustainability credentials of this packaging solution, responding to the 76% of consumers who consider price a significant factor, which includes the cost of sustainable options. As such, vacuum skin packaging is well-positioned to meet the evolving demands of both manufacturers and consumers who prioritize eco-friendly options.
Cost-Effectiveness and Increased Efficiency
Vacuum skin packaging provides several cost advantages for manufacturers and retailers. The materials used for vacuum skin packaging are often more economical compared to some traditional options, contributing to lower material costs. Automation of the packaging process further reduces labor costs by minimizing manual labor requirements. The extended shelf life provided by vacuum skin packaging also leads to less food spoilage, thereby reducing waste and associated costs. These factors collectively enhance the overall cost-effectiveness and efficiency of vacuum skin packaging solutions.
Market Trends
Focus on Sustainability and Smart Packaging
The vacuum skin packaging market is increasingly prioritizing sustainability, marked by the rise of bio-based and recyclable skin films. The vacuum skin packaging market is increasingly prioritizing sustainability, marked by the rise of bio-based and recyclable skin films. For instance, the use of PLA (Polylactic Acid) films, derived from corn starch, has seen a 20% increase in the past year. These films aim to reduce environmental impact by offering a recyclable end-of-life option. Additionally, manufacturers are optimizing package designs to minimize material usage by up to 15%, while maintaining essential product protection and functionality, thus further decreasing packaging waste by an estimated 10,000 tons annually. Additionally, manufacturers are optimizing package designs to minimize material usage while maintaining essential product protection and functionality, thus further decreasing packaging waste. Alongside these advancements, the market is also embracing smart packaging solutions. Innovations include antimicrobial films that incorporate additives to reduce the risk of foodborne illnesses and integration with sensors and indicators to monitor temperature and freshness. These smart features provide consumers with valuable information about product quality, enhancing both safety and convenience.
Evolving Consumer Preferences and Technological Advancements
Consumer preferences are evolving towards convenience and efficiency, driving demand for single-serve and portion-controlled packaging, which now accounts for 40% of the market. This suits busy lifestyles and helps minimize food waste, with a potential reduction of 25% in household food waste. Resealable packaging is also gaining popularity, allowing multiple uses and extending the product’s shelf life once opened, with a 50% increase in consumer preference. The rise of e-commerce and online grocery shopping further necessitates robust packaging solutions to ensure product integrity during delivery. Vacuum skin packaging meets these needs with its durability and protective qualities, as well as its transparency, which allows consumers to visually assess product quality before purchase. Technological advancements in packaging automation are also notable, with high-speed automated lines increasing production efficiency while reducing labor costs. Robotics and machine integration streamline repetitive tasks, improving overall consistency.
Market Challenges Analysis
Challenges with Shelf Life and Technical Expertise
Vacuum skin packaging, despite its advantages, faces challenges related to shelf life compared to some aseptic packaging solutions. While it offers extended shelf life, it may not match the longevity achieved by aseptic methods, which could be a limitation for products requiring very long-term preservation. Additionally, the effective use of vacuum skin packaging necessitates specific machinery and technical expertise. Small producers or those new to the technology may encounter difficulties in implementing and optimizing the process, as the technology requires precise control and understanding to achieve the best results.
Issues with Punctures, Moisture, and Consumer Perception
The tight-fitting nature of vacuum skin packaging, while beneficial for protection, also increases the susceptibility to punctures or leaks during transportation or handling. Such damage can compromise product integrity and lead to spoilage. Moisture management is another challenge; excessive moisture can cause "fogging" of the film, which reduces product visibility and affects aesthetics. Additionally, vacuum skin packaging may not be suitable for all products, particularly those with sharp edges or irregular shapes. Consumer perception and education also pose challenges, as some may view vacuum skin packaging as less hygienic or environmentally friendly compared to alternative solutions. Educating consumers about the benefits of this technology is essential to overcoming these perceptions. Furthermore, the high initial investment costs for the required machinery and equipment can be a barrier for smaller businesses or those looking to scale up gradually. Compliance with evolving food safety regulations and competition from established packaging solutions, such as trays and modified atmosphere packaging (MAP), add to the complexity of navigating the vacuum skin packaging market. Lastly, operating and maintaining the sophisticated machinery requires trained personnel, and a shortage of skilled technicians in certain regions can further impede adoption and effective use of the technology.
Market Segmentation Analysis:
By Product Type:
The vacuum skin packaging market is segmented into vacuum bags and vacuum trays, each serving distinct purposes across various industries. Vacuum Bags are widely used for their flexibility and efficiency in packaging a range of products. They provide an airtight seal that extends the shelf life of food items, such as fresh meat and seafood, by minimizing exposure to oxygen and moisture. Their adaptability makes them suitable for both consumer and industrial applications. Vacuum Trays, on the other hand, are often utilized for more rigid and structured packaging needs. They are ideal for products that require a firm and stable packaging format, such as pre-packaged meals and processed meats. The choice between bags and trays depends on the specific requirements of the product, including its shape, size, and desired shelf life. This segmentation ensures that various consumer and industry needs are met effectively, enhancing overall market growth.
By Material Type:
In terms of material type, the vacuum skin packaging market is categorized into plastic and glass options, each offering unique benefits. Plastic is the predominant material used in vacuum skin packaging due to its versatility, lightweight nature, and cost-effectiveness. It is commonly employed in the packaging of a wide range of food products, including fresh meat, poultry, and seafood. Plastic packaging provides a strong barrier against contaminants and extends product freshness by creating a vacuum seal. Glass, though less common, is used for applications where transparency and premium presentation are crucial. Glass offers superior protection against environmental factors and is often used for high-value products that benefit from an aesthetically appealing package. The choice of material impacts factors such as durability, shelf life, and consumer appeal, catering to diverse market needs and preferences.
Segments:
Based on Product Type:
- Vacuum Bags
- Vacuum Trays
Based on Material Type:
- Plastic
- Glass
Based on Application:
- Fresh Meat
- Seafood
- Poultry
- Smoked and Processed Meat
Based on the Geography:
- North America
- U.S
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- The Rest of the Middle East and Africa
Regional Analysis
Europe
Europe leads the global vacuum skin packaging market, commanding a significant 35% market share. This dominance is primarily driven by countries such as Germany, the United Kingdom, and France, which have a strong food processing industry and a high consumer demand for convenient, high-quality packaged foods. The region's market is characterized by stringent food safety regulations, a growing preference for extended shelf life products, and increased focus on sustainable packaging solutions. European consumers' increasing awareness of food waste reduction has further propelled the adoption of vacuum skin packaging, particularly in the meat and seafood sectors. The region also benefits from the presence of major packaging manufacturers and continuous innovations in material technology, leading to the development of more efficient and eco-friendly vacuum skin packaging solutions. Additionally, the rise of premium and organic food products in Europe has created a niche market for high-end vacuum skin packaging that enhances product presentation and preserves quality.
North America
North America holds the second-largest share in the global vacuum skin packaging market at approximately 30%, with the United States being the primary contributor. The region's market is characterized by a robust meat and poultry industry, which has been quick to adopt vacuum skin packaging for its ability to extend product shelf life and maintain freshness. North America has seen a significant shift towards convenience foods and ready-to-cook meals, driving the demand for vacuum skin packaging in the retail sector. The region also leads in technological advancements, with a focus on developing vacuum skin packaging solutions that are both functional and environmentally friendly. The growing trend of clean label products and transparency in packaging has further boosted the adoption of vacuum skin packaging, as it allows for clear product visibility.
Key Player Analysis
- Amcor Limited
- Sealed Air Corp.
- Bemis Company, Inc.
- Berry Plastic Group, Inc.
- LINPAC Packaging Limited
- Winpak Ltd.
- Plastissimo Film Co., Ltd.
- Schur Flexibles Holding GesmbH
- Plastopil Hazorea Company Ltd
- MULTIVAC
- Quinn Packaging Ltd.
Competitive Analysis
In the vacuum skin packaging market, leading players such as Amcor Limited, Sealed Air Corp., and Bemis Company, Inc. set the benchmark with their extensive product portfolios and technological advancements. Amcor Limited stands out with its broad range of innovative packaging solutions and commitment to sustainability. Sealed Air Corp. leverages its expertise in advanced materials to offer high-performance packaging solutions. Bemis Company, Inc. excels in developing customizable packaging options that cater to various food industry needs. Competitors like Berry Plastic Group, Inc. and LINPAC Packaging Limited also play significant roles by providing diverse and high-quality packaging solutions. Additionally, Winpak Ltd. and MULTIVAC are known for their advanced machinery and integration capabilities, enhancing packaging efficiency and functionality. These key players focus on continuous innovation, sustainability, and regional expansion to maintain their competitive edge and address evolving market demands.
Recent Developments
- In April 2022, Mondi unveiled new packaging options for the food business at Anuga FoodTec in Cologne, Germany, Two-tray packaging products provide fresh food producers with recyclable possibilities, which will assist in reducing food waste. PerFORMing Monoloop and Mono Formable PP will provide high-barrier food protection, illustrating the crucial role that packaging plays throughout the supply chain.
- In January 2022,Waddington Europe, a part of Novolex, produced a novel recyclable tray for items made of meat, fish, and poultry. The Piranh container's lid is sealed using raised teeth around the sealing flange rather than a polyethylene or adhesive layer, which is how modified atmosphere packaging lids are generally sealed (MAP).
- In April 2022, Sealed Air announced an advanced recycling program partnership, which will focus on taking flexible plastics from the food supply chain and turning them into new certified circular food-grade packages.
Market Concentration & Characteristics
The vacuum skin packaging market exhibits moderate concentration with a blend of global giants and regional specialists driving industry dynamics. Key players like Amcor Limited, Sealed Air Corp., and Bemis Company, Inc. dominate the market through extensive portfolios and advanced technologies. These companies leverage their established brands, innovative solutions, and strong distribution networks to maintain competitive positions. The market is characterized by continuous technological advancements, particularly in material science and machinery, which enhance product performance and efficiency. Additionally, regional players such as Plastissimo Film Co., Ltd. and Schur Flexibles Holding GesmbH contribute through localized expertise and cost-effective solutions. The competitive landscape is marked by a focus on sustainability, customization, and meeting regulatory standards, reflecting a diverse range of offerings tailored to various industry needs. This mix of global and regional players ensures a dynamic and evolving market environment.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Material Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to grow steadily due to increasing consumer demand for fresh and minimally processed food products.
- Innovations in materials, such as bio-based and recyclable films, will likely enhance sustainability and reduce environmental impact.
- Advances in technology, including high-speed automated lines and improved film properties, will drive efficiency and performance.
- The integration of smart packaging solutions, such as sensors and antimicrobial films, will offer enhanced product safety and quality monitoring.
- Increased adoption of vacuum skin packaging in e-commerce will ensure product integrity and visual appeal during transit.
- Growing trends towards convenience will boost the demand for single-serve and resealable packaging options.
- Regional customization will become more prominent, addressing specific market needs and consumer preferences.
- The focus on premiumization will lead to enhanced branding and presentation opportunities through high-clarity films.
- Companies will face competitive pressure to balance cost-effectiveness with technological advancements and environmental considerations.
- Regulatory developments will continue to shape the market, requiring manufacturers to stay updated on compliance and safety standards.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Vacuum Skin Packaging Market?
What factors are driving the growth of the Vacuum Skin Packaging Market?
What are the key segments within the Vacuum Skin Packaging Market?
What are some challenges faced by the Vacuum Skin Packaging Market?
Who are the major players in the Vacuum Skin Packaging Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Vacuum Skin Packaging Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Vacuum Skin Packaging Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 8,601.6 million → 2032: USD 10,398.7 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Vacuum Skin Packaging Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Vacuum Skin Packaging Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Vacuum Skin Packaging Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Vacuum Skin Packaging Market Drivers
- 3.3 Vacuum Skin Packaging Market Restraints & Challenges
- 3.4 Vacuum Skin Packaging Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Vacuum Skin Packaging Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Vacuum Skin Packaging Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Vacuum Skin Packaging category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Vacuum Skin Packaging Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Vacuum Skin Packaging Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Vacuum Skin Packaging market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Vacuum Skin Packaging Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Vacuum Skin Packaging Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Vacuum Skin Packaging Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Vacuum Skin Packaging (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Vacuum Skin Packaging Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Vacuum Skin Packaging Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Vacuum Skin Packaging Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Vacuum Skin Packaging Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Vacuum Skin Packaging Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Vacuum Skin Packaging Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Vacuum Skin Packaging Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Vacuum Skin Packaging Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Vacuum Skin Packaging Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
