
Market Overview:
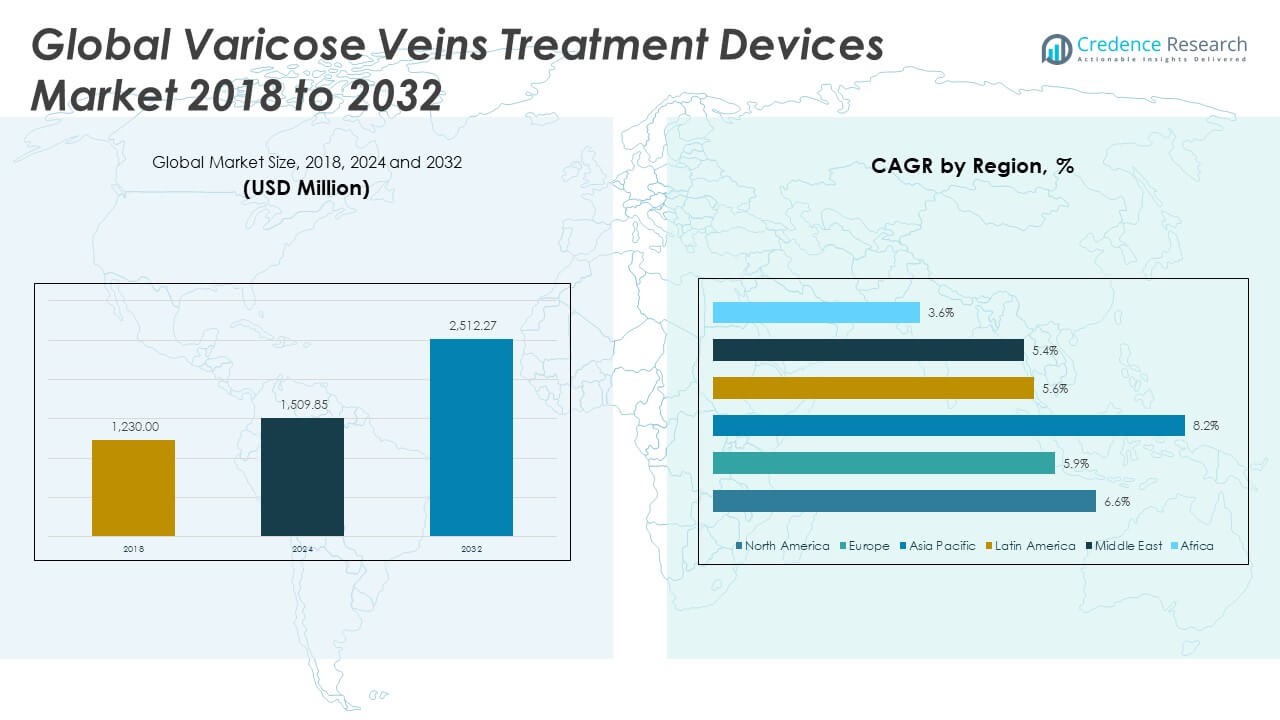
The Varicose Veins Treatment Devices Market size was valued at USD 1,230.00 million in 2018, increased to USD 1,509.85 million in 2024, and is anticipated to reach USD 2,512.27 million by 2032, at a CAGR of 6.62% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Varicose Veins Treatment Devices Market Size 2024 | USD 1,509.85 Million |
| Varicose Veins Treatment Devices Market, CAGR | 6.62% |
| Varicose Veins Treatment Devices Market Size 2032 | USD 2,512.27 Million |
Rising prevalence of varicose veins, driven by aging populations and sedentary lifestyles, has significantly increased the demand for minimally invasive treatment options. Technological advancements in laser and radiofrequency ablation, along with growing patient preference for outpatient procedures, are key factors propelling market growth. Additionally, increasing healthcare expenditure, awareness campaigns, and expanding insurance coverage for varicose veins procedures continue to boost the adoption of advanced treatment devices among both patients and healthcare providers.
North America leads the market due to strong healthcare infrastructure, early adoption of advanced technologies, and high awareness levels among patients. Europe follows closely, supported by favorable reimbursement policies and growing geriatric population. Emerging economies in Asia Pacific, particularly India and China, are witnessing rapid growth fueled by rising healthcare investments, expanding medical tourism, and increasing incidence of venous disorders. Latin America and the Middle East & Africa are gradually gaining traction due to improving access to vascular care and evolving treatment capabilities.
Market Insights:
- The Varicose Veins Treatment Devices Market was valued at USD 1,509.85 million in 2024 and is expected to reach USD 2,512.27 million by 2032, growing at a CAGR of 6.62%.
- Rising demand for minimally invasive procedures like endovenous and radiofrequency ablation is accelerating global adoption.
- Increasing aging population and sedentary lifestyles are driving the incidence of chronic venous disorders.
- High procedure costs and limited insurance coverage in developing regions restrict patient access to advanced treatments.
- North America leads the market with over 40% share, supported by strong healthcare infrastructure and early technology adoption.
- Asia Pacific is the fastest-growing region due to rapid urbanization, expanding healthcare access, and medical tourism.
- Market growth is further fueled by expanding vein clinics and ambulatory centers offering outpatient treatment options.
Market Drivers:
Growing Aging Population and Prevalence of Chronic Venous Diseases is Accelerating Demand for Effective Treatments
The steady rise in the global aging population contributes significantly to the demand for varicose veins treatments. Older adults are more susceptible to chronic venous insufficiency, which often results in varicose veins. Sedentary lifestyles and increased obesity rates across demographics further compound the condition’s prevalence. The Varicose Veins Treatment Devices Market benefits from the widespread need for minimally invasive solutions that offer faster recovery and fewer complications. It reflects growing patient preference for outpatient settings and procedures with minimal downtime. The demand is particularly strong in urban centers where lifestyle-induced vascular issues are more common. Governments and private institutions are investing in vascular health awareness, encouraging early diagnosis and treatment. These factors collectively increase the procedural volume and adoption of advanced treatment devices.
- For example, according to Medtronic’s official data, the ClosureFast™ radiofrequency ablation catheter has been used in over 2 million procedures globally. The device offers a minimally invasive alternative to surgical vein stripping, with faster recovery and less post-procedural pain, though specific recovery time comparisons are not publicly quantified.
Technological Advancements in Minimally Invasive Procedures are Driving Clinical Adoption
Technological innovations such as radiofrequency ablation, endovenous laser treatment, and mechanochemical ablation are enhancing treatment outcomes. These advancements reduce post-operative discomfort, shorten recovery periods, and eliminate the need for general anesthesia. The Varicose Veins Treatment Devices Market is increasingly benefiting from compact and portable systems that improve accessibility across healthcare facilities. Hospitals and specialized vascular clinics are upgrading their equipment to align with global best practices. It supports a consistent rise in patient throughput while maintaining clinical efficacy. Training programs for physicians are expanding rapidly, enabling safe use of new-generation devices. Healthcare providers prioritize devices with fewer complications and consistent results. Reimbursement policies are evolving to accommodate these procedures, further encouraging their use.
- For example, AngioDynamics’ VenaCure EVLT™ system using a 1470 nm laser and NeverTouch fiber shows clinically validated vein closure rates of approximately 98% at 12 months
Increased Awareness and Screening Initiatives are Boosting Early Diagnosis Rates
Public and private health organizations are launching awareness campaigns on the risks of untreated varicose veins. These initiatives aim to reduce stigma and encourage individuals to seek timely evaluation. Patients are more informed about treatment options than in the past, prompting proactive consultations. The Varicose Veins Treatment Devices Market gains from this trend through increased demand for diagnostic tools and early-stage interventions. Screening programs at community health centers and primary care facilities help in identifying cases earlier. This increases the adoption of less aggressive procedures and raises overall patient satisfaction. Social media, online platforms, and digital consultations also contribute to information dissemination. Insurance coverage and employer wellness programs are playing a role in promoting preventive care.
Rising Healthcare Infrastructure and Investments Across Emerging Markets are Enabling Wider Access
Emerging economies in Asia Pacific, Latin America, and the Middle East are witnessing significant growth in vascular care infrastructure. Governments are prioritizing non-communicable disease management, expanding public sector capabilities. Private hospitals and specialty clinics are equipping themselves with varicose veins treatment devices to serve an increasing urban population. The Varicose Veins Treatment Devices Market is expanding into secondary cities, driven by increased affordability and accessibility. It benefits from localized manufacturing, supply chain efficiencies, and regulatory approvals that support market entry. Public-private partnerships are enabling subsidized care, improving access in underserved regions. Telemedicine is extending consultation services to remote patients, guiding them toward treatment facilities. Local distributors and medical device companies are establishing strong networks to meet growing demand.
Market Trends
Rising Preference for Outpatient Vascular Procedures is Shaping Market Delivery Models
Healthcare systems are shifting towards outpatient care to improve cost efficiency and patient convenience. Many varicose vein procedures now take place in ambulatory surgical centers or physician offices. The Varicose Veins Treatment Devices Market is responding with compact, user-friendly systems tailored for such settings. These trends support broader treatment access in both developed and developing regions. It enables a shift from traditional hospital-based interventions to quicker, more personalized procedures. The move helps reduce hospital stay durations and increases procedural volume. Device makers are targeting this segment with innovations focused on portability and ease of use. Regulatory bodies are also adjusting compliance frameworks to support outpatient delivery.
Integration of AI-Powered Imaging and Diagnostics is Transforming Pre-Treatment Assessment
Artificial intelligence is improving the accuracy of venous disease detection and mapping. AI-driven ultrasound systems and imaging software enhance treatment planning by offering clearer anatomical visualization. The Varicose Veins Treatment Devices Market is incorporating these tools to improve clinical outcomes and reduce complications. Physicians can now rely on real-time diagnostics to determine optimal catheter paths and energy delivery points. It supports personalized treatment strategies that align with individual patient anatomy. These systems also enable automated documentation, improving workflow efficiency. As AI integration expands, device compatibility with digital health platforms is becoming a competitive differentiator. Investment in R&D for smart diagnostics is rising globally.
- For example, the Philips EPIQ CVx ultrasound platform leverages AI and automation to standardize vascular image acquisition and interpretation, ensuring consistent results across operators. Company documentation highlights automated measurement tools that reduce manual steps, help standardize interpretation, and improve reproducibility.
Growing Demand for Cosmetic and Aesthetic Vein Treatments is Influencing Product Development
Cosmetic concerns related to varicose and spider veins are influencing patient behavior across age groups. Many individuals seek treatment to improve leg appearance and boost confidence. The Varicose Veins Treatment Devices Market is seeing increased demand for low-risk procedures with minimal scarring and fast cosmetic recovery. Manufacturers are focusing on devices that offer precision energy delivery and aesthetic consistency. It drives development in mechanochemical and non-thermal modalities suited for smaller veins. Dermatology clinics and aesthetic centers are emerging as new customer segments. Marketing strategies are increasingly targeting lifestyle-focused consumers. Patient-friendly financing and package-based services are supporting market expansion.
- For example, Medtronic’s VenaSeal™ cyanoacrylate closure system, used for treating chronic venous insufficiency and advanced varicose veins, demonstrated promising outcomes in the 2025 Spectrum Venous Leg Ulcer (VLU) study. In patients with CEAP Class 6 disease (active venous ulcers due to severe varicose veins), the system achieved an 3% ulcer healing rate, 82.7% vein closure rate, and 83% freedom from ulcer recurrence at one year post-treatment.
Collaborations Between Hospitals and Device Manufacturers are Accelerating Innovation Cycles
Partnerships between healthcare providers and device companies are facilitating faster validation and adoption of new technologies. Hospitals provide real-world testing environments for prototype systems. The Varicose Veins Treatment Devices Market benefits from this feedback loop to refine design and usability. It accelerates regulatory approvals and shortens time to market. These collaborations also support joint training programs and technical support for clinicians. Global players are entering strategic agreements with regional providers to adapt technologies for local clinical needs. Co-branding initiatives and data-sharing agreements are becoming more common. These alliances ensure that emerging innovations align with both clinical efficiency and patient experience.
Market Challenges Analysis
High Treatment Costs and Limited Reimbursement in Developing Regions are Restricting Adoption
In many lower- and middle-income countries, high costs of varicose veins procedures remain a major barrier. Advanced technologies like endovenous ablation systems and laser devices require significant capital investment. The Varicose Veins Treatment Devices Market faces slow penetration in these markets due to limited health insurance coverage and low public awareness. It affects affordability for both public hospitals and private practitioners. Reimbursement remains inconsistent even in some high-income countries, especially for procedures categorized under aesthetics. Patients often delay treatment due to out-of-pocket expenses. This delay leads to complications and lowers the efficacy of minimally invasive interventions. Local governments are yet to prioritize vascular disorders in their health financing strategies.
Lack of Skilled Vascular Specialists and Inconsistent Training Standards are Hindering Market Growth
Effective use of varicose veins treatment devices requires trained vascular surgeons or interventional radiologists. In several regions, a shortage of such professionals limits patient access to safe and effective care. The Varicose Veins Treatment Devices Market faces a bottleneck in procedural volume due to workforce limitations. It also affects outcomes, increasing the risk of complications in inexperienced hands. Training opportunities for newer technologies remain fragmented and concentrated in urban areas. The absence of global standardization in skill certification further complicates adoption. Smaller clinics often avoid adopting newer devices due to fear of operational errors. Industry efforts to expand training programs have yet to bridge this skills gap.
Market Opportunities
Expansion of Medical Tourism and Cross-Border Treatment is Opening Growth Avenues
Several emerging countries are gaining popularity as medical tourism destinations for vascular treatments. Competitive pricing, experienced clinicians, and improving infrastructure attract patients from Europe, North America, and the Middle East. The Varicose Veins Treatment Devices Market can capitalize on this by partnering with hospitals offering bundled treatment packages. It helps device manufacturers scale faster and diversify across regions. Streamlined regulatory pathways in these markets also support quicker product approvals.
Increased Penetration of Telehealth and Remote Consultations is Creating New Entry Points
The adoption of telehealth is enabling early diagnosis and follow-ups for patients with varicose veins. Virtual care models allow specialists to guide local physicians or refer patients to advanced centers. The Varicose Veins Treatment Devices Market can tap into this network by aligning devices with teleconsultation workflows. It supports long-term patient engagement and drives recurring device usage in both urban and rural areas.
Market Segmentation Analysis:
The Varicose Veins Treatment Devices Market is segmented
By Type
Into endovenous ablation, radiofrequency ablation, laser ablation, sclerotherapy, and surgical ligation & stripping. Endovenous ablation holds a dominant share due to its high efficacy and preference for minimally invasive treatment. Radiofrequency ablation is gaining traction for its reduced post-operative pain and faster recovery compared to surgery. Laser ablation continues to be widely adopted in outpatient settings owing to its precision and lower risk profile. Sclerotherapy remains a cost-effective method for smaller veins, particularly in cosmetic cases. Surgical ligation and stripping are declining in usage, primarily reserved for complex or recurrent cases due to higher invasiveness.
- For instance, BTG’s Varithena® (polidocanol injectable foam) achieved a statistically significant improvement in vein appearance in 85% of treated patients at 12 weeks, as reported in BTG’s FDA submission data, with a complication rate under 1%.
By end use
The market is divided into vein clinics, hospitals, and ambulatory care units. Vein clinics lead the segment due to specialization, rapid procedures, and increased demand for cosmetic outcomes. Hospitals retain a significant share for treating advanced cases and complications. Ambulatory care units are emerging as viable settings due to growing outpatient procedural volumes and reduced healthcare costs. The segmentation reflects a shift toward outpatient, patient-friendly treatment environments across global regions.
- For example, USA Vein Clinics, the largest network of vein clinics in the United States with over 160 locations nationwide, provides minimally invasive vein treatments that typically allow patients to resume normal activities within a day, according to the clinic’s official patient care guidance.
Segmentation:
By Type
- Endovenous Ablation
- Radiofrequency Ablation
- Laser Ablation
- Sclerotherapy
- Surgical Ligation & Stripping
By End Use
- Vein Clinics
- Hospitals
- Ambulatory Care Units
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East
- Africa
Regional Analysis:
North America
The North America Varicose Veins Treatment Devices Market size was valued at USD 498.89 million in 2018, reached USD 605.74 million in 2024, and is anticipated to reach USD 1,006.67 million by 2032, at a CAGR of 6.6% during the forecast period. North America holds the largest market share of 40.2% in the global Varicose Veins Treatment Devices Market. It benefits from advanced healthcare infrastructure, strong reimbursement frameworks, and early adoption of minimally invasive technologies. High awareness among patients and healthcare providers supports increased diagnosis and timely intervention. Leading manufacturers are based in the U.S., supporting innovation and streamlined regulatory approvals. Outpatient clinics and ambulatory surgical centers are widely available, accelerating procedural volumes. Rising obesity and aging populations contribute to the growing patient base. Strong presence of board-certified vascular specialists ensures high procedural efficacy and demand for advanced devices. Investment in training and education further strengthens regional capabilities.
Europe
The Europe Varicose Veins Treatment Devices Market size was valued at USD 339.48 million in 2018, increased to USD 401.28 million in 2024, and is projected to reach USD 632.47 million by 2032, at a CAGR of 5.9% during the forecast period. Europe accounts for 26.3% of the global market share. It is supported by favorable reimbursement policies, public health initiatives, and wide availability of vein treatment clinics. Countries like Germany, France, and the UK lead in technology adoption and procedural volumes. The region has a well-structured network of vascular care units offering endovenous and laser-based treatments. Demand is driven by aging demographics and lifestyle-related venous disorders. Clinical trials and academic research centers promote continued innovation. Health-conscious consumers in Europe also drive demand for cosmetic vein procedures. Manufacturers focus on expanding distribution and clinician training across Central and Eastern Europe to tap growth opportunities.
Asia Pacific
The Asia Pacific Varicose Veins Treatment Devices Market size was valued at USD 249.94 million in 2018, reached USD 323.18 million in 2024, and is anticipated to reach USD 604.20 million by 2032, at a CAGR of 8.2% during the forecast period. Asia Pacific contributes 24.0% to the global market share. Rapid urbanization, increasing disposable income, and improved healthcare infrastructure are key factors driving growth. Countries like China, India, Japan, and South Korea show strong demand for minimally invasive procedures. Rising prevalence of varicose veins due to sedentary lifestyles and expanding medical tourism are creating favorable conditions. Local players are entering the market with cost-effective devices to meet regional needs. Government programs are improving awareness about venous disorders and encouraging early diagnosis. The market is also witnessing growing partnerships between hospitals and international device makers. Training programs and workshops for vascular specialists are expanding regionally.
Latin America
The Latin America Varicose Veins Treatment Devices Market size was valued at USD 71.34 million in 2018, rose to USD 86.65 million in 2024, and is forecast to reach USD 132.82 million by 2032, at a CAGR of 5.6% during the forecast period. The region represents 5.3% of the global market. Brazil and Mexico are the primary markets, supported by a growing middle-class population and private healthcare investments. Awareness about varicose veins treatment is increasing, especially in urban areas. Cosmetic concerns and demand for non-surgical treatments are rising among younger populations. Clinics are investing in energy-based devices to offer competitive procedures. Challenges include uneven access to care and inconsistent reimbursement across countries. Public-private partnerships are helping bridge infrastructure gaps. Regional distributors play a crucial role in increasing product availability and adoption.
Middle East
The Middle East Varicose Veins Treatment Devices Market size was valued at USD 50.68 million in 2018, reached USD 58.57 million in 2024, and is anticipated to hit USD 88.70 million by 2032, at a CAGR of 5.4% during the forecast period. It holds a 3.5% share of the global market. Demand is supported by rising chronic venous diseases and improved access to vascular care in countries like the UAE and Saudi Arabia. Medical tourism is also fueling adoption of advanced treatment technologies. Hospitals are upgrading to minimally invasive platforms to reduce patient recovery times. The region benefits from collaborations with global manufacturers and clinical training initiatives. Patient preference for non-invasive procedures is shaping treatment offerings in private clinics. Market expansion is influenced by increased healthcare investments in Gulf Cooperation Council countries. Device manufacturers are targeting the region with localized support and product customization.
Africa
The Africa Varicose Veins Treatment Devices Market size was valued at USD 19.68 million in 2018, increased to USD 34.43 million in 2024, and is projected to reach USD 47.40 million by 2032, at a CAGR of 3.6% during the forecast period. The region represents 1.9% of the global market share. Growth is modest due to limited access to specialized vascular care and high device costs. South Africa leads in terms of adoption, driven by private healthcare networks. Awareness about varicose vein treatment remains low in many countries. Multinational organizations and NGOs are promoting venous health education in underserved regions. Opportunities exist in urban centers where healthcare spending is rising. The market is gradually opening to global players through distributor partnerships. Public sector initiatives focused on non-communicable diseases may create long-term demand for treatment infrastructure.
Key Player Analysis:
- AngioDynamics
- Medtronic
- Teleflex Incorporated
- Sciton, Inc.
- Dornier Medtech
- Merit Medical Systems
- Alma Lasers
- Biolitec AG
- Boston Scientific Corporation
Competitive Analysis:
The Varicose Veins Treatment Devices Market features intense competition among well-established global vendors and emerging innovators. Medtronic, AngioDynamics, Biolitec, Teleflex, Boston Scientific, Sciton, Alma Lasers, and Energist command leading positions with extensive product ranges covering laser, radiofrequency, and ablation systems. It benefits from continuous product development and strategic collaborations between manufacturers and vascular clinics to refine device performance. Innovators target enhanced safety and efficiency to differentiate from mature competitors. It sees increasing patient preference for compact, minimally invasive platforms that facilitate office-based procedures. Geographic expansion into emerging markets represents a critical growth strategy. Regulatory approvals, clinician training support, and distributor partnerships shape competitive dynamics. Partnerships with medical centers support validation of new technologies. Price-competitive local entrants challenge global players in cost-sensitive regions. Market leaders continue to invest in R&D and clinician support to secure long-term growth.
Recent Developments:
- In July 2025, Teleflex Incorporated completed the acquisition of the Vascular Intervention business of Biotronik for €760 million. This acquisition significantly expands Teleflex’s portfolio of peripheral and coronary vascular intervention products, strengthening its position in the interventional market, including tools relevant to varicose veins treatment.
- In June 2023, Biolitec AG introduced the Elves Radial 2ring Pro laser fiber and the Leonardo 1940 laser, designed for minimally invasive varicose veins therapy. These products provide versatile laser solutions for treating both complex and smaller venous presentations, promising improved procedure outcomes and rapid convalescence.
Market Concentration & Characteristics
The Varicose Veins Treatment Devices Market remains moderately concentrated among key multinational manufacturers that control major market share and influence pricing and innovation dynamics. Medtronic, AngioDynamics, Biolitec, Lumenis, Teleflex, and Sciton dominate due to broad device portfolios and global distribution networks. It exhibits a tiered structure: Tier‑1 players maintain scale and brand recognition, while Tier‑2 and local firms compete on affordability and niche applications. It demands strong regulatory compliance, clinical validation, and post‑market clinician training, which favor established firms. Smaller regional players face barriers to entry including capital constraints and certification timelines. It sees specialization by device type-endovenous laser, radiofrequency, sclerotherapy-where manufacturers compete on efficacy and user interface. Strength of partnerships with clinics and training institutions plays a strategic role. Price sensitivity in emerging markets drives demand for lower‑cost systems. Market concentration remains stable but evolving as new device modalities enter the field.
Report Coverage:
The research report offers an in-depth analysis based on Type and End Use. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for minimally invasive varicose veins treatments will continue to rise due to growing patient preference for outpatient care.
- Technological advancements in ablation and imaging devices will enhance treatment precision and safety.
- Expansion of medical tourism in emerging regions will increase cross-border procedures and device demand.
- Integration of AI and diagnostic platforms will support better clinical decision-making and personalized treatment plans.
- Growing investments in vascular health infrastructure will widen access to advanced treatment options.
- Cosmetic awareness among younger demographics will boost adoption of aesthetic-focused vein therapies.
- Collaborations between hospitals and device manufacturers will accelerate clinical training and product innovation.
- Reimbursement policy improvements in developing countries will support broader market penetration.
- Local manufacturing and distribution partnerships will help address affordability and regulatory challenges.
- Increasing awareness campaigns and preventive screenings will drive early diagnosis and long-term market sustainability.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Aging Population and Sedentary Lifestyles
The global increase in elderly populations and sedentary lifestyles is leading to a higher prevalence of chronic venous disorders, directly boosting demand for varicose veins treatment devices as more patients seek effective and minimally invasive solutions.
Technological Advancements in Minimally Invasive Procedures
Innovations such as radiofrequency ablation, endovenous laser treatment, and mechanochemical ablation are improving clinical outcomes, reducing recovery times, and making treatments more accessible, thereby accelerating market adoption.
Expansion of Outpatient and Ambulatory Care Models
The shift toward outpatient and ambulatory care settings is increasing procedural volumes and patient preference for minimally invasive, quick-recovery treatments, driving demand for compact and user-friendly varicose veins treatment devices.
Rising Awareness and Screening Initiatives
Public and private health campaigns, along with increased insurance coverage and preventive screenings, are leading to earlier diagnosis and intervention, which in turn raises the adoption of advanced treatment devices.
Healthcare Infrastructure Growth in Emerging Markets
Rapid improvements in healthcare infrastructure, increased investments, and expanding medical tourism in Asia Pacific, Latin America, and the Middle East are enabling broader access to advanced varicose veins treatment technologies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Varicose Veins Treatment Devices Market?
What factors are driving the growth of the Varicose Veins Treatment Devices Market?
What are the key segments within the Varicose Veins Treatment Devices Market?
What are some challenges faced by the Varicose Veins Treatment Devices Market?
Who are the major players in the Varicose Veins Treatment Devices Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Endovenous Ablation
- 1.2.2 Radiofrequency Ablation
- 1.2.3 Laser Ablation
- 1.2.4 Sclerotherapy
- 1.2.5 Surgical Ligation & Stripping
- 1.3 By End Use
- 1.3.1 Vein Clinics
- 1.3.2 Hospitals
- 1.3.3 Ambulatory Care Units
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,509.85 million → 2032: USD 2,512.27 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Varicose Veins Treatment Devices Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Varicose Veins Treatment Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Varicose Veins Treatment Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Varicose Veins Treatment Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Varicose Veins Treatment Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Varicose Veins Treatment Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Varicose Veins Treatment Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Varicose Veins Treatment Devices Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,509.85 million → 2032: USD 2,512.27 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Varicose Veins Treatment Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Endovenous Ablation
- 12.3.7.2 Radiofrequency Ablation
- 12.3.7.3 Laser Ablation
- 12.3.7.4 Sclerotherapy
- 12.3.7.5 Surgical Ligation & Stripping
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End Use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Vein Clinics
- 12.4.7.2 Hospitals
- 12.4.7.3 Ambulatory Care Units
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Varicose Veins Treatment Devices End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Varicose Veins Treatment Devices Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Varicose Veins Treatment Devices Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Varicose Veins Treatment Devices Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Medtronic
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 AngioDynamics
- 18.4 Teleflex Incorporated
- 18.5 Biolitec AG
- 18.6 Boston Scientific Corporation
- 18.7 Sciton, Inc.
- 18.8 Dornier Medtech
- 18.9 Merit Medical Systems
- 18.10 Alma Lasers
- 18.11 BTG International
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

