
Market Overview
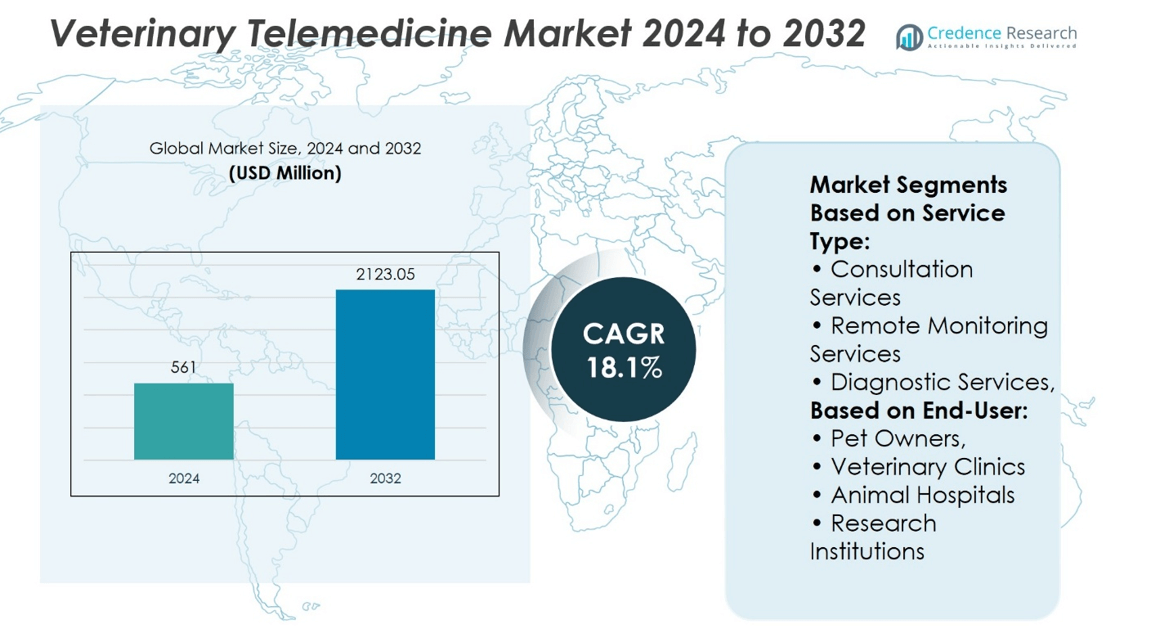
Veterinary Telemedicine Market size was valued at USD 561 million in 2024 and is anticipated to reach USD 2123.05 million by 2032, at a CAGR of 18.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Veterinary Telemedicine Market Size 2024 | USD 561 million |
| Veterinary Telemedicine Market, CAGR | 18.1% |
| Veterinary Telemedicine Market Size 2032 | USD 2123.05 million |
The Veterinary Telemedicine Market is driven by rising pet ownership, increasing demand for accessible veterinary care, and advancements in digital health technologies. Busy lifestyles and rural veterinary shortages push pet owners toward remote consultations for convenience and timely intervention. Regulatory support and growing adoption of telehealth platforms by clinics further accelerate market expansion. Trends include integration of AI for diagnostic assistance, mobile app-based service delivery, and cloud-based health record management. Subscription-based models and 24/7 virtual care services are also gaining traction, as providers focus on enhancing user experience and expanding reach across underserved and remote regions.
North America holds the largest share of the Veterinary Telemedicine Market, driven by high pet ownership and advanced digital infrastructure, followed by Europe and the rapidly growing Asia Pacific region. Emerging markets in Latin America and the Middle East & Africa show increasing adoption due to rising veterinary awareness. Key players in the market include TeleVet, Vetster, VetNOW, Pawp, VETetc, Vet2Pet, DVM360, Pet Care Telemedicine, FurEver Vets, Whiskers Wags, Lifelong Pet Care, and Animal Health Connected Source.
Market Insights
- The Veterinary Telemedicine Market was valued at USD 561 million in 2024 and is projected to grow at a CAGR of 18.1% from 2024 to 2032.
- Growing pet ownership, increased awareness of pet health, and the need for accessible veterinary care are driving market demand.
- AI-powered diagnostics, cloud-based health record systems, and mobile app integration are key trends shaping service delivery and user engagement.
- The market is competitive, with leading players including TeleVet, Vetster, VetNOW, Pawp, and Vet2Pet focusing on platform expansion and partnerships.
- Regulatory limitations, lack of standardized protocols, and limited digital literacy in rural areas restrain broader market adoption.
- North America holds the largest market share, followed by Europe; Asia Pacific is the fastest-growing region due to rising digital infrastructure and pet adoption.
- Service providers are enhancing 24/7 access, multilingual support, and real-time care
Market Drivers
Rising Pet Ownership and Demand for Convenient Veterinary Access Strengthen Market Growth
The Veterinary Telemedicine Market is gaining momentum due to increasing global pet ownership and the growing demand for accessible veterinary services. Urbanization and lifestyle changes have encouraged people to adopt companion animals, which has raised the need for timely medical care. Traditional in-clinic visits often pose logistical challenges, prompting pet owners to seek remote consultation options. The convenience of telemedicine platforms allows for immediate advice on minor health concerns, which helps prevent complications. It also supports continuous monitoring of chronic conditions in pets without frequent clinic visits. This shift in consumer preference strongly supports the adoption of veterinary telehealth solutions.
- For instance, IDEXX Laboratories reported conducting approximately 2.5 million telemedicine consultations worldwide in 2023 through its VetConnect PLUS platform.
Technological Advancements in Digital Health Infrastructure Accelerate Market Expansion
The integration of advanced technologies into animal healthcare has fueled the Veterinary Telemedicine Market. Mobile apps, AI-powered diagnostic tools, and cloud-based medical records simplify the process of remote consultations and follow-ups. Telemedicine platforms now support real-time video conferencing, high-resolution imaging, and secure data sharing between veterinarians and pet owners. It has significantly improved diagnostic accuracy and client communication. Many service providers invest in tech-enabled solutions to reduce wait times and improve service efficiency. The digital transformation in veterinary services continues to drive innovation and market penetration.
- For instance, Antech Diagnostics implemented an AI-driven imaging analysis system that processes over 1 million diagnostic images annually, enhancing accuracy and reducing turnaround time. Furthermore, Vetter Software's cloud-based practice management platform supports more than 4,500 veterinary clinics globally, facilitating seamless access to patient records during teleconsultations.
Veterinarian Shortages and Increased Pressure on Clinics Drive Remote Service Adoption
Veterinary practices, particularly in rural and underserved regions, face ongoing challenges from staff shortages. The Veterinary Telemedicine Market addresses these gaps by enabling clinics to extend care virtually, helping manage workload and expand service reach. It offers a practical solution to areas lacking full-time veterinary professionals, improving animal health outcomes across geographies. Clinics use telehealth for triage, follow-ups, and behavioral consultations, which frees up in-person resources for emergency or complex cases. This model enhances operational efficiency and optimizes clinic capacity. It also aligns with broader trends toward healthcare decentralization.
Favorable Regulatory Shifts and Insurance Support Promote Market Maturity
Governments and veterinary associations are revising regulations to accommodate telemedicine within standard veterinary practices. The Veterinary Telemedicine Market benefits from this regulatory clarity, which encourages broader implementation by professionals. Some pet insurance providers now include teleconsultations in their coverage, making the service more affordable for pet owners. These policy changes reduce entry barriers and increase user trust in virtual care. It fosters a supportive ecosystem where veterinary telemedicine is recognized as a legitimate mode of service delivery. These developments contribute to the market’s sustained advancement and integration into mainstream animal healthcare.
Market Trends
Wider Integration of Mobile Platforms and Real-Time Communication Tools Enhances Service Delivery
The Veterinary Telemedicine Market \ is witnessing increased adoption of mobile-based platforms that support real-time interaction between pet owners and veterinarians. These platforms offer high-definition video calls, secure chat features, and easy access to medical records. It enables quick responses to health inquiries, medication adjustments, and behavioral consultations. The shift toward mobile-first solutions aligns with rising smartphone penetration and digital literacy among pet owners. Telemedicine apps are becoming more sophisticated, offering automated appointment scheduling, reminders, and payment integration. These advancements improve user engagement and streamline the veterinary care experience.
- For instance, Vetster’s mobile platform facilitated over 300,000 live video consultations in 2023, connecting pet owners directly with licensed veterinarians across North America.
Growing Use of AI and Data Analytics Supports Personalized Animal Healthcare
Artificial intelligence and data analytics are playing a growing role in the Veterinary Telemedicine Market \. AI algorithms assist in analyzing symptoms and medical history to generate preliminary assessments. It allows veterinarians to make informed decisions more efficiently and helps detect patterns in chronic conditions. Predictive analytics tools help monitor disease progression and treatment responses in real time. Platforms are increasingly embedding AI features to support decision-making and improve care accuracy. This trend is creating a more proactive and personalized approach to pet healthcare.
- For instance, SignalPET’s AI-powered diagnostic platform processes over 600,000 radiographic images annually, providing veterinarians with automated analysis to identify abnormalities faster.
Hybrid Models Combine In-Person and Virtual Services for Greater Flexibility
Veterinary clinics are adopting hybrid models that blend telemedicine with traditional in-clinic services to offer comprehensive care. The Veterinary Telemedicine Market reflects this transition, with providers offering virtual consultations for follow-ups and non-urgent issues. It reduces congestion in physical clinics and improves appointment availability for critical cases. Clinics benefit from better time management and broader client outreach through this model. Pet owners value the flexibility to choose between virtual or physical visits based on their needs. This integration of care formats is shaping long-term service models in the veterinary sector.
Telehealth Adoption Expands Across Livestock and Large Animal Segments
While telemedicine initially focused on companion animals, it is now gaining traction in livestock and equine care. The Veterinary Telemedicine Market is expanding as large animal veterinarians leverage remote tools for monitoring herd health, post-treatment evaluations, and biosecurity. It offers a practical solution to serve remote farms and ranches where frequent travel is not feasible. Wearable sensors and remote imaging are increasingly used to transmit vital signs and diagnostics to veterinarians. These innovations improve decision-making and reduce downtime for farm operations. The growing relevance in large animal care is diversifying the telemedicine landscape.
Market Challenges Analysis
Regulatory Ambiguities and Licensing Barriers Limit Market Scalability
The Veterinary Telemedicine Market faces considerable hurdles due to inconsistent regulations and licensing constraints across regions. Many jurisdictions require a pre-established veterinarian-client-patient relationship (VCPR), which restricts first-time consultations via telemedicine. It limits the ability of providers to scale operations across state or national boundaries. Licensing requirements often vary, compelling veterinarians to hold multiple certifications to offer services in different areas. These challenges create operational inefficiencies and slow market penetration. Regulatory bodies are yet to standardize telehealth practices in veterinary care, creating uncertainty for both providers and users.
Technological Limitations and Connectivity Gaps Affect Service Delivery
The Veterinary Telemedicine Market also contends with infrastructure challenges that hinder consistent service delivery. Poor internet connectivity in rural and remote areas restricts access to virtual consultations, especially for large animal or livestock care. It affects real-time video quality and data transmission, reducing diagnostic accuracy. Some clinics lack the resources to invest in advanced telehealth systems or train staff in digital tools. Data security concerns and lack of interoperability between platforms further complicate integration. These limitations reduce the effectiveness of remote care and impact user confidence in telemedicine solutions.
Market Opportunities
Expanding Preventive Care and Wellness Monitoring Opens New Avenues for Growth
The Veterinary Telemedicine Market is well-positioned to support the rising focus on preventive care and long-term wellness monitoring for animals. Pet owners increasingly seek regular health assessments, nutritional advice, and behavioral consultations outside emergency visits. It enables continuous engagement between veterinarians and clients, improving compliance with treatment plans. Telemedicine platforms can incorporate remote monitoring tools and wearable devices to track vital signs and activity levels. This data-driven approach enhances early detection and proactive care, creating value beyond traditional clinical visits. Preventive services through telehealth present a scalable and recurring revenue model for providers.
Global Expansion and Rural Outreach Present Strong Market Potential
Unmet veterinary needs in rural and underserved regions create strong opportunities for market expansion. The Veterinary Telemedicine Market can bridge the accessibility gap by delivering remote consultations, follow-ups, and triage services to areas with limited veterinary infrastructure. It allows professionals to extend their reach without physical relocation, increasing their service footprint. Mobile connectivity improvements and broader smartphone access support the feasibility of remote care in emerging markets. Localized telemedicine solutions tailored to livestock and agricultural practices further expand use cases. These developments offer pathways to diversify service offerings and capture new customer segments.
Market Segmentation Analysis:
By Service Type
The Veterinary Telemedicine Market includes a range of service types designed to support remote veterinary care across different settings. Consultation services dominate this segment, offering real-time video or voice interaction between veterinarians and pet owners. These services enable timely medical advice without requiring in-person visits. Remote monitoring services are expanding, particularly in chronic condition management, allowing continuous tracking of animal health data through wearable devices. Diagnostic services support early identification of issues by enabling remote interpretation of lab results and imaging. Emergency care services provide critical support during off-hours or when immediate physical access to veterinary clinics is not feasible. For instance, GuardianVets has reported a 40% increase in after-hours emergency consultations through its integrated telemedicine platform, improving outcomes in time-sensitive situations.
- For instance, according to the American Veterinary Medical Association (AVMA) 2023 survey, approximately 120,000 veterinary clinics in the U.S. reported using telemedicine platforms for consultation and diagnostic support, with an average of 150,000.
By End User
The Veterinary Telemedicine Market caters to a diverse group of end users with varying needs. Pet owners represent the largest segment, driven by the growing demand for convenience and accessibility in pet healthcare. Veterinary clinics use telemedicine to expand their service offerings and maintain continuity of care during non-office hours. Animal hospitals leverage these platforms to manage post-operative care and follow-ups more efficiently. Research institutions utilize telehealth tools to monitor trial subjects remotely, reducing logistical challenges and improving data collection. For instance, Airvet reported that more than 70% of its users are pet owners who engage in follow-up care through the platform, reducing unnecessary in-clinic visits and improving client retention.
- For instance, the American Veterinary Medical Association (AVMA) 2023 survey found that over 175,000 pet owners participated in telemedicine consultations within that year in the United States.
Segments:
Based on Service Type:
- Consultation Services
- Remote Monitoring Services
- Diagnostic Services,
Based on End-User:
- Pet Owners,
- Veterinary Clinics
- Animal Hospitals
- Research Institutions
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America dominates the global veterinary telemedicine market, holding approximately 45% of the total share. This leadership is driven by high pet ownership rates, advanced digital infrastructure, and strong awareness of animal health management. The United States and Canada both support the expansion of telemedicine services through favorable regulatory policies and active participation from leading veterinary networks. A robust pet insurance landscape further encourages adoption by offsetting consultation costs. Clinics and hospitals in this region actively integrate video consultations, digital prescriptions, and remote monitoring tools into their service offerings. The presence of technology-driven companies such as Vetster and TeleVet has streamlined the availability of teleconsultations and emergency response systems across suburban and rural areas.
Europe
Europe accounts for around 25% of the global veterinary telemedicine market, positioning it as the second-largest regional contributor. Countries including the United Kingdom, Germany, and France have adopted regulatory measures that allow virtual veterinary services with clear guidelines for prescription issuance. The European pet care industry continues to emphasize digital transformation, with many veterinary practices shifting to cloud-based platforms. This region benefits from a high density of trained veterinary professionals and pet owners who are increasingly relying on digital tools for follow-up care and preventive health check-ups. Innovations in AI-supported diagnostics and growing support from veterinary associations help reinforce the demand for virtual care services.
Asia Pacific
Asia Pacific holds close to 15% of the global market and is currently the fastest-growing region in this segment. The rising trend of pet humanization, coupled with improving access to mobile and internet services, has expanded the reach of telemedicine solutions in countries such as India, China, Japan, and Australia. India, in particular, has witnessed a surge in local telehealth platforms offering affordable virtual consultations for small and large animals. Government initiatives aimed at digitizing veterinary care, especially for livestock owners in remote areas, have significantly contributed to market development. The region continues to experience rising demand from urban pet owners seeking quick and cost-effective medical consultations for their pets.
Latin America
Latin America contributes about 10% to the global veterinary telemedicine market. Brazil is the leading market in this region, supported by increasing pet adoption, growing urbanization, and strengthening veterinary service infrastructure. Veterinarians and clinics across urban hubs in Brazil and Mexico are adopting telemedicine to improve accessibility and manage high caseloads. Although internet penetration remains uneven across rural zones, mobile-based veterinary apps are bridging this gap. Livestock producers are also beginning to adopt remote veterinary services for disease surveillance and herd health planning, which contributes to overall regional growth.
The Middle East and Africa
The Middle East and Africa region holds the remaining 5% share of the market. Adoption is comparatively lower but shows steady improvement due to expanding veterinary infrastructure and increasing demand for companion animal care. Emerging markets such as Saudi Arabia, South Africa, and Kenya are witnessing rising interest in mobile-based veterinary services. Startups and government initiatives are helping raise awareness about telemedicine, especially in underserved areas. The region's growth potential remains strong, provided there is continued investment in digital infrastructure and veterinary outreach programs.
Key Player Analysis
- VetNOW
- Whiskers Wags
- Vetster
- Pet Care Telemedicine
- Lifelong Pet Care
- Veterinary Telemedicine
- DVM360
- FurEver Vets
- Pawp
- Vet2Pet
- VETetc
Competitive Analysis
The Veterinary Telemedicine Market is shaped by key players including TeleVet, Vetster, VetNOW, Pawp, VETetc, Vet2Pet, DVM360, Pet Care Telemedicine, FurEver Vets, Whiskers Wags, Lifelong Pet Care, and Animal Health Connected Source. These companies drive market growth through technological innovation, platform scalability, and user-centric service models. They focus on enhancing virtual care delivery by integrating video consultations, digital health records, and AI-assisted diagnostic tools. Competitive strategies emphasize improving accessibility, offering mobile compatibility, and ensuring compliance with veterinary telehealth regulations. Most platforms are expanding their reach through partnerships with veterinary clinics and hospitals, while also targeting direct-to-consumer models to capture the growing pet owner base. Continuous investment in platform development, client engagement tools, and multi-species care support helps maintain a competitive edge. As digital adoption in animal healthcare accelerates, competition intensifies around service differentiation, platform reliability, and customer retention.
Recent Developments
- In October 2024, Dial A Vet acquired SpeakToAVet.com to strengthen its market presence and provide affordable pet-health services across the world. This strategic move will lead to significant market expansion of the company in the telehealth sector.
- In August 2024, Vetster received “Pet App of the Year” award for the third consecutive year. This app is regarded as the fastest growing pet telehealth platform in recent times.
- In July 2024, Ontario-based Canadian telemedicine company, VetSon expanded their existing veterinary telehealth platform by adding novel animal care options to its existing platform.
Market Concentration & Characteristics
The Veterinary Telemedicine Market demonstrates moderate market concentration, with a mix of established players and emerging platforms competing to expand their service reach. It is characterized by rapid digital adoption, strong demand for convenience-driven care, and the growing role of virtual consultations in routine and emergency veterinary services. The market includes both B2B models targeting clinics and B2C models aimed at pet owners. It remains technology-intensive, relying on mobile platforms, cloud storage, AI diagnostics, and real-time communication tools. It is also price-sensitive in emerging regions, where affordability influences adoption rates. Service differentiation lies in platform usability, integration with health records, subscription models, and multilingual access. Companies prioritize partnerships with veterinary clinics, tech upgrades, and customer engagement strategies to maintain competitive edge. The Veterinary Telemedicine Market benefits from rising pet healthcare awareness and favorable regulatory shifts, though it faces operational challenges in rural deployment and cross-border service standardization.
Report Coverage
The research report offers an in-depth analysis based on Service Type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand with increased acceptance of remote veterinary consultations among pet owners.
- AI-powered diagnostic tools will improve clinical decision-making and service efficiency.
- Mobile apps will become the primary platform for telemedicine access and appointment management.
- Integration with electronic health records will streamline follow-up care and continuity of treatment.
- Demand for 24/7 virtual veterinary support will rise, especially in urban and remote areas.
- Veterinary clinics will increasingly adopt hybrid care models combining in-person and virtual services.
- Startups and tech firms will enter the market, intensifying competition and innovation.
- Subscription-based telehealth services will attract more pet owners seeking affordable care.
- Expansion into livestock and farm animal care will open new revenue streams.
- Regulatory frameworks will evolve to support broader adoption and cross-border telehealth services.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Pet Ownership and Demand for Convenient Veterinary Access
Increasing global pet ownership and urbanization have led to higher demand for accessible veterinary care. Telemedicine platforms provide pet owners with immediate access to veterinary advice, reducing the need for in-person visits and supporting timely intervention.
Technological Advancements in Digital Health Infrastructure
The integration of mobile apps, AI-powered diagnostics, and cloud-based health records has streamlined remote consultations and improved diagnostic accuracy. These innovations make telemedicine more efficient and appealing to both providers and pet owners.
Veterinarian Shortages and Increased Pressure on Clinics
Staff shortages, especially in rural and underserved areas, have made it difficult for clinics to meet demand. Telemedicine enables clinics to extend their reach virtually, manage workloads, and provide care to regions lacking full-time veterinary professionals.
Favorable Regulatory Shifts and Insurance Support
Evolving regulations and increased insurance coverage for teleconsultations are lowering barriers to adoption. Regulatory clarity and insurance reimbursement make telemedicine a more viable and trusted option for both providers and pet owners.
Expansion of Preventive Care and Wellness Monitoring
Growing interest in preventive animal healthcare and wellness monitoring is driving the adoption of telemedicine platforms. Remote monitoring tools and wearable devices enable continuous engagement and early detection of health issues, supporting long-term animal wellness.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Veterinary Telemedicine Market and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Veterinary Telemedicine Market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Veterinary Telemedicine ket?
Who are the leading companies in the Veterinary Telemedicine Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Pet Owners
- 1.2.2 Veterinary Clinics
- 1.2.3 Animal Hospitals
- 1.2.4 Research Institutions
- 1.3 By Animal Type
- 1.3.1 Companion Animals
- 1.3.2 Livestock
- 1.3.3 Equine
- 1.3.4 Others
- 1.4 By Service Type
- 1.4.1 Consultation Services
- 1.4.2 Remote Monitoring Services
- 1.4.3 Diagnostic Services
- 1.4.4 Emergency Care Services
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 561 million → 2032: USD 2123.05 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Veterinary Telemedicine Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Veterinary Telemedicine Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Veterinary Telemedicine Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Veterinary Telemedicine Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Veterinary Telemedicine Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Veterinary Telemedicine Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Veterinary Telemedicine Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Veterinary Telemedicine Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 561 million → 2032: USD 2123.05 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Veterinary Telemedicine Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Pet Owners
- 12.3.7.2 Veterinary Clinics
- 12.3.7.3 Animal Hospitals
- 12.3.7.4 Research Institutions
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Animal Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Companion Animals
- 12.4.7.2 Livestock
- 12.4.7.3 Equine
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Service Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Consultation Services
- 12.5.7.2 Remote Monitoring Services
- 12.5.7.3 Diagnostic Services
- 12.5.7.4 Emergency Care Services
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Veterinary Telemedicine End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Veterinary Telemedicine Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Veterinary Telemedicine Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Veterinary Telemedicine Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 TeleVet
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Vetster
- 18.4 VetNOW
- 18.5 Pawp
- 18.6 Vet2Pet
- 18.7 DVM360
- 18.8 Pet Care Telemedicine
- 18.9 FurEver Vets
- 18.10 Whiskers Wags
- 18.11 Lifelong Pet Care
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

