
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
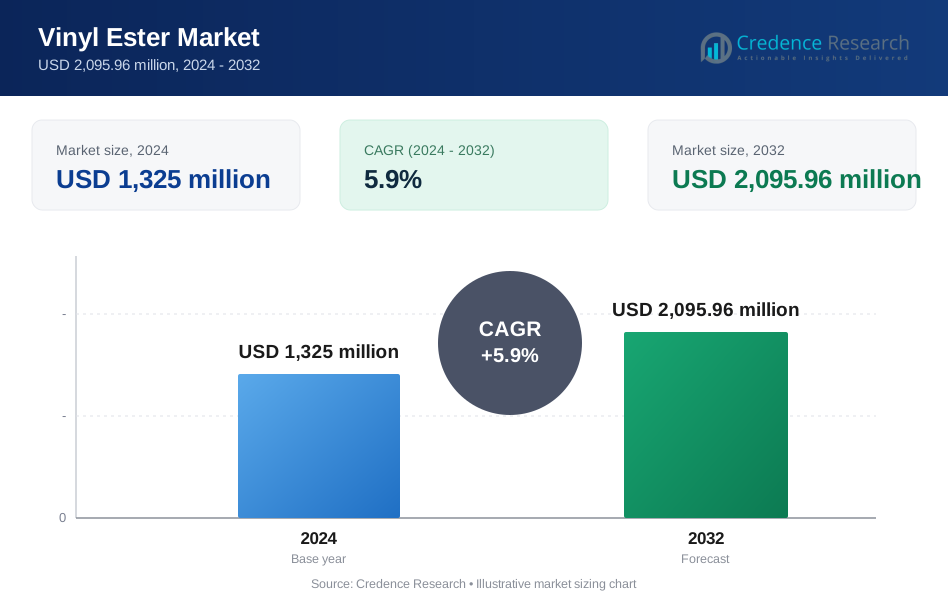
| Vinyl Ester Market Size 2024 | USD 1,325 million |
| Vinyl Ester Market, CAGR | 5.9% |
| Vinyl Ester Market Size 2032 | USD 2,095.96 million |
Market Overview
The vinyl ester market is projected to grow from USD 1,325 million in 2024 to USD 2,095.96 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.9%.
The vinyl ester market is driven by increasing demand from various end-use industries, including construction, automotive, and marine, due to its superior chemical resistance and durability. The growing trend toward lightweight and high-performance materials further fuels market growth, as vinyl esters offer excellent mechanical properties and corrosion resistance. Additionally, advancements in manufacturing technologies and the rising adoption of eco-friendly resins enhance the appeal of vinyl esters. As industries seek sustainable solutions, the shift toward bio-based vinyl esters is gaining momentum, aligning with global sustainability initiatives and enhancing market prospects.
The geographical analysis of the vinyl ester market reveals strong growth across regions, particularly in North America and Asia-Pacific. North America, with key players such as INEOS Composites, AOC, and Interplastic Corporation, accounts for a significant market share due to robust demand in construction and renewable energy sectors. Meanwhile, the Asia-Pacific region is rapidly expanding, driven by industrialization and infrastructure development, featuring major companies like Sino Polymer Co., Ltd. and SWANCOR. These key players leverage their advanced manufacturing capabilities to meet the increasing demand for vinyl ester applications across various industries globally.
Market Drivers
Superior Chemical Resistance
Vinyl ester exhibits exceptional resistance to chemicals, acids, alkalis, and solvents, making it ideal for applications in harsh environments such as chemical processing plants, wastewater treatment facilities, and oil and gas pipelines. For instance, vinyl ester resins provide superior chemical and corrosion resistance, making them an excellent choice for protective coatings in harsh industrial environments. Its ability to withstand aggressive substances ensures the integrity and longevity of structures, reducing maintenance needs and enhancing operational efficiency. As industries prioritize safety and reliability, the demand for vinyl ester continues to grow, reinforcing its position as a preferred material in critical applications.
Excellent Mechanical Properties
The mechanical properties of vinyl ester, characterized by high strength, stiffness, and impact resistance, make it suitable for structural components across various industries, including marine, construction, and transportation. For example, vinyl ester resins have high tensile elongation and heat distortion temperature, making them suitable for high-strength applications. Its robust nature allows for the design of lighter yet stronger materials, which is essential in enhancing performance and safety in applications like boat construction and building frameworks. As industries evolve and seek materials that deliver both performance and efficiency, vinyl ester stands out as a key player in meeting these demands.
Growing Demand for Infrastructure Development
Increased investment in infrastructure projects worldwide significantly drives the demand for high-performance materials like vinyl ester. As nations focus on modernizing their infrastructure, vinyl ester’s properties make it an attractive option for construction and rehabilitation efforts. Additionally, the increasing adoption of vinyl ester in renewable energy applications, such as wind turbine blades, contributes to market growth, as industries align with global sustainability goals and seek innovative solutions for energy production.
Stricter Environmental Regulations
Stricter environmental regulations further catalyze the adoption of vinyl ester, as industries seek durable and corrosion-resistant materials to reduce maintenance costs and environmental impact. The material's extensive applications in various sectors—such as pipes and tanks, marine construction, chemical processing, and renewable energy—underscore its versatility and alignment with regulatory standards. This growing emphasis on sustainability and performance positions vinyl ester as a vital component in the materials landscape, ensuring its relevance for years to come.
Market Trends
Growing Demand in Infrastructure and Renewable Energy
The vinyl ester market is experiencing significant growth driven by increasing demand in infrastructure projects and renewable energy applications. Vinyl ester’s excellent corrosion resistance makes it an ideal choice for infrastructure projects, particularly in harsh environments such as coastal areas and industrial settings. Its durability and long lifespan reduce maintenance costs while extending the life of infrastructure assets, positioning it as a preferred material in the construction of bridges, pipelines, and other critical infrastructure. In the renewable energy sector, vinyl ester plays a crucial role in the manufacturing of wind turbine blades, offering lightweight, durable, and corrosion-resistant components essential for optimal performance. Additionally, its application in solar energy construction, specifically for solar panel frames and support structures, highlights its high strength and weather resistance, aligning with global sustainability initiatives.
Expanding Applications in Marine and Chemical Processing Industries
Another key trend driving the vinyl ester market is its expanding applications in the marine industry and the chemical processing sector. In the marine industry, vinyl ester is widely used in constructing boats, yachts, and commercial vessels due to its excellent water resistance and impact strength, ensuring reliability and safety in demanding marine environments. For example, vinyl ester resins are used in the production of fiberglass-reinforced plastic (FRP) boats, which are known for their durability and resistance to harsh marine conditions. Furthermore, its application in offshore structures, such as platforms and pipelines, underscores its superior corrosion resistance and durability, making it a vital material in the energy sector. In the chemical processing industry, vinyl ester’s exceptional chemical resistance allows it to effectively line tanks, pipes, and other equipment, protecting them from corrosive substances. This capability makes it suitable for high-performance applications like flue gas desulfurization (FGD) systems, where durability and resistance to harsh chemicals are paramount. As emerging markets in the Asia-Pacific and Middle East regions witness rapid industrialization and infrastructure development, the demand for vinyl ester continues to rise, supported by innovations in product formulations and ongoing research into new applications across diverse industries, including automotive and aerospace.
Market Challenges Analysis
High Initial Costs and Limited Shelf Life
One of the primary challenges facing the vinyl ester market is the high initial cost associated with its production. The manufacturing process for vinyl ester is more complex and costly compared to alternative resins, such as polyester. This elevated cost can limit the adoption of vinyl ester in price-sensitive applications, where budget constraints are a significant consideration. For instance, a survey by the Chemical Industry Association highlighted that many small to medium-sized enterprises (SMEs) prefer polyester resins due to their lower cost, despite the superior performance of vinyl ester. Additionally, vinyl ester has a relatively short shelf life compared to other resins, leading to inventory management challenges and potential waste, particularly for smaller-scale users who may not have the resources to manage rapid turnover. The combination of high production costs and limited shelf life creates barriers that could hinder the broader acceptance of vinyl ester across various industries.
Competition from Alternatives and Supply Chain Challenges
The vinyl ester market also faces stiff competition from alternative materials, such as epoxy resins, which offer similar properties at a lower cost for certain applications. While vinyl ester often outperforms these alternatives in terms of chemical resistance and durability, the price differential can sway customers toward more affordable options. Furthermore, the vinyl ester industry is susceptible to supply chain disruptions, which can arise from natural disasters or geopolitical events. Such disruptions can lead to fluctuations in raw material prices and product availability, complicating the market landscape. Moreover, environmental concerns surrounding the production and disposal of vinyl ester persist, despite its overall reputation as an environmentally friendly option. Stricter environmental regulations may increase production costs and limit the use of certain raw materials, further impacting the market dynamics. Collectively, these challenges necessitate innovative strategies and adaptations within the industry to maintain competitiveness and ensure sustainable growth.
Market Segmentation Analysis:
By Type:
The vinyl ester market can be segmented by type into Bisphenol A Diglycidyl Ether (DGEBA), Epoxy Phenol Novolac (EPN), Brominated Fire Retardant, and others. Among these, DGEBA is widely utilized due to its superior mechanical properties and chemical resistance, making it ideal for demanding applications in construction and infrastructure. EPN also holds a significant share, as it provides enhanced thermal stability and is favored in high-performance coatings and electrical applications. Brominated fire retardants are increasingly being incorporated into vinyl ester formulations to meet stringent fire safety regulations, particularly in marine and transportation sectors. The "Others" category includes various specialized formulations tailored to meet specific industry needs, further contributing to the market’s diversity. This segmentation allows manufacturers to target specific applications effectively, fostering innovation and product development that cater to evolving customer demands and regulatory requirements. As the market matures, the focus on creating advanced vinyl ester formulations will likely drive further segmentation, optimizing performance across a range of applications.
By Application:
In terms of application, the vinyl ester market is segmented into Pipes & Tanks, Paints & Coatings, Transportation, Pulp & Paper, and others. The Pipes & Tanks segment dominates the market, driven by the material’s excellent corrosion resistance and durability, making it an ideal choice for chemical processing and water treatment applications. The Paints & Coatings segment is also significant, as vinyl esters are employed in high-performance coatings that require superior adhesion and resistance to environmental degradation. In the Transportation sector, vinyl ester's lightweight and strong properties make it suitable for manufacturing components in automotive and aerospace applications. The Pulp & Paper segment utilizes vinyl ester for its chemical resistance, particularly in coatings and protective linings. Other applications encompass diverse uses across industries, including construction and marine. As the demand for high-performance materials continues to rise, vinyl ester’s versatility in various applications will play a critical role in driving market growth and expanding its footprint in existing and emerging sectors.
Segments:
Based on Type:
- Bisphenol A Diglycidyl Ether (DGEBA)
- Epoxy Phenol Novolac (EPN)
- Brominated Fire Retardant
- Others
Based on Application:
- Pipes & Tanks
- Paints & Coatings
- Transportation
- Pulp & Paper
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the vinyl ester market, accounting for approximately 30% of the global market. The region's growth is primarily driven by the robust demand from key industries, including construction, marine, and oil and gas. The presence of advanced manufacturing facilities and a well-established infrastructure further bolsters the market. The increasing focus on renewable energy projects, particularly wind energy, is also propelling the demand for vinyl ester composites in the production of wind turbine blades. Moreover, stringent environmental regulations are encouraging industries to adopt durable and corrosion-resistant materials, reinforcing vinyl ester’s appeal. With continued investment in infrastructure development and an expanding marine industry, North America is expected to maintain its strong market position in the coming years.
Asia-Pacific
The Asia-Pacific region is witnessing rapid growth in the vinyl ester market, projected to capture around 25% of the global share. This surge is largely attributed to the region’s ongoing industrialization and urbanization, driving demand across various sectors, including construction and transportation. Countries like China and India are at the forefront, with substantial investments in infrastructure projects and a booming manufacturing base. The increasing adoption of vinyl ester in renewable energy applications, particularly in solar panel and wind turbine production, further contributes to the market’s expansion. Additionally, the region’s growing awareness of the importance of high-performance materials for environmental sustainability is pushing manufacturers to integrate vinyl ester into their product offerings. As these trends continue to evolve, the Asia-Pacific region is poised for significant growth, enhancing its competitive stance in the global vinyl ester market.
Key Player Analysis
- AOC (US)
- DIC Corporation (Japan)
- SWANCOR (Taiwan)
- Hexion Inc. (US)
- INEOS Composites (US)
- BUFA Composites (Germany)
- Reichhold LLC (US)
- Allnex GmbH (Germany)
- Sino Polymer Co., Ltd. (China)
- Polynt S.p.A. (Italy)
- Resonac Holdings Corporation (Japan)
- Scott Bader Company Ltd. (UK)
- Interplastic Corporation (US)
- Poliya (Turkey)
- Nivitex Fibreglass & Resins (South Africa)
Competitive Analysis
The competitive landscape of the vinyl ester market is characterized by several leading players, including INEOS Composites, AOC, Polynt S.p.A., SWANCOR, Interplastic Corporation, Sino Polymer Co., Ltd., Resonac Holdings Corporation, Reichhold LLC, Allnex GmbH, Scott Bader Company Ltd., Hexion Inc., DIC Corporation, Poliya, and Nivitex Fibreglass & Resins. These companies compete on various fronts, including product quality, pricing, and technological innovation. Key players emphasize sustainable practices and advanced formulations to meet evolving customer demands, particularly in industries such as construction, marine, and renewable energy. The focus on expanding production capacities and developing innovative applications is increasingly important, especially in the rapidly growing Asia-Pacific region. As competition intensifies, companies are investing in research and development to enhance their product offerings and improve performance characteristics. This dynamic environment ensures that the vinyl ester market remains competitive, with firms striving to differentiate themselves through innovation and responsiveness to market trends.
Recent Developments
- In April 2023, AOC and BÜFA Composite Systems signed an agreement that targeted to expand their distribution in Southeast Europe through Büfa Composites Austria. Customers in the region will receive better service with various high-quality formulations, gelcoats, and auxiliary materials.
- In April 2023, BÜFA Composite Systems acquired the composite division from Joh. Klinglhuber & Söhne Handelsgesellschaft mbH. This constituted a strategic purchase by Büfa Composites to significantly raise its presence and visibility throughout the Austrian domestic market and wider Eastern Europe.
- In December 2023, Scott Bader Company Ltd and Bodotex entered into an agreement giving Bodotex the right and authority to control different product lines of distribution processes, composite materials, functional polymer solutions, and structural adhesive products. Geographically, this agreement is targeted at two different regions, South Africa and Denmark.
- In June 2024, Scott Bader established a fully independent operational presence in Brazil. This will come a decade after a long, ongoing joint venture with NOVAPOL PLÁSTICOS LTDA, a subsidiary operating under the umbrella of GRUPO IMSA S.A.
- In March 2022, The Mahad plant remained the only production facility that supplied to manufacturing units of Allnex GmbH. The company acquired the Coating Resins Business from D.R. Coats Ink & Resins Pvt. Ltd.
Market Concentration & Characteristics
The vinyl ester market exhibits moderate concentration, with several key players dominating production and distribution. These companies leverage their established market presence, extensive product portfolios, and advanced manufacturing capabilities to maintain competitive advantages. Market characteristics include a strong emphasis on innovation, as manufacturers invest in research and development to create high-performance formulations tailored to specific applications. The demand for sustainable and environmentally friendly materials has led to an increasing focus on developing vinyl ester products with reduced environmental impact. Additionally, the market is characterized by a diverse range of applications, spanning construction, marine, and renewable energy sectors, which further drives growth. Regional dynamics play a crucial role, with North America and Asia-Pacific emerging as key markets due to their industrial activities and infrastructure development. Overall, the vinyl ester market is evolving, with companies continually adapting to meet changing consumer preferences and regulatory requirements while enhancing product performance and sustainability.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The vinyl ester market is projected to experience steady growth, driven by increasing demand in construction and infrastructure sectors.
- Advancements in manufacturing technologies will enhance product quality and performance, making vinyl ester more competitive.
- Rising environmental concerns will lead to a greater emphasis on sustainable and eco-friendly formulations.
- The expansion of the renewable energy sector will boost demand for vinyl ester in applications like wind turbine blades and solar panel frames.
- Growing industrialization in emerging markets, particularly in Asia-Pacific, will create new opportunities for vinyl ester products.
- Companies will increasingly invest in research and development to innovate and diversify their product offerings.
- Strategic partnerships and collaborations among industry players will facilitate market expansion and technological advancements.
- The trend towards lightweight materials in transportation will drive further adoption of vinyl ester in automotive and aerospace applications.
- Increased focus on regulatory compliance will prompt manufacturers to develop products that meet stringent environmental standards.
- Overall, the vinyl ester market is poised for resilience and adaptability amid changing industry dynamics and consumer preferences.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the size of Vinyl Ester Market?
What factors are driving the growth of the Vinyl Ester market?
What are the key segments within the Vinyl Ester market?
Who are the major players in this Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Vinyl Ester Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Vinyl Ester Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,325 million → 2032: USD 2,095.96 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Vinyl Ester Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Vinyl Ester Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Vinyl Ester Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Vinyl Ester Market Drivers
- 3.3 Vinyl Ester Market Restraints & Challenges
- 3.4 Vinyl Ester Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Vinyl Ester Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Vinyl Ester Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Vinyl Ester category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Vinyl Ester Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Vinyl Ester Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Vinyl Ester market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Vinyl Ester Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Vinyl Ester Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Vinyl Ester Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Vinyl Ester (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Vinyl Ester Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Vinyl Ester Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Vinyl Ester Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Vinyl Ester Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Vinyl Ester Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Vinyl Ester Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Vinyl Ester Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Vinyl Ester Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Vinyl Ester Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
