
Market Overview:
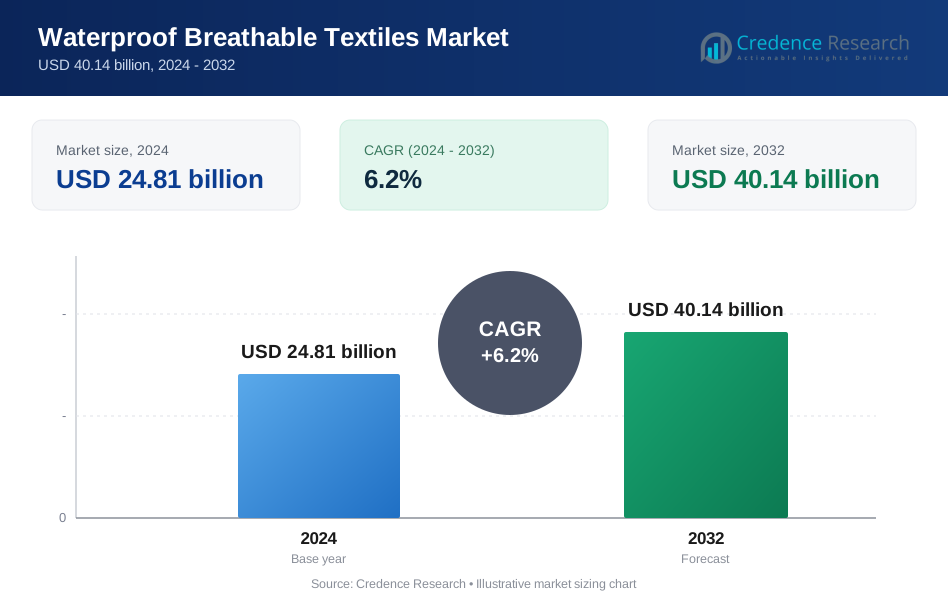
The Waterproof Breathable Textiles (WBT) market size was valued at USD 24.81 billion in 2024 and is anticipated to reach USD 40.14 billion by 2032, at a CAGR of 6.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Waterproof Breathable Textiles (WBT) market Size 2024 | USD 24.81 billion |
| Waterproof Breathable Textiles (WBT) market, CAGR | 6.2% |
| Waterproof Breathable Textiles (WBT) market Size 2032 | USD 40.14 billion |
The Waterproof Breathable Textiles (WBT) market is highly competitive, with key players including Gore-Tex, Patagonia, Mountain Hardwear, Helly Hansen, eVent Fabrics, Rudolf GmbH, Sympatex, Nextec Applications, Marmot Mountain LLC, HeiQ Materials AG, Jack Wolfskin Retail GmbH, Aclimatise, and Polartec, LLC driving innovation. These companies focus on developing advanced membranes, fluorine-free coatings, and sustainable fabrics to meet rising demand for performance apparel and protective clothing. North America leads the market with approximately 34% share in 2024, supported by strong outdoor recreation culture and strict industrial safety standards. Europe follows with 28% share, driven by high adoption of eco-friendly textiles and premium outdoor brands, while Asia-Pacific emerges as the fastest-growing region due to expanding middle-class populations and manufacturing capacity.

Market Insights
- The waterproof breathable textiles market was valued at USD 24.81 billion in 2024 and is projected to reach USD 40.14 billion by 2032, growing at a CAGR of 6.2%.
- Rising demand for outdoor apparel, sportswear, and protective clothing is a major driver, supported by growing disposable incomes and active lifestyle trends.
- Key trends include the shift toward fluorine-free and recycled materials, adoption of smart textiles, and investment in lightweight, high-performance membranes and laminates.
- The market is competitive, with global players focusing on product innovation, sustainability initiatives, and strategic collaborations with apparel brands to expand reach.
- North America led the market with 34% share, followed by Europe with 28%, while Asia-Pacific is the fastest-growing region; membrane textiles held the largest segment share at over 45% in 2024, driven by demand for high-performance outdoor gear and technical apparel across global markets.
Market Segmentation Analysis:
By Textile
Membrane textiles dominated the Waterproof Breathable Textiles (WBT) market in 2024, holding over 45% market share. Their superior waterproofing and breathability make them the preferred choice for high-performance outdoor gear and technical apparel. Membrane technology, such as microporous and monolithic structures, provides excellent moisture vapor transmission while maintaining durability under extreme conditions. Rising demand for premium sportswear and protective clothing drives adoption, especially in developed markets. Manufacturers are investing in advanced membrane laminates to enhance flexibility and eco-friendly performance, aligning with consumer expectations for sustainable and comfortable products.
- For instance, Xpore uses nanoporous membranes that are non-toxic and free of PFCs and solvents; their membrane has 10 billion nanopores per square inch.
By Material
ePTFE (expanded polytetrafluoroethylene) led the market with more than 40% share in 2024, driven by its excellent microporous structure and high durability. Its superior water resistance and breathability make it the material of choice for technical sportswear, military uniforms, and industrial protective gear. Polyurethane follows due to its cost-effectiveness and adaptability in coated fabrics. The growing demand for lightweight, high-performance textiles in outdoor apparel and footwear segments boosts ePTFE usage. Key players are innovating with fluorine-free alternatives to meet stringent environmental regulations and address consumer demand for sustainable material solutions.
- For instance, GORE-TEX produces membranes with about 9 billion pores per square inch, each pore about 20,000 times smaller than a raindrop and about 700 times larger than a water vapor molecule.
By Application
General Clothing & Accessories held the largest share, accounting for over 50% of the WBT market in 2024. Demand is fueled by increasing consumer preference for weather-resistant jackets, casual wear, and footwear with breathable comfort. The fashion industry’s focus on functionality combined with aesthetics accelerates the adoption of waterproof breathable fabrics in everyday apparel. Sports goods represent a fast-growing segment, supported by the rise in outdoor activities and athletic participation. Protective clothing applications also expand, driven by stricter safety regulations in industrial, defense, and healthcare sectors requiring performance-driven textile solutions.
Market Overview
Rising Outdoor and Sportswear Demand
The growing popularity of outdoor recreation, adventure tourism, and fitness activities is a key driver for the WBT market. Consumers are increasingly choosing high-performance jackets, shoes, and gear that offer all-weather protection and superior comfort. Sportswear brands are focusing on integrating waterproof breathable fabrics into their collections to meet customer expectations for durability and functionality. Rising disposable incomes in developing nations are fueling the purchase of premium apparel, while growing participation in global events like marathons and trekking expeditions continues to drive steady demand across multiple consumer segments.
- For instance, eVent Fabrics reports that specific membranes with its Direct Venting® technology, such as the DVAlpine, can achieve a high moisture vapor transmission rate (MVTR) of 20,000 g/m² over 24 hours, effectively keeping users drier during intense outdoor exercise.
Advancements in Textile Technology
Innovations in textile engineering are transforming the WBT market, making fabrics lighter, more flexible, and highly breathable. Manufacturers are investing in advanced membrane and laminate technologies that deliver improved moisture vapor transmission rates without compromising durability. The shift toward fluorine-free and solvent-free coatings is helping companies meet environmental regulations while appealing to eco-conscious consumers. Automated production techniques are reducing defects and increasing scalability, enabling cost-effective production of high-performance textiles that cater to both sportswear and protective apparel applications globally.
- For instance, a study of fluorine-free waterborne coatings achieved waterproofness of 9 kPa, breathability of 12.3 kg/m²/day, and tensile strength of 16.0 MPa in finished fibrous textiles.
Growing Safety and Protection Needs
The increasing need for reliable protective clothing across industries is another major growth driver. Workers in construction, oil & gas, chemical, and military sectors require garments with superior water resistance and comfort, pushing demand for WBT-based apparel. Government regulations mandating worker safety equipment, along with rising awareness about occupational hazards, are accelerating adoption. Additionally, healthcare facilities are using WBT in PPE and surgical gowns to provide both barrier protection and comfort. This broad application base across sectors strengthens market penetration and creates stable long-term growth opportunities.
Key Trends & Opportunities
Sustainable and Eco-Friendly Materials
A major trend shaping the WBT market is the shift toward sustainable and recyclable materials. Companies are developing PFC-free membranes, bio-based coatings, and recycled polyester fabrics to align with green standards and consumer expectations. Regulatory frameworks in Europe and North America are accelerating this transition by restricting harmful chemicals in textile production. Brands adopting circular economy initiatives and transparent supply chains are gaining a competitive advantage and strengthening their sustainability image, which appeals to a growing environmentally conscious consumer base worldwide.
- For instance, SMS (spunbond-meltblown-spunbond) materials used in medical protective clothing are tested to reach hydrostatic pressures greater than 50 cm of water column for ANSI/AAMI Level 3 protection.
Integration with Smart Textiles
The convergence of waterproof breathable technology with smart textiles is opening new market opportunities. Innovative products now combine moisture management with embedded sensors to track heart rate, temperature, and sweat levels in real time. These advancements are attracting demand from sports, defense, and healthcare sectors looking for data-driven performance apparel. The rise of wearable technology and IoT integration is further encouraging collaborations between textile manufacturers and electronics companies to create multifunctional, intelligent garments that provide both protection and valuable analytics.
- For instance, Ventile / Stotz & Co AG produces its Ventile Original fabric (100% cotton) with a hydrostatic head between 400 mm and 850 mm depending on variant.
Key Challenges
High Production Costs
One of the most pressing challenges in the WBT market is the high production cost of advanced fabrics. Manufacturing membranes and coatings requires specialized raw materials and precision processing, which drives up costs. The final product often carries a premium price, restricting its adoption in price-sensitive markets and among mass-market consumers. To overcome this challenge, companies are working on process optimization, economies of scale, and material innovations to bring down costs while maintaining performance standards.
Environmental Compliance and Regulations
Strict environmental regulations represent a key hurdle for manufacturers. The global phase-out of PFCs and other harmful substances in textile coatings requires heavy investment in research and development to find effective alternatives. Achieving compliance with diverse regional standards adds complexity and cost to operations. Non-compliance risks include product recalls, fines, and damage to brand reputation. As sustainability expectations rise, companies must adapt quickly while balancing profitability and innovation, which can strain resources and increase operational challenges.
Regional Analysis
North America
North America held the largest share of the waterproof breathable textiles (WBT) market in 2024, accounting for around 34% of global revenue. The region benefits from strong demand for outdoor apparel, sportswear, and protective clothing driven by a well-developed activewear culture. High participation in activities such as hiking, skiing, and camping boosts consumption of high-performance fabrics. Stringent workplace safety regulations further support adoption in industrial and protective applications. Leading brands and innovations from the U.S. contribute to market growth. Rising preference for sustainable and fluorine-free materials also drives investments in advanced textile technologies across the region.
Europe
Europe accounted for approximately 28% share of the global WBT market in 2024, driven by growing demand for sustainable and high-quality apparel. The region is a hub for luxury outdoor and sportswear brands, which consistently integrate advanced membrane and coated textiles. Strong regulatory focus on eco-friendly and PFC-free materials encourages manufacturers to invest in greener production methods. Increasing popularity of adventure tourism and sports like mountaineering and cycling enhances demand. Industrial and military sectors also contribute significantly, with stringent worker safety standards supporting adoption of waterproof breathable clothing across multiple European markets.
Asia-Pacific
Asia-Pacific captured around 25% share of the WBT market in 2024 and is projected to be the fastest-growing region during the forecast period. Expanding middle-class population and rising disposable incomes are fueling demand for premium sportswear and outdoor apparel. Countries like China, Japan, and South Korea are leading producers and consumers, supported by strong textile manufacturing infrastructure. Rapid urbanization and increasing participation in recreational activities also drive consumption. Local brands are focusing on offering affordable yet high-performance waterproof breathable products, while global players expand manufacturing operations in the region to meet growing demand efficiently.
Latin America
Latin America accounted for nearly 7% of the global WBT market share in 2024, supported by rising demand for affordable sportswear and outdoor clothing. Brazil and Mexico are the key markets, with increasing interest in hiking, running, and fitness activities driving consumption. Growth of the textile and apparel manufacturing sector supports local availability of performance fabrics. Rising investments from international brands are helping expand product penetration. However, market growth remains moderate compared to Asia-Pacific and North America due to economic fluctuations, though opportunities remain significant as disposable incomes and lifestyle-oriented purchases continue to rise.
Middle East & Africa
The Middle East & Africa held about 6% share of the global WBT market in 2024, characterized by gradual but steady growth. Rising focus on protective workwear in oil & gas, mining, and construction sectors is a key driver. Sportswear adoption is increasing, especially in urban centers of Gulf countries where active lifestyle trends are growing. Import reliance remains high, but local manufacturing capacity is expanding to meet demand. Government initiatives promoting worker safety and tourism activities such as desert trekking and adventure sports are expected to boost the adoption of waterproof breathable fabrics in coming years.
Market Segmentations:
By Textile:
- Densely Woven
- Membrane
- Coated
By Material:
- ePTFE
- Polyurethane
- Polyester
- Others
By Application:
- General Clothing & Accessories
- Sports Goods
- Protective Clothing
By Geography:
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Latin America
- Brazil
- Argentina
- Chile
- Rest of Latin America
- Middle East & Africa
- United Arab Emirates
- South Africa
- Saudi Arabia
- Egypt
- Rest of Middle East & Africa
Competitive Landscape
The competitive landscape of the Waterproof Breathable Textiles (WBT) market is shaped by leading players such as Gore-Tex, Patagonia, Mountain Hardwear, Helly Hansen, eVent Fabrics, Rudolf GmbH, Sympatex, Nextec Applications, Marmot Mountain LLC, HeiQ Materials AG, Jack Wolfskin Retail GmbH, Aclimatise, and Polartec, LLC. The market is characterized by strong innovation, with companies focusing on advanced membrane technology, lightweight laminates, and sustainable coatings to enhance product performance. Research and development efforts emphasize fluorine-free and recycled materials to meet strict environmental standards. Strategic collaborations with apparel and footwear brands support product differentiation and expand market reach. Manufacturers are also adopting automated production processes to improve scalability and cost efficiency. Marketing strategies focus on highlighting comfort, breathability, and eco-friendly features to attract performance-oriented and sustainability-driven consumers. Intense competition encourages continuous product launches and material innovations to maintain leadership in this rapidly evolving performance textile industry.
Key Player Analysis
- Gore-Tex
- Patagonia
- Mountain Hardwear
- Helly Hansen
- eVent Fabrics
- Rudolf GmbH
- Sympatex
- Nextec Applications
- Marmot Mountain LLC.
- HeiQ Materials AG
- Jack Wolfskin Retail GmbH
- Aclimatise
- Polartec, LLC
Recent Developments
- In 2025, Sympatex was working toward its climate-neutrality and circularity goals, sharing updates on its progress and market offerings, and continuing its activism against PTFE and PFAS.
- In 2025, Patagonia had fully transitioned its new products, including its H₂No Performance Standard outerwear, to be made without intentionally added PFAS.
- In 2023, Gore-Tex launched a brand campaign emphasizing its commitment to innovation and responsible performance, highlighting the durability and features of new products with the ePE membrane.
Report Coverage
The research report offers an in-depth analysis based on Textile, Material, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow steadily driven by rising demand for outdoor and sportswear apparel.
- Technological advancements will enhance fabric breathability, durability, and eco-friendly performance.
- Adoption of fluorine-free and recycled materials will become a key manufacturing focus.
- Increasing urbanization and lifestyle changes will boost premium apparel consumption globally.
- Protective clothing demand from industrial and healthcare sectors will continue to rise.
- Asia-Pacific will emerge as the fastest-growing regional market during the forecast period.
- Smart textile integration will create opportunities for connected and data-driven garments.
- Companies will invest in automation to lower production costs and improve scalability.
- Partnerships between apparel brands and fabric innovators will accelerate product launches.
- Regulatory compliance and sustainability initiatives will shape competitive strategies worldwide.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Waterproof Breathable Textiles (WBT) Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Waterproof Breathable Textiles (WBT) Market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Waterproof Breathable Textiles (WBT) Market?
Who are the leading companies in the Waterproof Breathable Textiles (WBT) Market?
Which region commanded the largest share of the Waterproof Breathable Textiles (WBT) Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Waterproof Breathable Textiles Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Waterproof Breathable Textiles Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 24.81 billion → 2032: USD 40.14 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Waterproof Breathable Textiles Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Waterproof Breathable Textiles Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Waterproof Breathable Textiles Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Waterproof Breathable Textiles Market Drivers
- 3.3 Waterproof Breathable Textiles Market Restraints & Challenges
- 3.4 Waterproof Breathable Textiles Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Waterproof Breathable Textiles Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Waterproof Breathable Textiles Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Waterproof Breathable Textiles category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Waterproof Breathable Textiles Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Waterproof Breathable Textiles Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Waterproof Breathable Textiles market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Waterproof Breathable Textiles Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Waterproof Breathable Textiles Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Waterproof Breathable Textiles Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Waterproof Breathable Textiles (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Waterproof Breathable Textiles Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Waterproof Breathable Textiles Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Waterproof Breathable Textiles Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Waterproof Breathable Textiles Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Waterproof Breathable Textiles Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Waterproof Breathable Textiles Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Waterproof Breathable Textiles Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Waterproof Breathable Textiles Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Waterproof Breathable Textiles Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
