
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Wheel Spinning Machines Market Size 2024 | USD 1224 million |
| Wheel Spinning Machines Market, CAGR | 5.57% |
| Wheel Spinning Machines Market Size 2032 | USD 1888.45 million |
Market Overview:
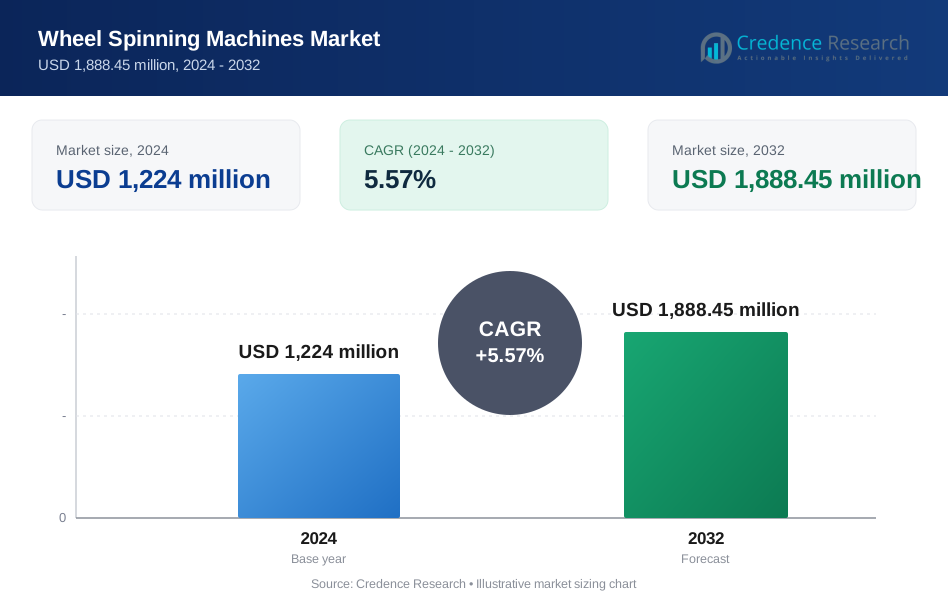
The Wheel Spinning Machines Market is projected to grow from USD 1224 million in 2024 to an estimated USD 1888.45 million by 2032, with a compound annual growth rate (CAGR) of 5.57% from 2024 to 2032.
Multiple factors drive investment in wheel spinning technologies. First, the automotive and aerospace industries propel demand for lightweight, high-strength components such as aluminum wheels and aircraft structural parts, which spin-forming processes efficiently produce. Manufacturers turn to these machines to realize weight reduction, superior fatigue resistance, and enhanced surface finishes key requirements in performance-driven applications. Second, ongoing integration of automation, artificial intelligence, and Industry 4.0 practices into manufacturing systems increases production output, consistency, and predictive maintenance, raising the attractiveness of these machines. Third, environmental and energy efficiency concerns receive mounting focus. Spin forming enables material savings and reduces waste, enabling companies to advance sustainability initiatives and cost-cutting goals. As fabrication standards tighten, the market gains additional momentum from technical advancements such as multi-axis controls, sensor-based feedback loops, and modular machine designs.
North America currently leads growth in the wheel spinning machines market, driven by its mature automotive and aerospace sectors, high R&D investment, and early adoption of Industry 4.0 technologies. The United States stands as the primary regional market, underpinned by continued demand for lightweightwheel rims, structural components, and defense-grade assemblies. Europe follows closely, supported by strong automotive OEM presence in Germany, Italy, and France and robust aerospace production in the UK and France. Meanwhile, the Asia-Pacific region exhibits the fastest growth trajectory, fueled by rapidly expanding vehicle production in China and India, growing aviation infrastructure, and government-led manufacturing modernization. Economies across Southeast Asia also experience rising industrialization. Latin America, the Middle East, and Africa trail in absolute volumes but show increasing investment in specialized manufacturing capacity in countries such as Brazil, Mexico, and the UAE.
Market Insights:
- The Wheel Spinning Machines Market is projected to grow from USD 1,224 million in 2024 to USD 1,888.45 million by 2032, registering a CAGR of 5.57%.
- Rising demand for lightweight and high-strength components in automotive and aerospace industries drives significant investment in spin-forming technologies.
- Integration of Industry 4.0 tools-such as IoT, automation, and predictive analytics-enhances efficiency, uptime, and product consistency in forming operations.
- Sustainability pressures encourage adoption of spin-forming machines, which reduce material waste and energy use compared to traditional methods.
- High upfront costs and integration challenges hinder adoption among small- and medium-sized enterprises, requiring clearer ROI justification.
- Skilled labor shortages and complex maintenance requirements limit machine utilization and demand stronger training and after-sales support.
- North America leads the market with a 32% share, while Asia Pacific exhibits the fastest growth due to industrial expansion in China and India.
Market Drivers:
Surging Demand for Lightweight and High-Strength Components in Automotive and Aerospace Industries
The automotive and aerospace sectors continue to drive the need for advanced forming technologies capable of producing lightweight yet structurally robust components. Manufacturers increasingly adopt spin forming to produce precision rims, structural housings, and engine components with minimal material waste. These machines enable the shaping of high-strength alloys such as aluminum and titanium, which are essential for weight reduction and fuel efficiency in vehicles and aircraft. OEMs and Tier 1 suppliers value the ability to maintain tight tolerances and high repeatability without compromising structural integrity. The Wheel Spinning Machines Market benefits from the growing preference for metal forming over casting or welding, which often requires post-processing. It remains a preferred solution for critical applications that demand reliability and mechanical strength.
- For example, Aero Race Wheels Inc., a major U.S. racecar wheel supplier, uses spin forming on CNC lathes to manufacture steel wheels for NASCAR, IMCA, and WISSOTA events, producing hundreds of wheels daily.
Integration of Industry 4.0 Technologies to Optimize Manufacturing Efficiency
Smart manufacturing initiatives accelerate the adoption of automated and sensor-driven spinning machines. Embedded control systems and IoT connectivity now enable real-time process monitoring, remote diagnostics, and predictive maintenance, which reduce downtime and boost productivity. Factories are investing in CNC-based spinning machines equipped with multi-axis control, enabling complex geometries to be formed with precision. It supports production scalability and shortens lead times, especially in mass manufacturing environments. The Wheel Spinning Machines Market aligns with the global shift toward digitalized manufacturing, where precision and efficiency play a central role. It appeals to manufacturers aiming to enhance competitiveness through process optimization.
Focus on Sustainability and Resource-Efficient Manufacturing
Environmental mandates and sustainability goals compel industries to minimize material waste and energy consumption during production. Spin forming techniques offer high material utilization rates by reshaping metal blanks without removing excess material. This process also lowers energy usage compared to conventional machining or forging, which involve substantial heat and material loss. Manufacturers use this advantage to align with corporate sustainability objectives while improving cost-efficiency. The Wheel Spinning Machines Market supports low-carbon manufacturing initiatives by reducing the environmental footprint of metal forming operations. It remains a strategic choice for companies seeking eco-efficient production capabilities.
- For instance, LEIFELD’s WSC Flex technology reports a significant reduction in CO₂ emissions through energy-saving measures such as recuperation on main drives, while eliminating tooling costs and setup times, further supporting lean and eco-efficient manufacturing.
Expansion of End-Use Industries and Customized Production Requirements
Diversified applications across transportation, defense, medical, and energy sectors generate fresh demand for precision-formed metal components. Each of these sectors requires parts with unique geometries, wall thicknesses, and material properties, which spin forming can achieve consistently. Small- and mid-sized manufacturers now pursue customized machine configurations to support niche production needs. These machines enable batch flexibility without extensive tooling changes, making them ideal for low- to medium-volume production. The Wheel Spinning Machines Market continues to benefit from growing demand for tailored solutions that address specific performance, design, and production goals. It plays a pivotal role in enabling flexible, high-precision fabrication across evolving industrial landscapes.
Market Trends:
Growing Adoption of CNC-Based and Multi-Axis Spinning Machines
Manufacturers increasingly favor CNC-based spinning machines for their precision, repeatability, and ease of integration into automated production lines. These systems use programmable logic controllers and multi-axis controls to produce complex geometries with minimal manual intervention. Multi-axis configurations allow for the formation of intricate contours and variable wall thicknesses, which traditional lathes or manual systems cannot achieve efficiently. The Wheel Spinning Machines Market reflects this shift toward high-tech configurations that improve throughput while maintaining strict quality standards. It supports modern manufacturing environments that prioritize speed, flexibility, and digital control. This trend reinforces the role of advanced forming machinery in smart factory initiatives.
Increasing Preference for Hybrid and Modular Machine Designs
Manufacturers show strong interest in hybrid machines that combine spinning with other forming processes such as shear forming or flow forming. This integration enhances versatility, enabling the same equipment to produce a broader range of components. Modular machine designs also gain popularity, allowing users to reconfigure or upgrade existing systems based on changing production needs. The market responds with customizable platforms that offer flexibility without sacrificing performance or durability. The Wheel Spinning Machines Market benefits from the demand for adaptable equipment that supports evolving product portfolios. It meets the requirements of both large-scale OEMs and small job shops seeking long-term value.
Rising Focus on Automation and Process Monitoring for Quality Assurance
Quality control and process traceability now take precedence across industries such as automotive, aerospace, and energy. Manufacturers increasingly integrate advanced sensors, vision systems, and feedback loops into spinning machines to monitor force, temperature, and material behavior during forming. These technologies ensure consistent output and reduce the risk of defects, which improves overall manufacturing efficiency. The Wheel Spinning Machines Market aligns with this trend by incorporating embedded systems that support real-time data collection and analytics. It enables smarter decision-making and tighter control over product specifications. This focus on automation drives both operational excellence and customer satisfaction.
- For instance, Aero Race Wheels Inc. has implemented NUM CNC controls with automated program generation and real-time monitoring, which significantly reduces changeover times and improves process control and quality assurance.
Expansion into Niche Applications and Emerging Geographies
Demand for precision spinning technology extends beyond traditional sectors into emerging areas such as medical devices, renewable energy systems, and defense-grade components. These applications require exacting standards and benefit from the precision, repeatability, and material efficiency of spinning machines. Growth is also evident in developing economies where manufacturing capabilities continue to scale, especially in Southeast Asia, Latin America, and parts of Eastern Europe. The Wheel Spinning Machines Market experiences growth in both established and emerging regions, driven by increased industrialization and the pursuit of advanced forming technologies. It remains positioned to address a broadening range of technical and geographic opportunities.
- For instance, Rieter’s textile spinning systems process bast fibers like flax and hemp, aligning with sustainability goals and supporting circular economy initiatives in regions like Eastern Europe.
Market Challenges Analysis:
High Initial Investment and Complex Integration Requirements
The high cost of advanced wheel spinning machines remains a significant barrier for small- and medium-sized enterprises. CNC-based multi-axis systems, integrated with automation and sensors, demand substantial upfront capital, which limits accessibility for businesses with constrained budgets. Integration with existing production infrastructure also presents challenges, especially when legacy systems lack compatibility with modern controls and software. Manufacturers must allocate resources for specialized training, machine calibration, and digital synchronization, which can extend implementation timelines. The Wheel Spinning Machines Market faces hesitation from buyers wary of long ROI periods and operational disruption. It needs clear value demonstrations to overcome financial concerns and adoption delays.
Skilled Labor Shortages and Maintenance Complexity
Operating advanced spinning machinery requires a skilled workforce familiar with CNC programming, material science, and digital monitoring systems. However, the shortage of trained technicians and machine operators across many regions slows machine utilization and output quality. Maintenance complexity adds another layer of difficulty, with multi-axis systems requiring precise calibration and part replacements to maintain performance. Errors in tooling alignment or sensor integration can lead to costly downtime or product defects. The Wheel Spinning Machines Market must address this challenge through improved training programs and simplified user interfaces. It must also deliver robust service support to ensure consistent operation across diverse industrial environments.
Market Opportunities:
Emergence of Electric Vehicles and Lightweight Mobility Solutions
The global shift toward electric vehicles (EVs) creates a growing demand for lightweight, high-strength components such as alloy wheels, battery casings, and structural supports. Manufacturers seek advanced forming methods to reduce component weight without compromising durability or safety. The Wheel Spinning Machines Market stands to gain from this trend by offering precision forming capabilities that align with EV manufacturing requirements. It supports the production of aerodynamic, performance-optimized parts that meet regulatory standards for efficiency. With many OEMs investing in localized EV production, machine suppliers can capitalize on rising regional procurement needs. This trend opens new channels across Asia-Pacific, Europe, and North America.
Adoption in Emerging Sectors and Custom Production Applications
New industries such as renewable energy, defense, and medical equipment increasingly require complex metal components with tight tolerances and consistent quality. These sectors present strong opportunities for machine manufacturers offering specialized configurations and rapid prototyping capabilities. The Wheel Spinning Machines Market can address the demand for small-batch, customized parts where traditional casting or forging methods fall short. It enables flexible production while reducing material waste and processing time. Growth in additive manufacturing and hybrid forming systems further broadens the application scope. Suppliers that align solutions with niche technical requirements will capture untapped revenue streams in high-value industrial segments.
Market Segmentation Analysis:
The Wheel Spinning Machines Market demonstrates varied adoption across different machine configurations.
By types, three roller machines dominate the segment due to their balanced control, cost-effectiveness, and ability to handle standard wheel forming tasks with efficiency. These systems suit small- to mid-volume production and offer solid flexibility for different wheel sizes. Four roller machines hold a significant share in high-precision manufacturing environments, especially where complex rim geometries and tighter tolerances are required. Their additional support and stability enhance forming accuracy and reduce material stress, making them ideal for demanding applications. The others category, which includes hybrid and custom designs, serves niche applications and continues to attract interest for specialized production needs.
- For instance, Saar Maschinenbau GmbH has been acknowledged for its precision four-roller machines used in high-precision manufacturing environments. These systems are especially valuable in the aerospace industry, where the production of complex wheel geometries is essential.
By application, aluminum wheel manufacturing leads the market due to rising demand for lightweight wheels in automotive and aerospace sectors. Spin forming enhances the strength-to-weight ratio of aluminum components, supporting fuel efficiency and performance. The steel wheel segment maintains steady demand, particularly in heavy-duty vehicles and cost-sensitive markets, where durability and load-bearing capacity remain priorities. The Wheel Spinning Machines Market supports both material types by offering precision, material efficiency, and scalable production capabilities.
- For the steel wheel market, Rösler has reported a consistent demand for their machines in heavy-duty commercial vehicle manufacturing. Their systems are built to provide durability and cost-efficiency, ensuring that steel wheels continue to meet the rigorous demands of sectors such as transportation and construction, where high load-bearing capacity is a priority.
Segmentation:
By Type
- Three Roller
- Four Roller
- Others
By Application
- Steel Wheel
- Aluminum Wheel
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America Leads with Advanced Manufacturing Ecosystems North America holds the largest share of the global Wheel Spinning Machines Market, accounting for 32% of total revenue. Strong demand from the automotive and aerospace sectors, particularly in the United States, continues to drive growth. Manufacturers in this region prioritize high-precision forming technologies to meet strict regulatory and performance standards. The integration of Industry 4.0 practices and smart factory models further supports the adoption of CNC-based and sensor-enabled spinning machines. Investments in defense and electric vehicle production also contribute to equipment modernization across manufacturing lines. The Wheel Spinning Machines Market benefits from well-established supply chains, skilled labor, and technological leadership across North America.
Europe Maintains Steady Growth through Automotive and Aerospace Hubs Europe contributes around 27% to the global market, with countries like Germany, France, and the UK serving as major hubs for automotive and aerospace production. Leading OEMs and Tier 1 suppliers invest in advanced metal-forming technologies to align with emission norms, lightweighting strategies, and competitive production timelines. The region also benefits from strong R&D ecosystems that support process innovation and machine development. Manufacturers deploy wheel spinning machines to fabricate precision parts for electric drivetrains, aircraft fuselage components, and defense-grade assemblies. The Wheel Spinning Machines Market in Europe remains driven by sustainability goals, skilled engineering capabilities, and consistent export demand across mechanical sectors.
Asia Pacific Emerges as the Fastest-Growing Regional Market Asia Pacific holds a 23% share of the global market but exhibits the highest growth rate, driven by rapid industrialization and expanding automotive production. China, India, and Japan lead regional demand, supported by rising investments in EV manufacturing, infrastructure development, and aerospace capabilities. Governments across the region promote localized production through favorable policies and subsidies, encouraging adoption of advanced forming equipment. Manufacturers in Southeast Asia also invest in wheel spinning machines to support domestic demand and export-oriented industries. The Wheel Spinning Machines Market in Asia Pacific gains momentum through capacity expansion, technological upgrades, and the growing presence of global equipment suppliers. It is expected to outpace other regions in absolute growth over the forecast period.
Key Player Analysis:
- LMW Limited
- Industrias Puigjaner (DENN)
- Leifeld Metal Spinning
- Nova Sidera
- Grotnes
- Guangdong Prosper
- MJC Engineering and Technology
- Daitoh Spinning
- Repkon Machine
- Abacus Maschinenbau
- Quanzhou Taida
- Ernst Grob
- Nihon Spindle Manufacturing
Competitive Analysis:
The Wheel Spinning Machines Market features a moderately consolidated landscape, led by established players focused on precision engineering, automation integration, and global service support. Key companies such as Leifeld Metal Spinning, MJC Engineering & Technology, Inc., and DENN are known for their technologically advanced machines and strong R&D capabilities. These firms invest in CNC and multi-axis system innovations to meet evolving industry demands. Regional manufacturers from Asia Pacific, including suppliers from China and Japan, continue to gain share through cost-effective solutions and strategic partnerships. The market sees growing competition in customized machine configurations tailored for specific end-use industries. It remains driven by product differentiation, after-sales service, and the ability to deliver turnkey solutions. Global players sustain competitiveness through geographic expansion, while smaller firms focus on niche applications and flexible machine offerings. The Wheel Spinning Machines Market rewards companies that align technical performance with evolving user expectations and advanced manufacturing standards.
Recent Developments:
- In July 2024, LMW Textile Machinery Division introduced an innovative fully automated yarn piecing device called the Ring Frame Auto Piecer (RAP) for Ring spinning machines. This new product automates the piecing process, which was previously performed manually by specialized personnel, significantly boosting productivity and quality in the spinning industry.
- In January 2025, LMW Limited (Lakshmi Machine Works Limited) unveiled a new lineup of advanced CNC machines at IMTEX 2025. These innovations include new turning, milling, and turnmill centers, as well as automation solutions like the Flexzy Bot and IoT-enabled production monitoring systems, all aimed at enhancing productivity, precision, and efficiency for industries such as automotive and general engineering.
Market Concentration & Characteristics:
The Wheel Spinning Machines Market exhibits moderate market concentration, with a handful of global players controlling a significant portion of total revenue. It features high entry barriers due to the capital-intensive nature of advanced machine manufacturing and the specialized technical expertise required. The market is characterized by continuous innovation, a strong emphasis on precision engineering, and rising demand for automation and digital integration. Customization, energy efficiency, and multi-functionality define purchasing preferences, especially across automotive and aerospace sectors. It demonstrates a balance between standardized equipment for mass production and tailored solutions for niche applications. The Wheel Spinning Machines Market favors firms with robust R&D capabilities, comprehensive after-sales support, and the ability to adapt to evolving manufacturing technologies and end-user requirements.
Report Coverage:
The research report offers an in-depth analysis based on Type and Application It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for lightweight vehicle components will continue to drive machine adoption across automotive manufacturing.
- Integration of Industry 4.0 features such as IoT sensors and AI-based monitoring will become standard in new systems.
- Electric vehicle production expansion will create sustained opportunities for precision wheel forming solutions.
- Manufacturers will invest in energy-efficient machines to meet environmental regulations and reduce operational costs.
- Customizable and modular machine designs will gain traction among mid-sized and specialized producers.
- Growth in Asia Pacific will outpace other regions due to industrialization, infrastructure growth, and local sourcing policies.
- Adoption of spinning machines in aerospace and defense sectors will rise due to complex geometry and performance needs.
- Niche markets like medical equipment and renewable energy will seek compact, high-accuracy machines for specialized parts.
- Global players will focus on strategic partnerships and localized service centers to strengthen regional presence.
- Technological advancements in tooling and control systems will enhance machine versatility and long-term market competitiveness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Wheel Spinning Machines Market?
What factors are driving the growth of the Wheel Spinning Machines Market?
What are some challenges faced by the Wheel Spinning Machines Market?
Who are the major players in the Wheel Spinning Machines Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Wheel Spinning Machines Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Wheel Spinning Machines Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,224 million → 2032: USD 1,888.45 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Wheel Spinning Machines Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Wheel Spinning Machines Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Wheel Spinning Machines Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Wheel Spinning Machines Market Drivers
- 3.3 Wheel Spinning Machines Market Restraints & Challenges
- 3.4 Wheel Spinning Machines Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Wheel Spinning Machines Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Wheel Spinning Machines Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Wheel Spinning Machines category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Wheel Spinning Machines Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Wheel Spinning Machines Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Wheel Spinning Machines market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Wheel Spinning Machines Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Wheel Spinning Machines Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Wheel Spinning Machines Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Wheel Spinning Machines (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Wheel Spinning Machines Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Wheel Spinning Machines Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Wheel Spinning Machines Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Wheel Spinning Machines Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Wheel Spinning Machines Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Wheel Spinning Machines Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Wheel Spinning Machines Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Wheel Spinning Machines Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Wheel Spinning Machines Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
