
Market Overview
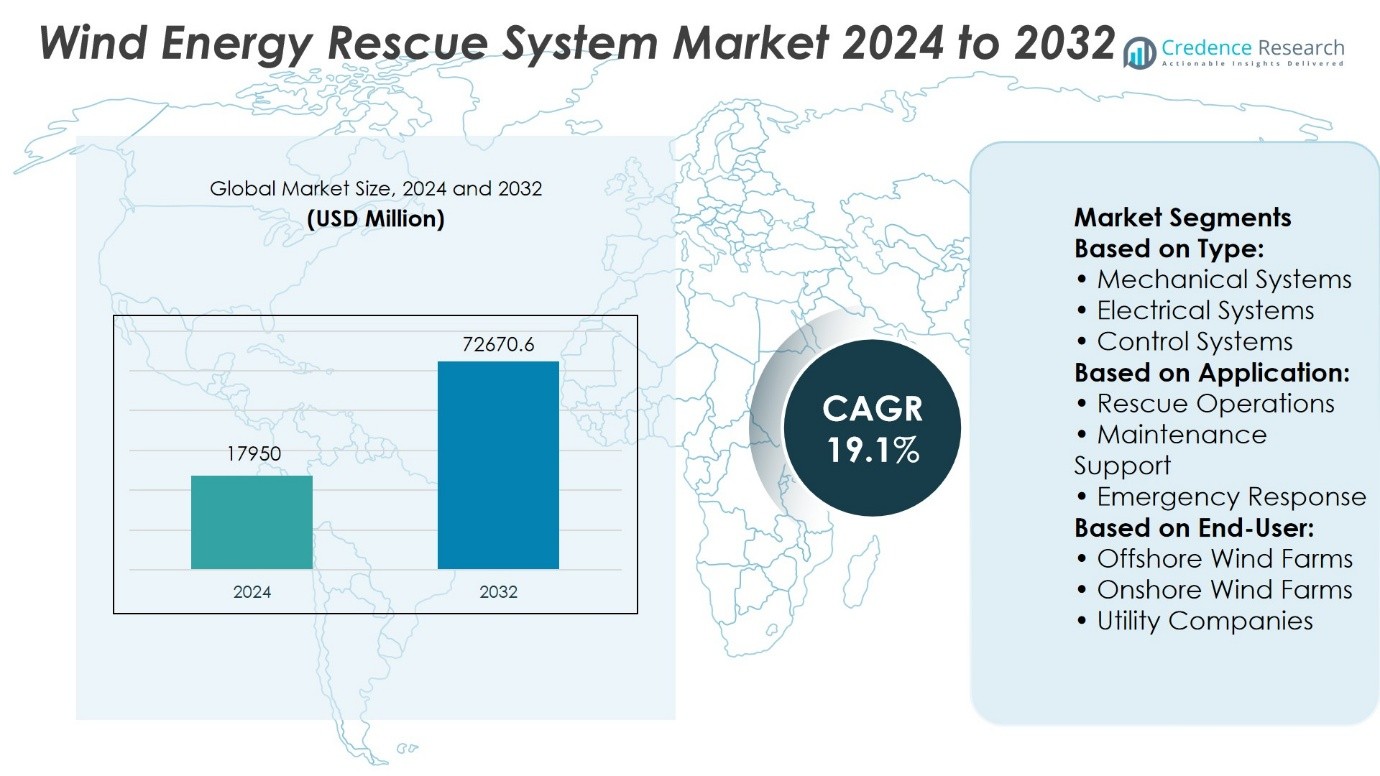
Wind Energy Rescue System Market size was valued at USD 17950 million in 2024 and is anticipated to reach USD 72670.6 million by 2032, at a CAGR of 19.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Wind Energy Rescue System Market Size 2024 | USD 17950 Million |
| Wind Energy Rescue System Market, CAGR | 19.1% |
| Wind Energy Rescue System Market Size 2032 | USD 72670.6 Million |
The Wind Energy Rescue System Market grows on the strength of rising safety regulations, expansion of offshore wind projects, and increasing awareness of workforce protection. It benefits from strict compliance frameworks that mandate advanced evacuation and rescue solutions for technicians working at height. Offshore developments create demand for corrosion-resistant systems capable of operating in harsh marine environments, while onshore projects favor portable and cost-effective equipment. The market reflects trends in digitalization, with IoT-enabled monitoring tools and automated descent devices improving readiness and reliability. It also advances through ergonomic designs that enhance user efficiency and support rapid deployment during emergencies.
The Wind Energy Rescue System Market shows strong adoption in Europe, holding leadership through extensive offshore wind projects and strict safety standards, while North America follows with regulatory-driven demand across onshore and offshore sites. Asia-Pacific grows rapidly with expanding wind capacity in China, India, and Japan, whereas Latin America and the Middle East & Africa display gradual progress. Key players shaping the market include Siemens Gamesa, GE Renewable Energy, Goldwind, Nordex SE, Suzlon Energy, MHI Vestas, Acciona Energy, and EDP Renewables.
Market Insights
- Wind Energy Rescue System Market size was valued at USD 17,950 million in 2024 and is anticipated to reach USD 72,670.6 million by 2032, at a CAGR of 19.1%.
- Rising safety regulations and stricter compliance frameworks drive adoption of advanced rescue and evacuation systems.
- Growing offshore wind projects increase demand for corrosion-resistant and specialized equipment suitable for marine environments.
- Digitalization trends highlight IoT-enabled monitoring tools and automated descent devices to improve readiness and reliability.
- Competition intensifies with key players investing in innovation, including Siemens Gamesa, GE Renewable Energy, Goldwind, Nordex SE, Suzlon Energy, MHI Vestas, Acciona Energy, and EDP Renewables.
- High equipment and maintenance costs act as restraints, especially for smaller operators in emerging markets.
- Europe leads with strong adoption, North America follows with regulatory-driven demand, Asia-Pacific shows rapid growth, while Latin America and the Middle East & Africa display gradual development.
Market Drivers
Regulatory Standards Driving Adoption of Safety Systems
Governments enforce strict safety regulations for wind energy projects to minimize risks during turbine maintenance and operation. The Wind Energy Rescue System Market gains traction as international safety standards such as ISO 12100 and OSHA guidelines mandate reliable evacuation solutions. Compliance requirements push operators to invest in advanced rescue equipment that ensures worker protection at heights. It drives demand for certified descent devices, harnesses, and emergency evacuation kits across offshore and onshore projects. The increasing focus on occupational safety strengthens adoption among global developers. Authorities continue to monitor safety compliance, creating a steady pull for standardized rescue systems.
- For instance, Skylotec GmbH developed its Milan 2.0 Hub rescue device, capable of controlled descent speeds of 0.9 meters per second and load capacity of up to 280 kilograms.
Expansion of Offshore Wind Projects Increasing Demand
Global investment in offshore wind projects expands at a rapid pace, creating new challenges for worker safety in remote and high-altitude environments. The Wind Energy Rescue System Market benefits from installations that require specialized evacuation systems designed for offshore platforms. It secures importance where distance from shore reduces the availability of conventional emergency support. Operators rely on robust rope access systems, automated descent devices, and rapid deployment kits to manage emergencies. The scale of offshore projects amplifies the need for safety redundancy across turbines. Rising capital in offshore wind farms reinforces consistent demand for advanced rescue technologies.
- For instance, Cresto Safety SMARTLINE X descent device supports a user weight of 140 kg and enables safe manual evacuation from heights up to 25 meters features that have become standard across numerous offshore turbine installations.
Technological Advancements Enhancing Rescue Capabilities
Continuous innovation in personal protective equipment and mechanical descent devices enhances the efficiency of turbine rescue operations. The Wind Energy Rescue System Market integrates automatic braking features, lightweight materials, and modular designs that improve usability. It encourages operators to adopt equipment that reduces evacuation time without compromising safety. Manufacturers deploy smart monitoring systems that ensure equipment readiness for critical use. Compact and portable designs allow easier transport across challenging turbine environments. Investments in R&D ensure that rescue systems evolve in line with the growing complexity of wind turbine designs.
Rising Awareness of Worker Safety Promoting Market Growth
Employers in the renewable energy sector increasingly recognize the importance of investing in worker safety to reduce downtime and liability. The Wind Energy Rescue System Market strengthens its position as companies embed rescue protocols into standard operations. It reflects growing emphasis on minimizing risks associated with high-altitude maintenance work. Training programs supported by manufacturers improve the competency of technicians in using rescue equipment effectively. Partnerships between equipment providers and wind farm operators help create tailored evacuation solutions. Heightened focus on preventive safety culture ensures consistent growth in adoption of rescue systems worldwide.
Market Trends
Integration of Smart Monitoring and Digital Safety Tools
The Wind Energy Rescue System Market evolves with the integration of smart monitoring systems that track equipment readiness and performance. It incorporates sensors and IoT-enabled devices that alert operators to potential faults before emergencies occur. Remote monitoring platforms allow supervisors to ensure compliance with safety standards across multiple sites. Data analytics provide insights into usage patterns, improving preventive maintenance schedules. Digitalization enhances overall rescue preparedness and reduces downtime. The trend reinforces the movement toward proactive safety management in wind energy operations.
- For instance, Cresto Safety’s RESQ SOLO X Wind evacuation device incorporates a built‑in IoT sensor module that logs automated descent operations from heights up to 300 meters, capturing descent speed of 1.4 m/s and device weight of just 5.15 kg for a 100‑meter kit, with each event timestamped and remotely retrievable over its 30‑year certified lifespan.
Growing Preference for Lightweight and Ergonomic Equipment
Manufacturers emphasize the development of lightweight harnesses, compact descent devices, and ergonomic rescue kits. The Wind Energy Rescue System Market responds to the demand for solutions that reduce physical strain on technicians working at height. It encourages adoption of portable systems that can be carried easily during turbine climbs. Materials such as high-strength composites and advanced polymers improve durability while minimizing weight. Operators favor products that combine comfort and safety in high-risk environments. The trend highlights a shift toward practical equipment that improves technician efficiency during emergencies.
- For instance, the Cresto Safety Fusion Active+ Wind 1137 harness crafted specifically for wind-power technicians supports users from 30 kg up to 140 kg, features a minimum breaking strength (MBS) of 22 kN, and offers a working temperature range.
Expansion of Offshore Wind Farms Driving Specialized Solutions
Global expansion of offshore wind projects creates demand for specialized rescue technologies capable of withstanding harsh marine conditions. The Wind Energy Rescue System Market adapts with equipment designed for corrosive environments and long-distance evacuation. It includes advanced rope systems, sealed descent devices, and integrated flotation gear for offshore platforms. Growing turbine heights offshore increase the complexity of rescue planning. Manufacturers collaborate with energy companies to customize solutions for remote and large-scale projects. The trend establishes offshore safety as a priority area for innovation in rescue systems.
Increasing Focus on Training and Standardized Safety Protocols
Industry stakeholders invest in comprehensive training programs to ensure proper use of rescue systems during critical incidents. The Wind Energy Rescue System Market supports this trend with simulation tools and virtual training modules that replicate emergency conditions. It aligns with global safety certifications that require workers to demonstrate competency in evacuation procedures. Training providers work closely with equipment manufacturers to deliver tailored programs. Standardization of rescue protocols strengthens overall safety culture across the wind sector. The trend highlights the growing recognition of workforce preparedness as a critical element of risk management.
Market Challenges Analysis
High Cost of Specialized Rescue Equipment and Maintenance
The Wind Energy Rescue System Market faces challenges linked to the high cost of specialized safety devices and continuous maintenance requirements. It demands significant investment in advanced harnesses, automated descent systems, and offshore-certified evacuation kits, which raises overall project expenditure. Smaller operators often struggle to allocate sufficient budgets for premium rescue technologies. High maintenance costs emerge from the need to inspect, certify, and replace components at regular intervals to comply with safety standards. Limited cost-effective alternatives restrict widespread adoption, especially in emerging markets. The price barrier delays upgrades and slows deployment of new technologies in the sector.
Operational Complexity and Limited Skilled Workforce
Complex turbine designs and offshore installations increase the operational challenges associated with rescue systems. The Wind Energy Rescue System Market must address the shortage of trained professionals capable of executing high-altitude emergency protocols. It highlights gaps in global training standards that create inconsistent levels of preparedness across regions. Harsh environmental conditions in offshore locations complicate equipment deployment and reduce reliability under extreme stress. Limited awareness among smaller wind farm operators weakens adoption of comprehensive safety frameworks. The challenge remains in aligning advanced technology with skilled personnel to ensure effective and timely evacuation in emergencies.
Market Opportunities
Rising Expansion of Offshore Wind Projects Creating Demand for Advanced Rescue Systems
The Wind Energy Rescue System Market finds major opportunities in the rapid expansion of offshore wind energy capacity worldwide. It benefits from projects located in deeper waters with taller turbines that demand specialized safety equipment. Offshore operations require robust rescue solutions designed to withstand corrosion, strong winds, and remote access challenges. Manufacturers can capitalize on this growth by delivering systems with higher load capacity, sealed components, and integrated flotation features. Governments supporting offshore wind investment create favorable conditions for rescue technology providers. Increasing scale of offshore projects secures long-term potential for customized safety systems tailored to harsh marine environments.
Technological Innovation Driving Adoption of Next-Generation Rescue Solutions
Advances in smart safety equipment and digital monitoring platforms open opportunities for new product development. The Wind Energy Rescue System Market supports innovation in IoT-enabled harnesses, automated braking systems, and predictive maintenance tools. It enables operators to improve reliability, reduce downtime, and ensure compliance with evolving safety standards. Integration of virtual training modules enhances workforce readiness and expands the service portfolio of equipment suppliers. Partnerships between rescue system manufacturers and turbine developers create pathways for co-engineered solutions. Growing focus on sustainability and advanced materials strengthens the market’s position for next-generation rescue technologies.
Market Segmentation Analysis:
By Type
The market divides by type into mechanical systems, electrical systems, and control systems. Mechanical systems dominate due to their reliability and ability to function without external power sources, making them critical in high-risk scenarios. Electrical systems gain traction with the adoption of powered winches and automated descent devices that improve evacuation speed. Control systems play a key role in ensuring integration of rescue devices with turbine safety frameworks. It emphasizes monitoring, fault detection, and system readiness for emergency deployment. Each category strengthens overall safety standards by addressing different aspects of wind turbine rescue requirements.
- For instance, the 3M™ DBI‑SALA® Rollgliss™ R550 is an electrically assisted descent device rated for rescue from heights up to 500 m for one user (maximum 141 kg) or 175 m for two users (combined 282 kg).
By Application
The Wind Energy Rescue System Market segments by application into rescue operations, maintenance support, and emergency response. Rescue operations represent a core area where specialized descent devices, harnesses, and evacuation kits are used during high-altitude incidents. It reflects steady demand from operators seeking reliable solutions to safeguard technicians working on tall turbines. Maintenance support emerges as a growing segment with systems designed to assist routine inspections and servicing activities. Emergency response applications gain importance as turbine sizes increase and offshore installations expand into remote locations. Equipment tailored for rapid deployment enhances operational safety and improves worker confidence during critical events.
- For instance, Skylotec MILAN 2.0 HUB enables controlled two-person abseiling at a constant speed of 0.90 m/s, supports a combined load of up to 280 kg, and permits descents from heights up to 500 m, while weighing just 3.12 kg per device.
By End User
End-user segmentation covers offshore wind farms, onshore wind farms, and utility companies. Offshore wind farms generate strong demand for advanced systems capable of withstanding harsh marine environments and remote operations. It highlights the need for durable, corrosion-resistant materials and specialized training for offshore technicians. Onshore wind farms continue to rely on compact and portable equipment that supports faster rescue procedures in land-based installations. Utility companies adopt integrated safety frameworks, combining rescue devices with monitoring and compliance systems. This segment benefits from long-term investment in workforce safety and regulatory alignment. Growing complexity of both offshore and onshore projects ensures that rescue system providers remain central to operational safety strategies.
Segments:
Based on Type:
- Mechanical Systems
- Electrical Systems
- Control Systems
Based on Application:
- Rescue Operations
- Maintenance Support
- Emergency Response
Based on End-User:
- Offshore Wind Farms
- Onshore Wind Farms
- Utility Companies
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a 32% share of the Wind Energy Rescue System Market, driven by large-scale wind energy deployment in the United States and Canada. The region benefits from advanced occupational safety regulations enforced by OSHA and other agencies, which mandate strict compliance in high-altitude operations. It reflects consistent demand for advanced rescue systems, particularly mechanical descent devices and electrical evacuation kits, to support both onshore and offshore projects. The U.S. offshore wind market, expanding along the Atlantic coast, accelerates investment in rescue solutions that withstand harsh marine environments. Canadian initiatives in renewable energy, supported by provincial governments, further strengthen regional demand. It ensures steady adoption as utilities and operators prioritize workforce safety alongside wind power expansion.
Europe
Europe accounts for the largest share at 38%, reflecting its leadership in offshore wind development and stringent workplace safety standards. Countries such as Germany, the UK, Denmark, and the Netherlands drive adoption through expansive offshore projects and high turbine density. The Wind Energy Rescue System Market in Europe benefits from EU-level directives such as the European Green Deal, which links safety compliance with broader sustainability goals. It records strong demand for corrosion-resistant rescue equipment tailored to offshore platforms exposed to North Sea conditions. Manufacturers collaborate with European utilities to integrate advanced monitoring tools with rescue systems, enhancing preparedness. The region sets benchmarks in safety training and standardized rescue protocols, making it a central hub for innovation and implementation.
Asia-Pacific
Asia-Pacific holds a 22% share, reflecting its growing role in wind energy deployment across China, India, Japan, South Korea, and Australia. The region’s expansion in both onshore and offshore wind projects fuels demand for advanced rescue solutions. It emphasizes cost-effective mechanical systems in developing markets such as India, where affordability drives adoption. In contrast, Japan and South Korea invest in advanced control and monitoring systems to support offshore safety frameworks. China’s rapid turbine installations necessitate large-scale procurement of descent and evacuation devices, positioning it as a major growth driver. The region demonstrates increasing awareness of workforce safety, supported by government-backed renewable energy programs. It ensures long-term demand for systems that balance affordability with compliance to evolving safety standards.
Latin America
Latin America captures a 5% share, reflecting slower but steady adoption of wind energy rescue systems. Countries such as Brazil, Mexico, and Chile invest in wind energy projects where safety compliance is gradually gaining attention. The Wind Energy Rescue System Market in the region grows with the expansion of onshore projects that require basic mechanical rescue devices. It faces challenges from limited awareness and budget constraints among smaller operators. However, international partnerships and funding initiatives encourage higher safety standards. Offshore projects in Brazil create emerging opportunities for advanced equipment capable of handling marine conditions. Regional adoption is expected to strengthen as governments integrate safety into renewable energy strategies.
Middle East & Africa
The Middle East & Africa account for a 3% share, reflecting early-stage adoption with limited wind energy penetration. South Africa leads regional demand with operational wind farms requiring basic rescue systems for technician safety. The Wind Energy Rescue System Market in this region is shaped by increasing renewable energy commitments under national decarbonization goals. Offshore wind projects under planning in countries like Morocco and Egypt present long-term prospects for advanced rescue systems. It emphasizes the importance of cost-sensitive solutions in markets where affordability remains critical. International equipment suppliers seek entry through joint ventures and government-supported projects. Growing attention to workforce safety signals gradual expansion, though the region remains the smallest market globally.
Key Player Analysis
- MHI Vestas
- Acciona Energy
- GE Renewable Energy
- Nordex
- Siemens Gamesa
- Suzlon Energy
- Goldwind
- China Longyuan Power Group
- EDP Renewables
- Nordex SE
Competitive Analysis
The Wind Energy Rescue System Market players such as Siemens Gamesa, GE Renewable Energy, Goldwind, Nordex SE, MHI Vestas, Suzlon Energy, Acciona Energy, China Longyuan Power Group, and EDP Renewables. The Wind Energy Rescue System Market demonstrates a competitive environment driven by innovation, regulatory compliance, and regional expansion strategies. Companies invest heavily in research and development to introduce advanced rescue solutions that meet international safety standards. Offshore wind projects create strong demand for corrosion-resistant systems, automated descent devices, and digital monitoring tools tailored for harsh environments. Onshore markets emphasize cost-effective and portable solutions that support rapid adoption in developing regions. Partnerships with training providers and renewable energy operators enhance workforce preparedness and reinforce safety protocols. Continuous focus on sustainability and integration of smart technologies shapes the direction of product development. The market reflects an industry committed to balancing performance, affordability, and safety in line with the growing complexity of wind energy operations.
Recent Developments
- In January 2025, GE Vernova’s received orders in 2024 to repower over 1 gigawatt of wind turbines in the U.S. The orders were booked between the first and fourth quarters of 2024. These repower projects are expected to reach their commercial operation date between 2024 and 2027.
- In August 2023, Vestas announced a 158 MW order to repower three undisclosed U.S. wind projects, supplying 72 V120-2.2 MW turbines and providing a 10-year service agreement. The turbines were slated for delivery beginning in late 2023, with commissioning expected in late 2024, supporting the U.S. net-zero goals.
- In March 2023, GE Renewable Energy selected Eastgate Engineering, to provide mechanical and electrical activities for the pre-assembly of the towers and nacelles for the Haliade-X turbines to be used at Dogger Bank Offshore Wind Farm. The contract is anticipated to support approximately 90 local jobs to execute the installation, testing and commissioning works, associated with the pre-assembly of the three tower sections and nacelles.
Market Concentration & Characteristics
The Wind Energy Rescue System Market reflects a moderately concentrated structure where a mix of global manufacturers and regional suppliers compete on innovation, reliability, and compliance with safety regulations. It demonstrates strong reliance on certified equipment that aligns with international standards, driving consistency in product quality across markets. Leading players focus on integrating advanced technologies such as automated descent systems, IoT-enabled monitoring tools, and lightweight materials to differentiate offerings. Smaller suppliers strengthen their position by providing cost-effective solutions tailored for onshore projects in developing regions. Offshore projects push the need for specialized equipment, which increases demand for partnerships between turbine developers and safety solution providers. It highlights a market characterized by steady technological progress, high regulatory influence, and growing awareness of worker safety that continues to define competitive dynamics.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for advanced rescue systems will rise with the global expansion of offshore wind projects.
- Integration of smart monitoring tools will strengthen equipment reliability and safety compliance.
- Lightweight and ergonomic designs will gain preference to improve technician efficiency.
- Growth in high-capacity turbines will drive the need for specialized evacuation technologies.
- Training programs and digital simulations will become central to workforce preparedness.
- Partnerships between equipment manufacturers and wind farm operators will increase.
- Regional markets in Asia-Pacific and Latin America will emerge as growth opportunities.
- Standardization of safety protocols will enhance adoption across global projects.
- Investment in R&D will accelerate the development of automated and hybrid systems.
- Rising focus on sustainability will encourage the use of durable and recyclable materials.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Wind Energy Rescue System Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Wind Energy Rescue System Market projected to grow between 2025 and 2032?
Which Wind Energy Rescue System Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Wind Energy Rescue System Market?
Who are the leading companies in the Wind Energy Rescue System Market?
Which region commanded the largest share of the Wind Energy Rescue System Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Wind Energy Rescue System Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Wind Energy Rescue System Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 17,950 million → 2032: USD 72,670.6 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Wind Energy Rescue System Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Wind Energy Rescue System Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Wind Energy Rescue System Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Wind Energy Rescue System Market Drivers
- 3.3 Wind Energy Rescue System Market Restraints & Challenges
- 3.4 Wind Energy Rescue System Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Wind Energy Rescue System Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Wind Energy Rescue System Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Wind Energy Rescue System category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Wind Energy Rescue System Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Wind Energy Rescue System Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Wind Energy Rescue System. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Wind Energy Rescue System Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Wind Energy Rescue System Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Wind Energy Rescue System Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Wind Energy Rescue System (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Wind Energy Rescue System
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Wind Energy Rescue System Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Wind Energy Rescue System Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Wind Energy Rescue System Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Wind Energy Rescue System Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Wind Energy Rescue System Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Wind Energy Rescue System Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Wind Energy Rescue System Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Wind Energy Rescue System Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
