
Wood Charcoal Market Overview:
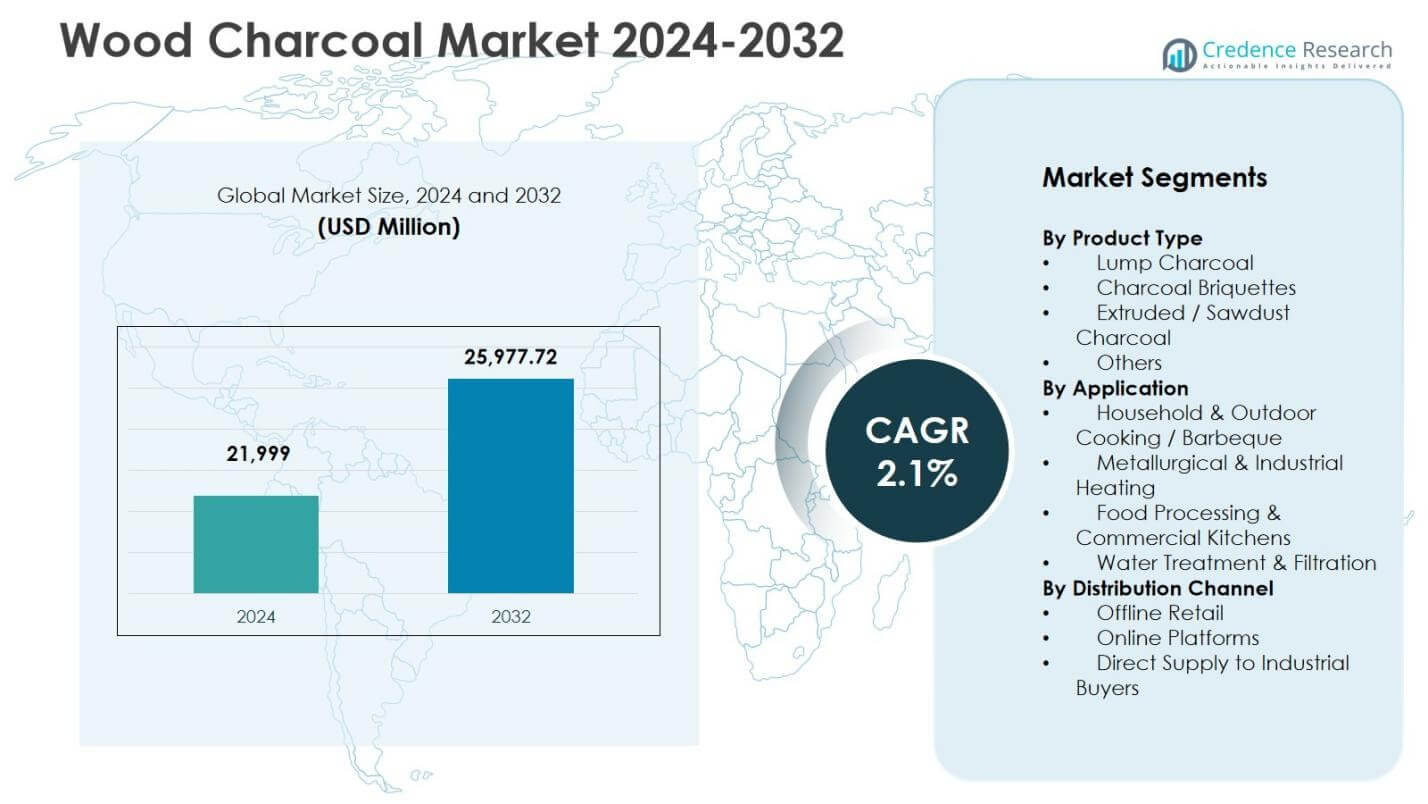
Wood Charcoal Market size was valued USD 21,999 Million in 2024 and is anticipated to reach USD 25,977.72 Million by 2032, at a CAGR of 2.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Wood Charcoal Market Size 2024 | USD 21,999 million |
| Wood Charcoal Market, CAGR | 2.1% |
| Wood Charcoal Market Size 2032 | USD 25,977.72 million |
Wood Charcoal Market Insights
- Market driver is rising household barbeque usage, outdoor cooking culture, and increasing adoption of lump charcoal and briquettes across residential, hospitality, and small-scale industrial heating applications globally.
- Market trends include growing demand for premium natural charcoal, eco-certified briquettes, sustainability-focused sourcing, and expanding e-commerce distribution supporting brand visibility and value-added grilling product preferences.
- Market analysis highlights strong presence of leading players focusing on product quality and heat performance, while Lump Charcoal remained the dominant product sub-segment with a 38.6 percent share in 2024.
- Regional analysis shows Asia-Pacific leading with a 32.8 percent share in 2024, followed by North America with 29.4 percent, Europe with 24.7 percent, Latin America with 7.6 percent, and Middle East & Africa with 5.5 percent.
Wood Charcoal Market Segmentation Analysis:
By Product Type
The Wood Charcoal Market by product type is dominated by Lump Charcoal, which held a 38.6% share in 2024 due to its higher calorific value, low chemical content, and strong consumer preference for premium grilling and artisanal barbeque applications. Charcoal Briquettes continue to expand adoption in urban households because of affordability and uniform burning performance, while Extruded/Sawdust Charcoal supports demand in industrial heating owing to consistent density and large-scale supply. Others, including coconut-shell and hardwood charcoal, gain traction as sustainability-focused alternatives. Growth across this segment is driven by rising outdoor cooking culture and expanding foodservice consumption.
- For instance, Royal Oak's 100% All Natural Hardwood Lump Charcoal, made from sustainably sourced oak and hickory, lights quickly and burns hotter for high-temperature searing in grilling and low-and-slow smoking.
By Application
In the application segment, Household & Outdoor Cooking / Barbeque emerged as the leading sub-segment with a 47.2% share in 2024, supported by increasing barbeque culture, higher leisure dining spending, and growing penetration of charcoal grills in residential and hospitality environments. Metallurgical & Industrial Heating contributes stable demand from foundries and metal processing units, while Food Processing & Commercial Kitchens rely on charcoal for flavor-centric cooking and smoking. Water Treatment & Filtration represents a gradually expanding niche application. Growth across this segment is driven by flavor-driven consumption preferences, heat efficiency advantages, and rising usage in urban and semi-urban markets.
- For instance, Jealous Devil lump charcoal burns at 1172°F with minimal ash, favored by chefs like Steve Cain at El Gaucho Portland for clean flavors in smoking meats and seafood.
By Distribution Channel
By distribution channel, Offline Retail remained the dominant sub-segment with a 56.4% share in 2024, driven by strong availability across supermarkets, hardware stores, garden centers, and local vendors, along with bulk purchasing behavior among households and small enterprises. Online Platforms are expanding rapidly as consumers shift toward e-commerce for convenience, wider product access, and doorstep delivery. Direct Supply to Industrial Buyers plays a key role in fulfilling metallurgical, manufacturing, and commercial kitchen requirements through contract-based procurement. Growth in this segment is supported by expanding retail networks, private-label offerings, and accelerating digital retail adoption in emerging markets.
Key Growth Drivers
Rising Demand from Household and Outdoor Cooking Activities
Growth in the Wood Charcoal Market is strongly driven by increasing household barbeque usage and outdoor cooking culture across residential and recreational environments. Consumers prefer lump charcoal and briquettes for authentic smoky flavor, higher heat intensity, and consistent grilling performance, which strengthens adoption in homes, restaurants, and leisure dining venues. The expansion of quick-service restaurants, food trucks, and outdoor dining spaces further accelerates charcoal consumption. Additionally, rising disposable income, tourism-linked foodservice demand, and growing popularity of premium barbeque equipment support sustained market growth. Emerging economies witness strong uptake as urbanization and lifestyle shifts increase charcoal-based cooking use across semi-urban and rural communities.
- For instance, Kingsford launched Signature Flavors briquets in March 2022, pre-mixed with enhancers like garlic onion paprika and Memphis BBQ that emit continuous flavor when added to ignited coals, enhancing grilled dishes in homes and foodservice venues.
Expanding Industrial and Metallurgical Applications
Industrial and metallurgical heating applications significantly contribute to market expansion as wood charcoal is increasingly used in metal processing, foundry operations, and small-scale manufacturing environments. Its high carbon content, strong heat output, and lower emission profile compared to certain fossil-fuel alternatives make it suitable for controlled industrial heating processes. Producers benefit from rising demand in steelmaking auxiliaries, blacksmith operations, and artisanal metalcraft sectors. Growth is also reinforced by small industrial clusters in Asia, Latin America, and Africa that rely on charcoal due to energy cost efficiency and localized availability, supporting steady, long-term consumption across industrial end-use segments.
- For instance, technical assessments by CSIRO indicate that replacing 50% of fossil carbon with charcoal in steelmaking could reduce total industrial CO2 emissions by about 2% in Australia and around 3% globally, highlighting charcoal’s role as a transitional industrial fuel.
Sustainability Preference and Renewable Fuel Adoption
Sustainability-focused consumption trends act as a major growth catalyst as wood charcoal derived from managed forestry, coconut shells, and agricultural residues gains acceptance as a renewable, bio-based fuel alternative. Governments and private stakeholders are promoting responsible sourcing, reforestation initiatives, and eco-certified charcoal production, reinforcing market credibility. Demand is further strengthened by growing awareness of circular-economy practices and waste-to-value conversion in charcoal briquette manufacturing. Hospitality chains and environmentally conscious households increasingly adopt natural and low-additive charcoal products, supporting premiumization and product differentiation. These sustainability-led initiatives create long-term growth opportunities for compliant and certified charcoal producers.
Key Trends & Opportunities
Shift Toward Value-Added and Premium Charcoal Products
A major market trend is the transition toward value-added charcoal formats such as lump charcoal, flavored briquettes, smoke-enhancing variants, and eco-certified products targeted at premium household and commercial grilling segments. Consumers increasingly prioritize clean-burning, high-heat, and chemical-free charcoal options, driving product innovation and brand repositioning. Manufacturers are investing in packaging improvements, moisture-resistant storage formats, and retail-focused branding strategies to enhance shelf appeal. The rise of e-commerce also creates opportunities for niche artisanal brands and specialty exporters. This trend supports margin expansion, product diversification, and strong growth potential across developed and emerging consumer barbeque markets.
- For instance, Cowboy produces Garlic & Onion Hardwood Briquets blended with real onion and garlic, releasing savory smoke flavors during cooking on kettles, barrels, or Kamado grills. These briquettes enhance grilled beef, pork, and vegetables with consistent aroma from lighting through cooking.
Growing Export Trade and Emerging-Market Production Opportunities
Global trade expansion presents significant opportunities as developing regions emerge as large-scale charcoal production hubs supplying international barbeque and industrial fuel markets. Countries in Africa, Southeast Asia, and Latin America benefit from raw material availability, labor advantages, and rising export-oriented manufacturing investments. Export growth is further facilitated by strengthening supply chains, logistics integration, and government-supported rural enterprise programs. Meanwhile, importing regions experience increasing demand for standardized, high-quality charcoal products aligned with safety and sustainability certifications. This trend creates opportunities for cross-border partnerships, capacity expansion, and technology-driven improvements in production efficiency and quality consistency.
- For instance, DIN CERTCO (part of TÜV Rheinland) has issued more than 280 valid DIN EN 1860-2 certificates for barbecue charcoal and briquettes from nearly 20 countries, enabling exporters in emerging regions to access premium European retail channels with verified safety and performance standards.
Key Challenges
Environmental Regulations and Deforestation Concerns
The Wood Charcoal Market faces regulatory challenges related to deforestation risks, illegal logging activities, and unsustainable raw material sourcing practices. Stricter environmental laws, certification requirements, and monitoring frameworks are being implemented across multiple regions to control unmanaged forest exploitation and carbon-intensive production cycles. Producers operating without compliance infrastructure encounter operational restrictions and export limitations. Transitioning toward sustainable forestry, plantation-based sourcing, and standardized production practices increases capital and certification costs for small and medium manufacturers. These regulatory and environmental pressures compel market players to upgrade production models while maintaining cost competitiveness, posing strategic and financial challenges.
Competition from Alternative Fuels and Cleaner Energy Substitutes
The market also encounters challenges from increasing adoption of alternative fuels such as electricity-powered grills, gas barbeque systems, biomass pellets, and cleaner industrial heating technologies. Urban consumers in developed regions increasingly shift toward convenient, low-smoke cooking solutions, reducing reliance on traditional charcoal in certain segments. Industrial users are gradually evaluating energy-efficient substitutes driven by emission targets and operational safety concerns. Price fluctuations in raw materials and supply disruptions further intensify competition with substitute fuels. To sustain demand, charcoal producers must emphasize performance differentiation, sustainability advantages, and product innovation to retain relevance in evolving consumer and industrial energy ecosystems.
Regional Analysis
North America
North America held a 29.4% share in 2024, supported by strong household barbeque culture, high consumption of lump charcoal and premium briquettes, and widespread availability through retail and specialty grilling stores. The United States leads demand due to recreational cooking trends, outdoor dining expansion, and growing adoption of eco-certified charcoal for residential and commercial grilling. Canada contributes steady consumption driven by foodservice penetration and seasonal barbeque activities. Market growth in the region is reinforced by product premiumization, brand-driven purchasing behavior, and increasing consumer inclination toward natural, chemical-free charcoal variants across both residential and hospitality-based usage environments.
Europe
Europe accounted for a 24.7% share in 2024, driven by rising demand from household barbeque applications, tourism-linked outdoor dining, and a growing shift toward sustainable and certified charcoal products. Germany, the United Kingdom, and France remain key consumption markets, supported by strong retail penetration and increasing popularity of premium grilling equipment. Regulatory emphasis on legal sourcing and controlled carbon emissions encourages adoption of environmentally responsible charcoal formats. Eastern European countries also support demand through metallurgical and small-scale industrial usage. Growth is reinforced by expanding e-commerce availability, higher consumer awareness of product quality standards, and strong summer-season consumption patterns.
Asia-Pacific
Asia-Pacific dominated the market with a 32.8% share in 2024, driven by large-scale production capacity, strong export activity, and extensive usage across household cooking, industrial heating, and food processing segments. Indonesia, Vietnam, India, and China represent major manufacturing and consumption hubs due to resource availability and expanding rural and semi-urban charcoal usage. Growing commercial kitchen adoption, rising outdoor dining culture, and cost-efficient energy preferences strengthen regional demand. Export-oriented briquette and coconut-shell charcoal production further supports revenue growth. Government initiatives promoting managed forestry and small-enterprise charcoal manufacturing also enhance supply stability and long-term market expansion across the region.
Latin America
Latin America captured a 7.6% share in 2024, supported by strong natural resource availability, expanding charcoal production clusters, and increasing exports to North America and Europe. Brazil and Mexico lead the market due to active industrial heating applications, rural household usage, and growing participation in premium barbeque consumption. Small-scale manufacturing units and agricultural residue-based briquette production strengthen domestic value creation. Rising tourism, outdoor cooking culture, and growth in commercial dining environments further contribute to market expansion. Ongoing investments in sustainable forestry and controlled kiln technologies enhance product quality, helping regional producers align with global sourcing and certification standards.
Middle East & Africa
The Middle East & Africa region held a 5.5% share in 2024, characterized by strong reliance on charcoal for household cooking, traditional food preparation, and emerging export-oriented production activities. African countries such as Nigeria, Ghana, and Tanzania contribute significantly through briquette and hardwood charcoal manufacturing supported by local resource availability. The Middle East records growing demand from hospitality and outdoor dining segments, particularly in tourism-driven economies. Market expansion is influenced by informal production networks and improving supply chain organization, while sustainability initiatives and gradual transition toward regulated sourcing practices create structured growth opportunities for regional charcoal producers.
Wood Charcoal Market Segmentations:
By Product Type
- Lump Charcoal
- Charcoal Briquettes
- Extruded / Sawdust Charcoal
- Others
By Application
- Household & Outdoor Cooking / Barbeque
- Metallurgical & Industrial Heating
- Food Processing & Commercial Kitchens
- Water Treatment & Filtration
By Distribution Channel
- Offline Retail
- Online Platforms
- Direct Supply to Industrial Buyers
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis in the Wood Charcoal Market is shaped by leading players such as Royal Oak Enterprises LLC, Kingsford Products Company, Duraflame Inc., Saint Louis Charcoal Company, Fogo Charcoal, The Original Charcoal Company, B&B Charcoal, Fire & Flavor, Cooks International, and Kamado Joe. The market reflects a balanced mix of large multinational manufacturers, regional producers, and export-oriented suppliers competing on product quality, heat efficiency, sustainability certification, and pricing. Companies increasingly focus on premium lump charcoal, eco-certified briquettes, and value-added grilling products to strengthen brand positioning across household and outdoor cooking applications. Strategic initiatives include retail network expansion, partnerships with barbeque equipment brands, and investments in packaging innovation and moisture-resistant storage formats. Producers are also enhancing production efficiency through kiln modernization, sustainable raw-material sourcing, and coconut-shell and biomass-based charcoal development. Meanwhile, growing e-commerce penetration and rising consumer preference for natural, chemical-free charcoal continue to intensify competition and support ongoing product differentiation across key markets.
Key Player Analysis
- Royal Oak Enterprises LLC
- Kingsford Products Company
- Duraflame, Inc.
- Fire & Flavor
- Fogo Charcoal
- Cooks International
- Saint Louis Charcoal Company
- The Original Charcoal Company
- B&B Charcoal
- Kamado Joe
Recent Developments
- In October 2025, Kingsford Products Company partnered with football personality Jason Kelce to launch Slow Burn, a unique fragrance inspired by charcoal grilling aroma.
- In October 2025, Duraflame introduced the duraflame® Char·Logs™, a premium charcoal grilling log product made from oak and hickory using Thermacore™ Airflow Technology for quicker lighting and consistent high heat.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will record steady growth as outdoor cooking culture and barbeque adoption continue to expand across residential and hospitality sectors.
- Demand for premium lump charcoal and natural, chemical-free briquettes will increase as consumers prioritize flavor quality and clean-burning performance.
- Sustainability-certified charcoal sourced from managed forestry and agricultural residues will gain wider acceptance in global trade channels.
- Export-oriented production in Asia, Africa, and Latin America will strengthen as manufacturers scale capacity and improve quality standards.
- Industrial and metallurgical applications will maintain stable demand due to cost-efficient heating advantages in small-scale manufacturing environments.
- E-commerce and direct-to-consumer distribution will grow, enabling niche and artisanal charcoal brands to expand market reach.
- Product innovation will focus on moisture-resistant packaging, quick-lighting variants, and value-added grilling solutions.
- Increasing policy emphasis on legal sourcing and deforestation control will accelerate the transition toward regulated production models.
- Competition from gas grills, electric alternatives, and pellet-based fuels will encourage performance differentiation and premium positioning.
- Long-term market opportunities will emerge from circular-economy charcoal briquettes and bio-based fuel development initiatives.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Outdoor Cooking and Barbeque Culture
The growing popularity of outdoor cooking, barbeque events, and leisure dining is driving increased household and hospitality demand for wood charcoal, especially in urban and semi-urban areas. This trend is reinforced by rising disposable incomes and the proliferation of premium grilling equipment.
Preference for Premium and Natural Charcoal Products
Consumers are increasingly seeking high-quality, clean-burning, and chemical-free charcoal options such as lump charcoal and eco-certified briquettes, which offer superior flavor and heat performance. This shift supports market growth through product innovation and premiumization.
Sustainability and Renewable Fuel Adoption
The adoption of wood charcoal sourced from managed forestry, coconut shells, and agricultural residues is rising due to environmental awareness and regulatory support for renewable, bio-based fuels. Eco-certified and sustainably produced charcoal is gaining traction in both domestic and export markets.
Growth in Industrial and Metallurgical Applications
Wood charcoal's high carbon content and heat efficiency make it a preferred fuel for metallurgical processes, foundries, and small-scale industrial heating, particularly in emerging markets where cost and local resource availability are critical.
Expansion of E-commerce and Direct-to-Consumer Channels
The rapid growth of online platforms and direct-to-consumer sales is making a wider variety of charcoal products accessible to consumers, supporting the rise of niche and artisanal brands and driving overall market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Wood Charcoal Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Wood Charcoal Market projected to grow between 2024 and 2032?
Which Wood Charcoal Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Wood Charcoal Market?
Who are the leading companies in the Wood Charcoal Market?
Which region commanded the largest share of the Wood Charcoal Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Household & Outdoor Cooking / Barbeque
- 1.2.2 Metallurgical & Industrial Heating
- 1.2.3 Food Processing & Commercial Kitchens
- 1.2.4 Water Treatment & Filtration
- 1.3 By Product Type
- 1.3.1 Lump Charcoal
- 1.3.2 Charcoal Briquettes
- 1.3.3 Extruded / Sawdust Charcoal
- 1.3.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 21,999 Million → 2032: USD 25,977.72 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Wood Charcoal Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Wood Charcoal Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Wood Charcoal Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Wood Charcoal Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Wood Charcoal Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Wood Charcoal Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Wood Charcoal Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Wood Charcoal Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 21,999 Million → 2032: USD 25,977.72 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Wood Charcoal Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Household & Outdoor Cooking / Barbeque
- 12.3.7.2 Metallurgical & Industrial Heating
- 12.3.7.3 Food Processing & Commercial Kitchens
- 12.3.7.4 Water Treatment & Filtration
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Lump Charcoal
- 12.4.7.2 Charcoal Briquettes
- 12.4.7.3 Extruded / Sawdust Charcoal
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Wood Charcoal End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Wood Charcoal Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Wood Charcoal Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Wood Charcoal Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Royal Oak Enterprises LLC
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Kingsford Products Company
- 18.4 Duraflame, Inc.
- 18.5 Saint Louis Charcoal Company
- 18.6 Fogo Charcoal
- 18.7 The Original Charcoal Company
- 18.8 B&B Charcoal
- 18.9 Fire & Flavor
- 18.10 Cooks International
- 18.11 Kamado Joe
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

