
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Xenon Light Source Market Size 2024 | USD 3,465 million |
| Xenon Light Source Market, CAGR | 3% |
| Xenon Light Source Market Size 2032 | USD 4,389.35 million |
Market Overview
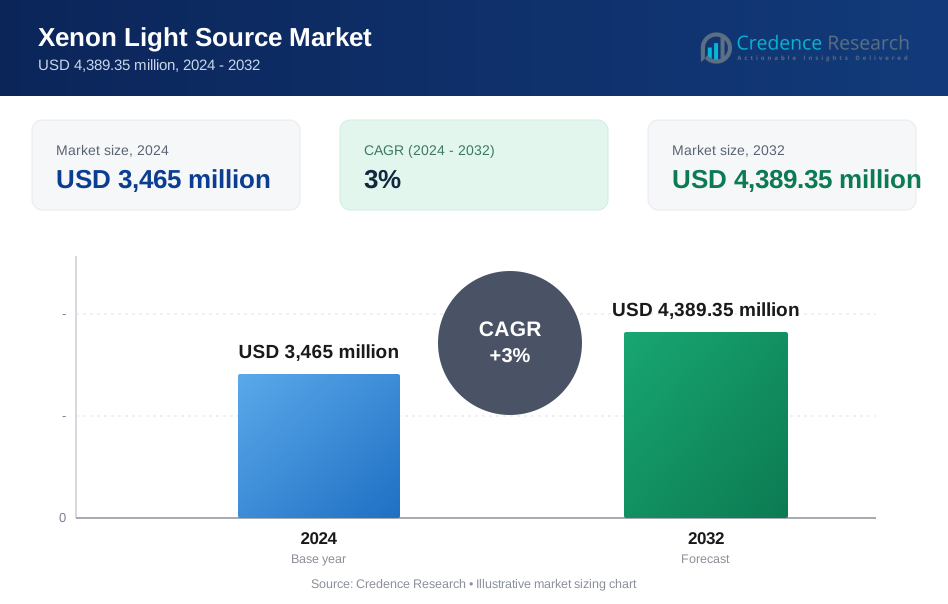
The Xenon Light Source market is projected to grow from USD 3,465 million in 2024 to USD 4,389.35 million by 2032, reflecting a compound annual growth rate (CAGR) of 3%.
The Xenon Light Source market is primarily driven by the growing demand for high-quality lighting solutions in various applications, including medical devices, projectors, and automotive lighting. Technological advancements in illumination efficiency and the rising adoption of xenon lights in theaters and large venues further propel market growth. Additionally, the increasing awareness of energy-efficient lighting solutions supports the shift towards xenon light sources, which offer superior brightness and color accuracy compared to traditional lighting options. These trends highlight the importance of innovation and sustainability in meeting the evolving needs of consumers and industries alike.
The xenon light source market shows significant growth across North America, Europe, and Asia-Pacific, with North America leading due to advanced technological adoption and strong demand in medical, automotive, and scientific applications. Europe follows closely, driven by research institutions and stringent lighting standards, while Asia-Pacific is expanding due to increasing industrialization and automotive manufacturing. Key players in this sector include Hamamatsu Photonics K.K., KARL STORZ SE & Co. KG, Stryker Corporation, Asahi Spectra USA, Inc., Olympus Medical Systems, Ocean Optics, Inc., and Excelitas Technologies Corp., each focusing on enhancing product efficiency, longevity, and expanding application versatility.
Market Drivers
Automotive Industry
Xenon light sources play a pivotal role in the automotive sector by significantly enhancing visibility for drivers. Compared to traditional halogen lights, xenon headlights provide superior illumination, especially in low-light conditions, ensuring safer night driving. For instance, a study highlighted that xenon headlights improve driver reaction times by up to 20% compared to halogen lights. The natural light spectrum produced by xenon lamps not only improves visibility but also enhances color perception, reducing eye strain for drivers. Additionally, these lamps boast a longer lifespan than their halogen counterparts, translating to reduced maintenance costs and greater reliability for vehicle owners, ultimately contributing to a safer driving experience.
Medical Industry
In the medical field, xenon light sources are critical for high-quality illumination during various procedures, including endoscopy and surgery. Their intense and consistent light output is essential for precise visualization, enabling healthcare professionals to perform delicate tasks with accuracy. For example, xenon lamps are used in endoscopic procedures to provide bright, white light that enhances the visibility of internal structures. Moreover, the broad spectrum of xenon light allows for accurate color rendition, which is crucial for effective diagnosis and treatment. This characteristic ensures that medical practitioners can assess tissues and conditions more accurately, thereby enhancing patient outcomes and the overall quality of care.
Projection Systems
Xenon lamps are integral to high-performance projection systems, offering bright and vibrant images that are ideal for large-screen displays and presentations. The high-intensity light produced by these lamps ensures that visuals are sharp and clear, enhancing the overall viewing experience. Furthermore, the broad spectrum of xenon light guarantees accurate color reproduction, which is vital for applications where color fidelity is essential, such as in film screenings and educational environments. This capability positions xenon lamps as a preferred choice in both commercial and educational settings.
Scientific Research
In scientific research, xenon light sources serve multiple purposes, notably in spectroscopy, where they are used to analyze the composition of materials through their interaction with light. These lamps are adept at simulating natural sunlight, allowing researchers to study the effects of sunlight on various materials and processes. This capability is particularly valuable in environmental studies and material sciences, where understanding light interaction is crucial. By providing consistent and accurate light sources, xenon lamps facilitate groundbreaking research and innovation across diverse scientific fields.
Market Trends
Emerging Trends in the Automotive and Medical Industries
Xenon lights are increasingly favored in the automotive industry, particularly in high-end vehicles, thanks to their exceptional brightness and color rendering capabilities. As consumers demand enhanced lighting for both safety and aesthetics, manufacturers are integrating xenon technology into premium models. Additionally, the automotive sector is exploring hybrid lighting systems that combine LED and xenon technologies to optimize performance and efficiency. This trend reflects the industry's commitment to innovation and the desire to provide drivers with cutting-edge lighting solutions. In the medical field, xenon lamps remain essential for procedures requiring high-quality illumination and precise color accuracy, such as endoscopy and surgery. As medical devices evolve, there is a growing trend toward miniaturization, leading to smaller and more compact xenon light sources that can be integrated into portable medical devices. This evolution enables healthcare providers to maintain the high standards of illumination necessary for effective diagnostics and treatments in increasingly mobile environments.
Developments in Projection Systems and Scientific Research
In the realm of projection systems, xenon lamps continue to be integral to high-performance projectors, particularly in cinemas and large-scale displays. Their ability to deliver vibrant images makes them a preferred choice for these applications. For instance, xenon lamps are widely used in cinema projectors due to their ability to produce bright, evenly distributed light that closely mimics natural daylight. However, there is a noticeable transition toward laser technology, which offers advantages such as higher brightness, longer lifespan, and improved color accuracy. As this trend gains traction, it poses a competitive challenge for traditional xenon lighting solutions. In scientific research, xenon lamps play a crucial role in spectroscopy and analytical instruments, thanks to their stable and broad-spectrum light output. Despite the increasing adoption of LED-based light sources in some scientific applications, xenon lamps still hold significant advantages in specific areas where high-quality illumination is paramount. The ability to produce consistent and reliable light makes them indispensable for precise measurements and analyses.
Market Challenges Analysis
Challenges in Energy Consumption and Manufacturing Complexity
One of the primary challenges facing xenon light sources is their high energy consumption, which significantly increases operational costs. This concern is particularly acute in applications such as automotive and general lighting, where energy efficiency is paramount. For instance, surveys from the automotive industry highlight that the substantial energy requirements of xenon lamps not only lead to higher utility expenses but also hinder their adoption in sectors increasingly focused on sustainability. As consumers and industries alike prioritize energy-efficient solutions, the inherent inefficiency of xenon technology presents a significant barrier to its broader market appeal. Additionally, the manufacturing process for xenon lamps is relatively complex and requires specialized equipment, leading to elevated production costs. This complexity can create potential supply chain disruptions, making it difficult for manufacturers to respond swiftly to market demands. As production costs rise, the competitive pricing of alternative lighting technologies, such as LEDs, further exacerbates the challenges faced by xenon lamp manufacturers.
Environmental Concerns and Market Competition
Environmental impact poses another significant challenge for xenon lamps, primarily due to the presence of hazardous materials within their construction. The disposal of xenon lamps can lead to environmental risks, prompting stricter regulations in many regions. These regulations may further limit the application of xenon technology, forcing manufacturers to rethink their product lifecycle management strategies. As a result, addressing these environmental concerns is crucial for maintaining market viability and compliance with regulatory standards. Moreover, xenon lamps are increasingly facing stiff competition from LED technology, which has rapidly advanced to offer more efficient, cost-effective, and environmentally friendly lighting solutions. LEDs not only consume less energy but also boast longer lifespans and improved color rendering capabilities, making them a formidable competitor in numerous applications. The niche market focus of xenon lamps, which primarily cater to high-end automotive lighting, medical devices, and scientific research, also constrains their overall growth and profitability. To thrive in this competitive landscape, manufacturers must improve energy efficiency, streamline production processes, and implement sustainable practices while exploring opportunities for hybrid lighting solutions that leverage the strengths of both xenon and LED technologies.
Market Segmentation Analysis:
By Type:
The xenon light source market is segmented by type into long arc and short arc xenon light sources. Long arc xenon lamps, known for their extended illumination, are primarily utilized in applications requiring steady, prolonged lighting such as theater projectors and industrial lighting. Their high intensity and broad light spectrum make them ideal for settings where visual clarity and accurate color rendering are essential. Short arc xenon lamps, on the other hand, deliver concentrated, intense lighting and are commonly used in applications that need high-intensity focused light, such as in research laboratories and scientific instruments. The precise and consistent light output of short arc xenon lamps supports critical tasks in research and medical applications where accuracy and reliability are paramount.
By Application:
Xenon light sources find diverse applications across various sectors, including theaters, searchlights, industry, and research. In theaters, xenon lamps provide superior brightness and color accuracy, enhancing the viewing experience with clear, vibrant images. Searchlights also benefit from xenon lighting’s intense output, enabling powerful beams that can penetrate long distances, making them suitable for outdoor events and emergency response. Industrial applications leverage xenon lamps for tasks requiring robust, reliable lighting, often used in equipment where consistency is crucial. In the research sector, xenon light sources serve as key components in scientific instruments, providing stable, accurate lighting needed for precise measurements and analyses in fields such as spectroscopy and photonics.
Segments:
Based on Type:
- Long Arc Xenon Light Source
- Short Arc Xenon Light Source
Based on Application:
- Theaters
- Searchlights
- Industry
- Research
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America commands approximately 35% of the global xenon light source market share, driven by robust demand across automotive, healthcare, and entertainment sectors. The U.S., in particular, leads in adoption, benefiting from technological advancements and an established infrastructure supporting medical and scientific research applications. High-end automotive manufacturers in the region heavily incorporate xenon lamps, capitalizing on their superior brightness and color rendering for premium vehicles. Additionally, the region’s focus on quality illumination in surgical lighting and projection systems strengthens its market share, with continuous investments in R&D further enhancing xenon light source efficiency and application versatility.
Asia-Pacific
Asia-Pacific accounts for around 30% of the global xenon light source market, marked by rapid growth driven by the automotive and industrial sectors in China, Japan, and India. The region’s expanding production of high-end vehicles increasingly integrates xenon lamps, meeting rising consumer expectations for advanced lighting. Industrial and research applications also see heightened demand as Asia-Pacific bolsters scientific development capabilities. Economic growth, a large population base, and a vibrant entertainment industry fuel this demand, particularly for theaters and large-scale venues. As the region enhances its manufacturing efficiency and infrastructure, its share in the xenon light source market is expected to grow further.
Key Player Analysis
- Asahi Spectra USA, Inc
- Avantes BV
- Cogentix Medical, Inc (LABORIE Medical Technologies)
- Excelitas Technologies Corp.
- Hamamatsu Photonics K.K.
- KARL STORZ SE & Co. KG
- Ocean Optics, Inc
- Olympus Medical Systems (Olympus Corporation)
- SOPRO-COMEG GmbH
- Smith & Nephew Plc
- Stryker Corporation
Competitive Analysis
The xenon light source market is highly competitive, with major players like Hamamatsu Photonics K.K., KARL STORZ SE & Co. KG, Stryker Corporation, Asahi Spectra USA, Inc., Olympus Medical Systems, Ocean Optics, Inc., and Excelitas Technologies Corp. leading through innovation and targeted applications. These companies focus on enhancing xenon light intensity, lifespan, and energy efficiency, especially in specialized sectors such as medical devices, automotive lighting, and scientific research. Continuous investment in R&D enables these leaders to adapt to industry shifts, including competition from LED technology and environmental regulations. By diversifying their product offerings, such as integrating hybrid lighting solutions or miniaturizing light sources for portable devices, these players maintain competitive positioning and cater to a range of high-demand applications. Additionally, expansion in emerging markets and strategic partnerships strengthen their global footprint and sustain market share amidst evolving consumer needs and regulatory landscapes.
Market Concentration & Characteristics
The xenon light source market is moderately concentrated, with a few prominent players dominating significant market share due to the specialized applications and technical requirements of the technology. Leading companies such as Hamamatsu Photonics, KARL STORZ, and Stryker Corporation leverage their expertise and advanced R&D capabilities to deliver high-performance, reliable xenon lighting solutions across automotive, medical, and industrial sectors. The market is characterized by the need for high capital investment and complex manufacturing processes, which create high entry barriers for new entrants. Additionally, product differentiation is essential, as end-users seek specific attributes like brightness, color fidelity, and durability for applications that demand precise lighting solutions. Despite growing competition from LEDs, xenon light sources remain preferred in applications requiring high-intensity, continuous light with natural color rendering. Companies in this space emphasize innovation, application-specific advancements, and strategic alliances to sustain their competitive edge and address evolving customer needs.Top of Form
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The xenon light source market is anticipated to see steady demand in niche sectors despite growing competition from LED technology.
- Advancements in xenon lamp technology are expected to enhance energy efficiency, catering to environmentally conscious industries.
- Medical applications will likely remain a strong market segment, particularly for endoscopy and surgical lighting requiring high-quality illumination.
- The automotive sector is expected to continue utilizing xenon lamps in high-end vehicles due to their superior brightness and color rendering.
- Hybrid lighting systems that integrate xenon with LED may emerge to balance performance and energy efficiency in various applications.
- Demand for compact xenon light sources may increase to meet the needs of portable and specialized equipment across industries.
- Scientific research, particularly in spectroscopy and material analysis, will continue to rely on xenon lamps for their stable and broad-spectrum light.
- Stricter environmental regulations could lead to an emphasis on sustainable practices in xenon lamp production and disposal.
- Emerging markets in Asia-Pacific are expected to provide growth opportunities due to industrial and technological advancements.
- Market players will likely focus on R&D to improve product lifespan and reduce maintenance costs, enhancing xenon’s competitiveness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Automotive Lighting Advancements
Xenon light sources are increasingly used in high-end automotive lighting due to their superior brightness, color rendering, and longer lifespan compared to halogen lamps, enhancing driver safety and reducing maintenance costs.
Medical Device Integration
The demand for high-quality, consistent illumination in medical procedures such as endoscopy and surgery drives adoption of xenon light sources, as their broad spectrum and color accuracy are critical for precise diagnostics and treatment.
Growth in Projection and Entertainment Applications
Xenon lamps remain the preferred choice for theaters and large-scale projection systems, offering intense, evenly distributed light and accurate color reproduction, which are essential for high-quality visual experiences.
Expansion in Scientific Research
Xenon light sources are vital in spectroscopy and analytical instruments, providing stable, broad-spectrum light necessary for accurate material analysis and research, supporting innovation in scientific fields.
Technological Innovation and Hybrid Systems
Ongoing R&D is leading to more energy-efficient and compact xenon lamps, as well as hybrid lighting systems that combine xenon and LED technologies, expanding application versatility and addressing energy consumption concerns.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the size of Xenon Light Source Market?
What factors are driving the growth of the Xenon Light Source market?
What are the key segments within the Xenon Light Source market?
Who are the major players in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Long Arc Xenon Light Source
- 1.2.2 Short Arc Xenon Light Source
- 1.3 By Application
- 1.3.1 Theaters
- 1.3.2 Searchlights
- 1.3.3 Industry
- 1.3.4 Research
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,465 million → 2032: USD 4,389.35 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Xenon Light Source Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Xenon Light Source Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Xenon Light Source Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Xenon Light Source Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Xenon Light Source Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Xenon Light Source Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Xenon Light Source Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Xenon Light Source Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,465 million → 2032: USD 4,389.35 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Xenon Light Source Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Long Arc Xenon Light Source
- 12.3.7.2 Short Arc Xenon Light Source
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Theaters
- 12.4.7.2 Searchlights
- 12.4.7.3 Industry
- 12.4.7.4 Research
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Xenon Light Source End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Xenon Light Source Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Xenon Light Source Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Xenon Light Source Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Hamamatsu Photonics K.K.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 KARL STORZ SE & Co. KG
- 18.4 Stryker Corporation
- 18.5 Asahi Spectra USA, Inc.
- 18.6 Olympus Medical Systems
- 18.7 Ocean Optics, Inc.
- 18.8 Excelitas Technologies Corp.
- 18.9 Smith & Nephew Plc
- 18.10 Avantes BV
- 18.11 Cogentix Medical, Inc (LABORIE Medical Technologies)
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

