
Automotive Braking System Market Overview:
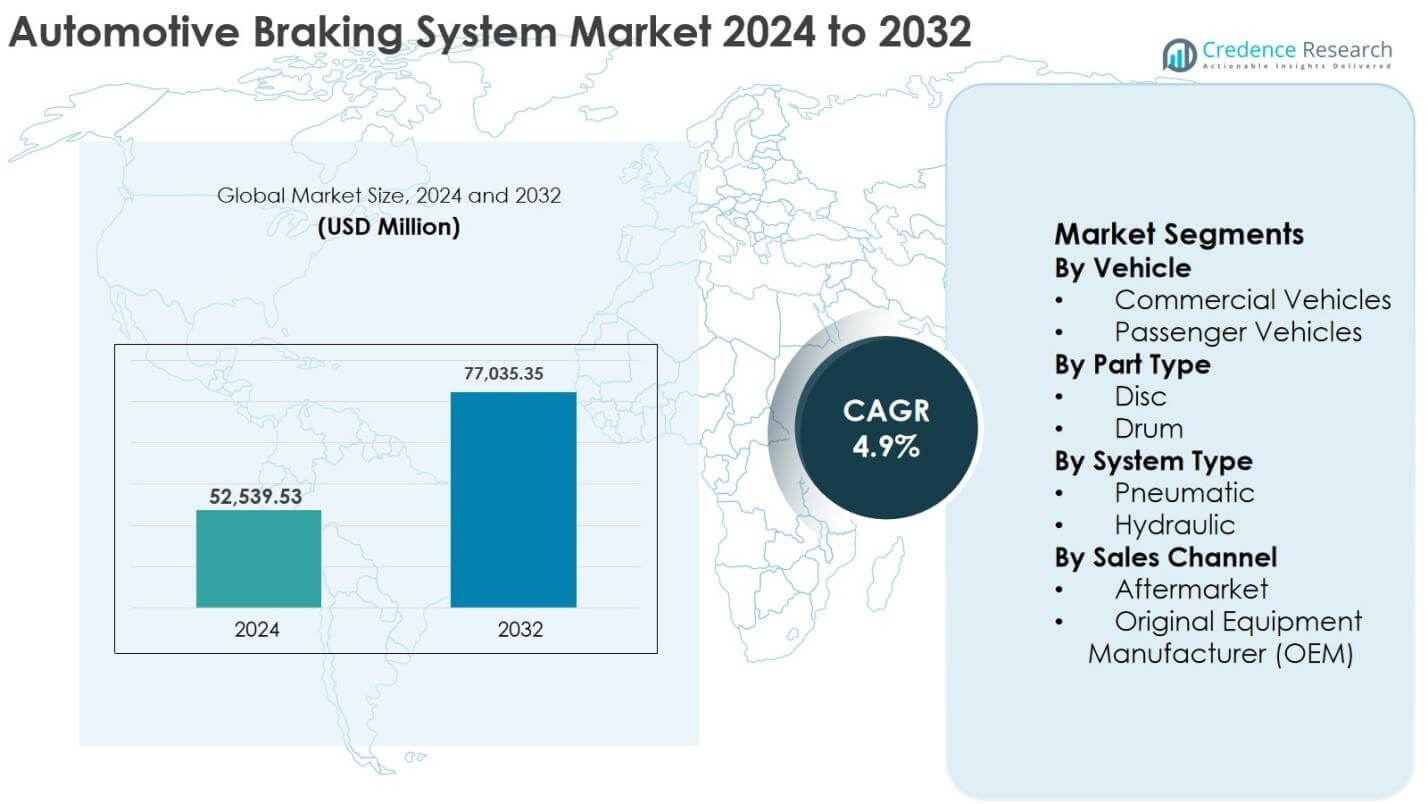
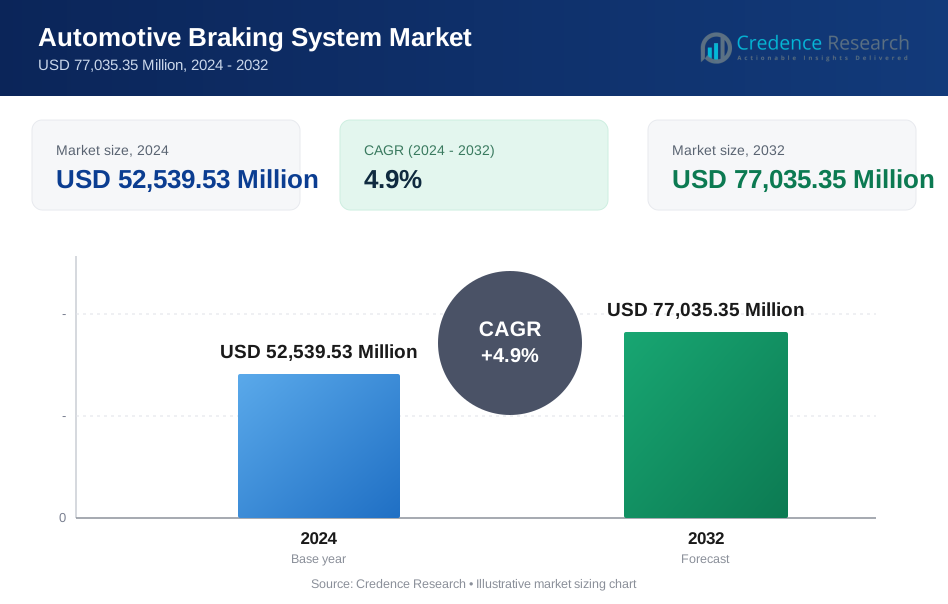
Automotive Braking System market size was valued USD 52,539.53 Million in 2024 and is anticipated to reach USD 77,035.35 Million by 2032, at a CAGR of 4.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Automotive Braking System Market Size 2024 | USD 52,539.53 million |
| Automotive Braking System Market, CAGR | 4.9% |
| Automotive Braking System Market Size 2032 | USD 77,035.35 million |
Automotive Braking System Market Insights
- Market overview highlights steady demand from passenger vehicles, which held a dominant 61.3% share in 2024, supported by rising safety awareness, increasing vehicle production, and regulatory mandates for ABS, ESC, and advanced hydraulic braking technologies across global markets.
- Market drivers include the growing adoption of electric and hybrid vehicles, integration of brake-by-wire and regenerative braking systems, and continuous technological advancements that enhance braking performance, energy efficiency, and driving stability in high-performance and urban mobility segments.
- Market trends and competitive analysis indicate strong participation from key players such as Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, AISIN Seiki, Brembo S.p.A., and Hyundai Mobis, with companies focusing on R&D, lightweight components, and ADAS-linked braking solutions.
- Regional analysis shows Asia-Pacific leading the market with 38.9% share in 2024, followed by North America with 26.8% and Europe with 24.6%, while Latin America and Middle East & Africa together account for the remaining share, driven by gradual safety upgrades and fleet expansion.
Automotive Braking System Market Segmentation Analysis:
By Vehicle
The Automotive Braking System market by vehicle segment is dominated by Passenger Vehicles, accounting for 61.3% share in 2024, driven by rising urban mobility, increasing passenger car production, and strong demand for safety-enhanced vehicles across Asia-Pacific and Europe. Manufacturers increasingly integrate ABS, EBD, and ESC technologies to meet regulatory mandates and consumer safety expectations, further strengthening adoption in sedans, SUVs, and compact cars. Commercial Vehicles hold the remaining 38.7% share, supported by growth in logistics and freight transport, where fleet operators invest in durable braking systems to improve road safety and operational efficiency.
- For instance, Hyundai Motor offers ESC and ABS as standard across most trims of the Hyundai Creta and i20 in India and other Asia-Pacific markets, in line with evolving safety norms
By Part Type
Within the Automotive Braking System market by part type, Disc Brakes represent the dominant sub-segment with a 68.5% market share in 2024, driven by the increasing penetration of high-performance vehicles, rising consumer preference for superior stopping efficiency, and regulatory emphasis on advanced braking technologies. Disc brakes offer enhanced heat dissipation, shorter braking distances, and better performance in high-speed conditions, supporting their widespread adoption across passenger vehicles and premium vehicle platforms. Drum Brakes account for 31.5% share, remaining relevant in cost-sensitive markets and rear-axle installations due to lower manufacturing and maintenance costs.
- For instance, Tesla equips the Model 3 and Model Y with ventilated disc brakes on both front and rear axles to manage repeated high-speed braking.
By System Type
The Automotive Braking System market by system type is led by Hydraulic Braking Systems, which captured 72.4% share in 2024, owing to their extensive use in passenger cars and light commercial vehicles, high reliability, and compatibility with ABS and emerging brake-by-wire technologies. Growth is further accelerated by rising vehicle production and continuous advancements in hydraulic actuation efficiency. Pneumatic Braking Systems account for 27.6% share, primarily driven by heavy commercial vehicles and buses, where high load capacity and strong braking force are essential to support logistics expansion and long-haul transportation demand.
Key Growth Drivers
Stringent Safety Regulations and Mandatory Advanced Braking Technologies
Global automotive safety regulations continue to tighten, compelling automakers to integrate advanced braking technologies such as ABS, ESC, EBD, and brake-assist systems across vehicle platforms. Governments in Europe, North America, and Asia-Pacific increasingly enforce safety compliance standards for both passenger and commercial vehicles, accelerating the transition from conventional braking systems to technology-enhanced solutions. Growing emphasis on reducing road accidents, improving vehicular stability, and enhancing pedestrian safety further strengthens system adoption. Automakers collaborate with braking system suppliers to meet certification norms while optimizing cost and performance. The proliferation of electric and hybrid vehicles also drives demand for regenerative and electronically controlled braking systems, expanding innovation opportunities. Fleet owners, logistics providers, and ride-sharing operators prioritize safety-enhanced braking to minimize downtime and liability risks. Together, these regulatory mandates and safety-centric buying behaviors act as a major catalyst for sustained growth in the Automotive Braking System market.
- For instance, the European Union mandates ESC on all new passenger cars and light commercial vehicles under UNECE Regulation No. 140, pushing OEMs to standardize electronic stability systems.
Rising Vehicle Production and Expanding Urban Mobility Demand
The steady growth in global vehicle production, particularly in emerging markets across Asia-Pacific, Latin America, and parts of Africa, significantly fuels demand for braking systems. Rapid urbanization, expanding middle-class consumer bases, and increasing disposable incomes stimulate higher passenger car ownership, while industrial growth boosts commercial vehicle deployment in logistics, construction, and public transportation sectors. Ride-hailing services, last-mile delivery fleets, and urban mobility platforms further contribute to vehicle utilization intensity, necessitating robust and reliable braking solutions. Manufacturers invest in localized production facilities to improve supply-chain efficiency and reduce system costs, supporting mass-market adoption. Additionally, consumer expectations for smoother driving experiences and enhanced braking comfort reinforce technology upgrades. As smart mobility and connected transportation ecosystems evolve, braking systems increasingly integrate intelligent sensors and control interfaces, strengthening long-term market momentum driven by sustained vehicle fleet expansion worldwide.
- For instance, India’s passenger vehicle production exceeded 4.5 million units in FY 2023–24 (SIAM), with strong output from OEMs such as Maruti Suzuki, Hyundai, and Tata Motors, all relying on large‑scale braking system sourcing.
Technological Advancements and Adoption of Electrification and Brake-by-Wire Systems
Rapid technological advancements significantly transform braking architectures, with innovations such as brake-by-wire, regenerative braking, ADAS-integrated braking, and electronic stability enhancements gaining traction across modern vehicles. Electrification trends in hybrid and battery-electric vehicles increase reliance on sophisticated braking control modules that optimize energy recovery and braking efficiency. The integration of sensors, actuators, and electronic control units enhances precision, responsiveness, and diagnostics capability, supporting predictive maintenance and improved vehicle safety performance. Automakers collaborate with technology partners to develop modular braking platforms adaptable across multiple vehicle variants, enabling scalability and cost optimization. Continuous R&D investments drive material innovations such as lightweight calipers and advanced friction components that improve thermal stability and braking durability. These advancements strengthen braking reliability in high-performance, autonomous-ready, and premium mobility platforms, positioning technology evolution as a critical growth enabler for the Automotive Braking System market.
Key Trends & Opportunities
Integration of Braking Systems with ADAS, Autonomous Driving, and Connected Vehicle Platforms
A major industry trend involves the integration of braking systems with ADAS features such as automatic emergency braking, collision avoidance, lane-keeping support, and adaptive cruise control. As vehicles progress toward higher levels of automation, braking systems evolve into intelligent safety control modules capable of real-time decision-making through sensor fusion and AI-driven algorithms. Connected vehicle ecosystems enable over-the-air diagnostics, remote monitoring, and predictive maintenance, creating opportunities for service-based revenue models. The development of coordinated braking with steering and traction systems enhances stability control and vehicle handling in complex driving environments. This convergence of electronics, software, and braking hardware opens new innovation pathways and allows suppliers to position braking systems as core components within next-generation mobility platforms, reinforcing long-term market opportunity.
- For instance, Mercedes-Benz’s Active Brake Assist and Volvo’s City Safety systems use radar and camera inputs to trigger automatic emergency braking to help prevent or mitigate frontal collisions.
Growing Demand for Lightweight, Energy-Efficient, and Sustainable Braking Components
Automakers increasingly prioritize lightweight and energy-efficient braking components to support fuel efficiency, emissions reduction, and vehicle range improvement in electric models. Advanced materials such as aluminum calipers, carbon-ceramic rotors, and low-copper friction materials gain momentum due to enhanced durability and thermal resistance. Sustainability initiatives encourage manufacturers to adopt environmentally responsible manufacturing processes and eco-compliant brake pad formulations that minimize particulate emissions and road dust. Lightweight braking assemblies also contribute to performance optimization in premium and sports vehicles, creating additional product differentiation opportunities. Supplier investments in green manufacturing, recyclable components, and lifecycle-optimized braking solutions strengthen alignment with corporate ESG objectives and regulatory expectations, positioning sustainable braking technologies as an expanding opportunity segment in the Automotive Braking System market.
- For instance, Brembo supplies aluminum brake calipers and lightweight disc solutions for high-performance and EV platforms, helping OEMs cut weight and improve efficiency.
Key Challenges
Rising Cost Pressures, Pricing Competition, and OEM Margin Constraints
The Automotive Braking System market faces growing cost pressures driven by fluctuating raw material prices, increasing electronic component integration, and continuous regulatory compliance requirements. OEMs seek cost-optimized braking solutions without compromising safety or performance, challenging suppliers to balance innovation investments with competitive pricing. Intense market competition from global and regional manufacturers further compresses margins, particularly in cost-sensitive and mass-production vehicle segments. Supply-chain disruptions, semiconductor shortages, and logistics constraints add uncertainty to production planning and delivery timelines. Additionally, scaling advanced braking technologies across entry-level vehicles remains difficult due to affordability barriers, creating structural pricing challenges for industry participants.
Thermal Management, Durability, and Performance Challenges in High-Load and EV Applications
Braking systems increasingly operate under demanding conditions due to heavier electric vehicle architectures, higher torque output, and intensive stop-start urban driving cycles. These conditions intensify heat generation, friction wear, and component fatigue, posing challenges in thermal management and long-term durability. Maintaining braking performance while supporting regenerative braking coordination requires sophisticated calibration and materials engineering. In commercial vehicles, frequent heavy-load operations accelerate component degradation, requiring advanced wear-resistant solutions and stronger compliance testing. Failure risks in safety-critical braking applications create substantial reliability, liability, and certification challenges for manufacturers. Addressing these technical complexities remains essential to ensuring performance consistency and user safety across evolving mobility environments.
Regional Analysis
North America
North America holds a significant position in the Automotive Braking System market, accounting for 26.8% share in 2024, supported by strong adoption of advanced safety technologies and regulatory mandates emphasizing ABS, ESC, and autonomous emergency braking in passenger and commercial vehicles. The United States leads regional demand due to high vehicle production, expanding EV penetration, and increasing integration of brake-by-wire and ADAS-linked braking systems. Growth is further reinforced by technological innovation, premium vehicle sales, and investments in intelligent mobility solutions. Canada and Mexico contribute through manufacturing expansion and OEM–supplier collaborations focused on performance-enhanced braking architectures.
Europe
Europe accounted for 24.6% share in 2024 in the Automotive Braking System market, driven by stringent safety legislation, strong presence of premium automobile manufacturers, and rapid electrification across Germany, France, Italy, and the United Kingdom. The region emphasizes lightweight braking materials, regenerative braking integration, and ESG-aligned component manufacturing. Adoption of ADAS-compatible and autonomous-ready braking solutions continues to accelerate, particularly in electric and hybrid vehicle platforms. Increasing investments in R&D, high consumer safety awareness, and the expansion of advanced braking applications in luxury and performance vehicles strengthen Europe’s position as a technology-driven growth hub.
Asia-Pacific
Asia-Pacific dominates the Automotive Braking System market with the largest share of 38.9% in 2024, propelled by high vehicle production volumes, rapid urbanization, and rising passenger car ownership across China, India, Japan, and South Korea. Government safety regulations, expanding middle-class consumer demand, and the growing penetration of EVs and compact SUVs drive large-scale adoption of hydraulic, disc, and ABS-integrated braking systems. Localized manufacturing, cost-efficient supply chains, and increasing technological partnerships with global suppliers further accelerate market expansion. The region continues to evolve as the primary production and consumption base for advanced and mass-market braking solutions.
Latin America
Latin America captured 5.4% share in 2024 in the Automotive Braking System market, supported by gradual improvements in vehicle safety standards and increasing adoption of ABS and hydraulic braking systems in Brazil, Mexico, and Argentina. Growth is influenced by expanding commercial vehicle fleets, infrastructure development, and demand for durable braking components suited to challenging operating conditions. Although cost sensitivity remains high, OEMs and suppliers increasingly invest in localized assembly and aftermarket solutions. Rising urban mobility trends, along with policy-driven safety enhancements, are expected to strengthen the region’s shift toward more reliable and technology-integrated braking systems.
Middle East & Africa
The Middle East & Africa region accounted for 4.3% share in 2024 in the Automotive Braking System market, driven by growing vehicle parc expansion, infrastructure investments, and increasing penetration of SUVs, light commercial vehicles, and fleet transport applications. Demand is supported by the need for robust braking systems capable of operating in high-temperature and off-road environments. Gulf economies adopt higher-end braking technologies through premium and luxury vehicle sales, while African markets focus on affordable, durable hydraulic and drum-brake solutions. Gradual road safety awareness and aftermarket modernization initiatives continue to create steady development opportunities across the region.
Automotive Braking System Market Segmentations:
By Vehicle
- Commercial Vehicles
- Passenger Vehicles
By Part Type
- Disc
- Drum
By System Type
- Pneumatic
- Hydraulic
By Sales Channel
- Aftermarket
- Original Equipment Manufacturer (OEM)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Automotive Braking System market features a strong presence of global Tier-1 suppliers and technology specialists that compete on product innovation, safety performance, reliability, and integration with electronic and ADAS-enabled vehicle platforms. Leading players such as Continental AG, Robert Bosch GmbH, ZF Friedrichshafen AG, Hyundai Mobis, AISIN Seiki, Brembo S.p.A., Akebono Brake Industry Co., Ltd., WABCO, Hitachi Ltd., and Mando Corporation focus on expanding portfolios that include hydraulic braking, disc and drum systems, brake-by-wire solutions, regenerative braking for EVs, and lightweight friction components. Companies invest heavily in R&D, strategic partnerships with automakers, and regional manufacturing footprints to enhance cost efficiency and customization for vehicle platforms across passenger and commercial segments. The market also reflects growing differentiation through software-driven braking controls, electronic stability integration, and performance materials, while mergers, collaborations, and aftermarket expansion strengthen supplier positioning in both mature and emerging automotive markets.
Key Player Analysis
- Continental AG
- Hyundai Mobis
- AISIN SEIKI
- Brembo S.p.A
- Hitachi Ltd.
- Robert Bosch GmbH
- Akebono Brake Industry Co., Ltd.
- WABCO
- ZF Friedrichshafen AG
- Mando Corporation
Recent Developments
- In December 2025, Brakes India acquired a 10% stake in Japan’s TBK Co, forming a strategic alliance to expand its commercial vehicle braking systems and global exports.
- In June 2025, Mutares signed an agreement to acquire Continental’s drum brakes production and R&D location in Cairo Montenotte, Italy, strengthening its automotive segment, expected to close in Q4 2025.
- In March 2025, Lippert (CURT portfolio) acquired RVibrake, a flat tow brake systems company that pioneered an Auto-Positioning brake system for towing applications.
Report Coverage
The research report offers an in-depth analysis based on Vehicle, Part Type, System Type, Sales Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will experience steady growth as automakers continue to integrate advanced safety and braking technologies across passenger and commercial vehicles.
- Electrification will accelerate the adoption of regenerative braking and electronic brake control systems in hybrid and battery-electric vehicles.
- Brake-by-wire and software-defined braking architectures will gain wider acceptance as vehicles move toward higher levels of automation.
- Lightweight braking materials and components will see increased use to improve energy efficiency and vehicle performance.
- ADAS-linked braking functions such as automatic emergency braking and collision avoidance will become standard in more vehicle segments.
- Suppliers will expand investments in R&D, digital diagnostics, and predictive maintenance capabilities for braking systems.
- Emerging markets will generate strong demand due to rising vehicle production, urban mobility expansion, and evolving safety regulations.
- OEM–supplier collaborations will intensify to co-develop modular and platform-scalable braking solutions.
- Aftermarket upgrades and replacement demand will remain strong as global vehicle fleets continue to expand.
- Sustainability initiatives will encourage greater adoption of eco-compliant friction materials and low-emission braking technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Safety Regulations and Mandatory Advanced Braking Technologies
Global regulatory mandates for ABS, ESC, and other advanced braking systems are compelling automakers to integrate these technologies across both passenger and commercial vehicles, accelerating the shift from conventional to technology-enhanced braking solutions.
Rising Vehicle Production and Expanding Urban Mobility
Increasing vehicle production, especially in Asia-Pacific and emerging markets, along with rapid urbanization and higher car ownership, is driving demand for robust and reliable braking systems to support growing fleets and urban mobility needs.
Technological Advancements and Electrification
The adoption of brake-by-wire, regenerative braking, and ADAS-integrated systems is transforming braking architectures, particularly in electric and hybrid vehicles, enhancing performance, energy efficiency, and enabling new safety features.
Integration with ADAS and Autonomous Driving
Braking systems are increasingly integrated with ADAS features such as automatic emergency braking and collision avoidance, making them critical components in the evolution toward autonomous and connected vehicles.
Demand for Lightweight and Sustainable Components
Automakers are prioritizing lightweight, energy-efficient, and eco-friendly braking components to improve fuel efficiency, reduce emissions, and meet sustainability goals, driving innovation in materials and manufacturing processes.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Automotive Braking System Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Automotive Braking System Market projected to grow between 2024 and 2032?
Which Automotive Braking System Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Automotive Braking System Market?
Who are the leading companies in the Automotive Braking System Market?
Which region commanded the largest share of the Automotive Braking System Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Vehicle
- 1.2.1 Passenger Vehicles
- 1.2.2 Commercial Vehicles
- 1.3 By Part Type
- 1.3.1 Disc Brakes
- 1.3.2 Drum Brakes
- 1.4 By System Type
- 1.4.1 Hydraulic Braking Systems
- 1.4.2 Pneumatic Braking Systems
- 1.5 By Sales Channel
- 1.5.1 Original Equipment Manufacturer (OEM)
- 1.5.2 Aftermarket
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 52,539.53 Million → 2032: USD 77,035.35 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Braking System Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Braking System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Braking System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Braking System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Braking System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Braking System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Braking System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Braking System Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 52,539.53 Million → 2032: USD 77,035.35 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Braking System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Vehicle - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Passenger Vehicles
- 12.3.7.2 Commercial Vehicles
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Part Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Disc Brakes
- 12.4.7.2 Drum Brakes
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By System Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hydraulic Braking Systems
- 12.5.7.2 Pneumatic Braking Systems
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Sales Channel - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Original Equipment Manufacturer (OEM)
- 12.6.7.2 Aftermarket
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Braking System Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Automotive Braking System Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Automotive Braking System Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Continental AG
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Robert Bosch GmbH
- 17.4 ZF Friedrichshafen AG
- 17.5 Hyundai Mobis
- 17.6 AISIN Seiki
- 17.7 Brembo S.p.A.
- 17.8 Akebono Brake Industry Co., Ltd.
- 17.9 WABCO
- 17.10 Hitachi Ltd.
- 17.11 Mando Corporation
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

