
Market Overview
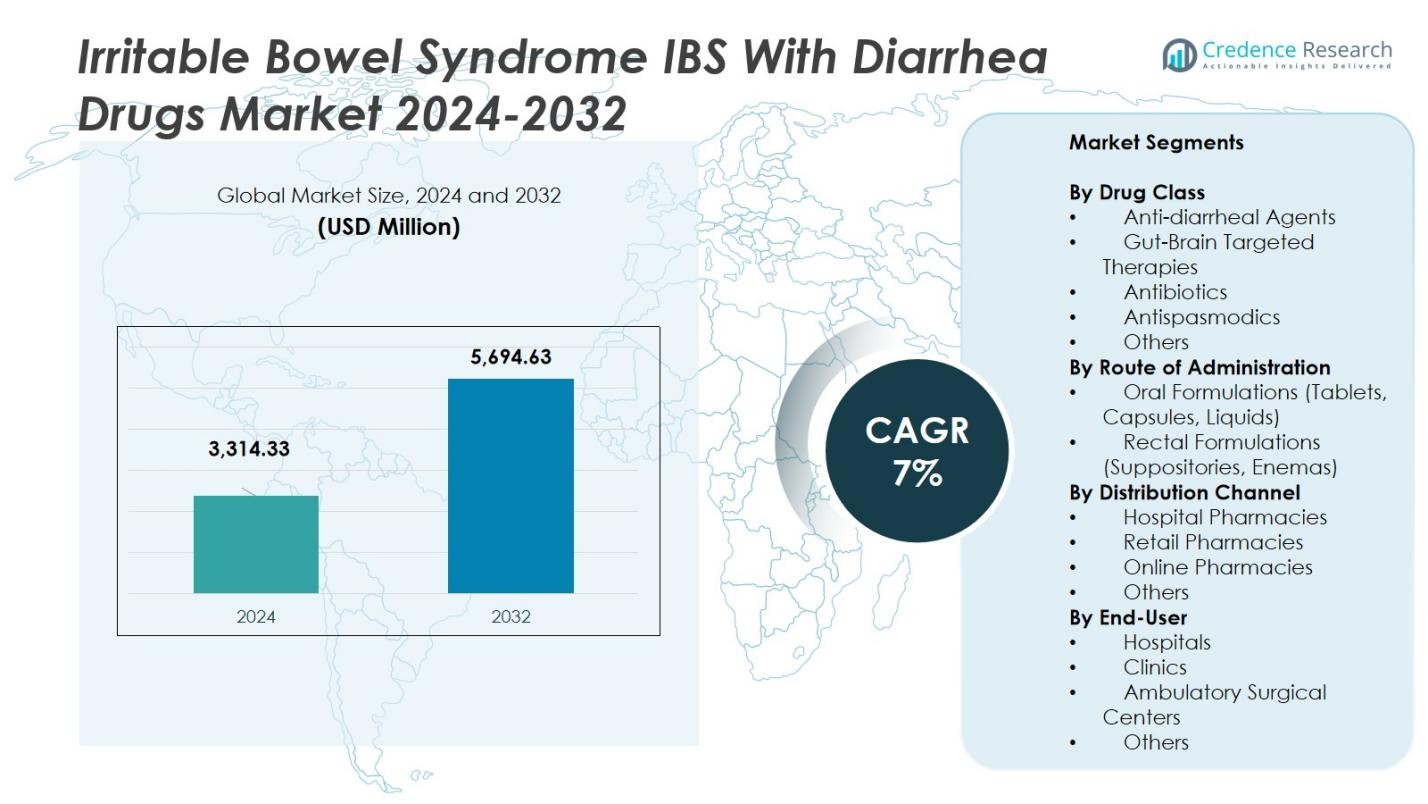
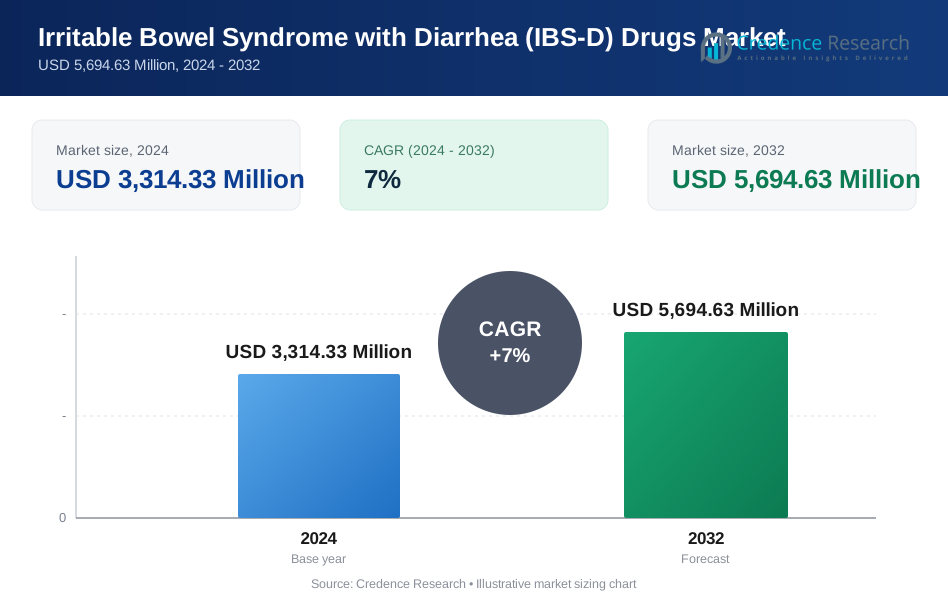
The Irritable Bowel Syndrome (IBS) with Diarrhea Drugs Market size was valued at USD 3,314.33 Million in 2024 and is anticipated to reach USD 5,694.63 Million by 2032, at a CAGR of 7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Irritable Bowel Syndrome (IBS) with Diarrhea Drugs Market Size 2024 | USD 3,314.33 Million |
| Irritable Bowel Syndrome (IBS) with Diarrhea Drugs Market, CAGR | 7% |
| Irritable Bowel Syndrome (IBS) with Diarrhea Drugs Market Size 2032 | USD 5,694.63 Million |
TheIrritable Bowel Syndrome (IBS with Diarrhea Drugs Market features leading players such asBausch Health Companies (Salix Pharmaceuticals), Ironwood Pharmaceuticals, Allergan (AbbVie), Sebela Pharmaceuticals, RedHill Biopharma, Ardelyx, Alnylam Pharmaceuticals, Mylan Pharmaceuticals, Astellas Pharma and Takeda Pharmaceutical Company. North America leads the market with a 37.5% share in 2024, driven by advanced healthcare infrastructure, high disease awareness and early therapeutic adoption. Europe follows closely, supported by strong regulatory frameworks and rising prevalence in key countries. The Asia Pacific region, growing rapidly, shows promise due to improving healthcare access, urbanisation, and increasing focus on novel therapies in markets such as China, Japan and India.
Market Insights
- The Irritable Bowel Syndrome (IBS) with Diarrhea Drugs Market was valued at USD 3,314.33 Million in 2024 and is forecasted to grow at a CAGR of 7% through 2032.
- The gut‑brain targeted therapies segment holds the largest share at around 22.6%, driven by increased understanding of the gut–brain axis in IBS‑D.
- The oral formulations route dominates with over 60% share, reflecting high patient compliance and preference for tablets and capsules.
- Major companies such as Bausch Health (Salix Pharmaceuticals), Ironwood, Allergan (AbbVie) and Takeda are leading the market, though limited approved therapies and high treatment costs restrain growth.
- Regionally, North America commands 37.5% of the market, followed by Europe, while Asia‑Pacific offers strong growth potential thanks to rising healthcare access and emerging patient demand.
Market Segmentation Analysis:
By Drug Class
Within the drug‑class segment for the Irritable Bowel Syndrome with Diarrhea (IBS‑D) drugs market, the gut‑brain targeted therapies sub‑segment currently holds the largest share, estimated at approximately 22.6% of the total. This dominance stems from growing evidence linking the gut–brain axis to IBS‑D symptoms, and the entry of targeted agents such as mixed opioid receptor modulators which address both diarrhea and abdominal pain. The rising preference for treatments beyond mere antidiarrheals those that also relieve key functional and neurological pathways is driving this sub‑segment’s growth, while broader awareness of the gut‑brain connection in gastrointestinal disorders further accelerates adoption.
- For instance, ramosetron, a serotonin 5-HT3 antagonist, has demonstrated effectiveness in relieving global IBS symptoms, including abdominal pain and abnormal bowel habits, with favorable safety outcomes observed in multiple randomized clinical trials.
By Route of Administration
In the route‑of‑administration segment, oral formulations dominate, accounting for the majority of market value (well in excess of 60% of the total). This preference reflects the convenience, widespread physician familiarity, and strong patient compliance associated with tablets, capsules and liquids. Oral delivery enables broad outpatient treatment of IBS‑D and supports high volumes of prescriptions. The ease of administration and the ability to deliver extended‑release and controlled‑release dosage forms further support the oral sub‑segment’s dominance over less convenient routes such as suppositories or enemas, which remain niche.
- For instance, RedHill Biopharma’s BEKINDA (RHB-102) is a once-daily, bimodal extended-release oral tablet of ondansetron. It showed clinically meaningful improvement in stool consistency and abdominal pain in Phase II IBS-D studies, positioning it as a promising oral treatment with a patient-friendly dosing schedule.
By Distribution Channel
For distribution channels in the IBS‑D drugs market, the hospital pharmacies channel leads with around 44.7% share of total revenue. The dominance of hospital pharmacies is driven by the concentration of specialist gastroenterology care within hospital settings, where novel therapies are frequently initiated and monitored. These settings often facilitate specialist prescribing, diagnostic confirmation, and multidisciplinary support, making them preferred for higher‑cost or newer agents. Meanwhile, retail and online channels are growing, but hospital pharmacies maintain the largest share due to their structured care environments and ability to handle complex cases.
Key Growth Drivers
Rising Prevalence of IBS-D
The increasing prevalence of IBS-D is a major driver of market growth. As lifestyle changes, stress, and dietary shifts contribute to higher diagnosis rates, more patients seek pharmaceutical treatments. This growing patient base fuels the demand for IBS-D drugs, prompting pharmaceutical companies to innovate and expand their offerings. The heightened focus on managing IBS-D symptoms effectively further accelerates market growth as healthcare providers and patients search for more targeted and efficient therapies.
- For instance, pharmaceutical companies are innovating with drugs like alosetron, a selective 5-HT3 antagonist approved specifically for IBS-D, providing targeted relief by slowing gut transit and alleviating pain.
Advancements in Targeted Therapies
Recent advancements in targeted therapies have significantly impacted the IBS-D drug market. Innovative treatments focusing on the gut-brain axis, microbiome imbalance, and neurotransmitter regulation are gaining traction. These therapies offer improved efficacy by addressing the root causes of IBS-D rather than just managing symptoms. With the increasing availability of such therapies, both patients and healthcare providers are more inclined to adopt them, leading to greater market penetration and sustained growth in the IBS-D segment.
- For instance, Rifaximin, a gut-selective antibiotic, reduces IBS-D symptoms by altering the intestinal microbiota, with documented efficacy shown in two Phase 3 clinical trials.
Improved Diagnosis and Awareness
Rising awareness among both patients and clinicians is driving growth in the IBS-D drug market. Better diagnostic tools and increased understanding of IBS-D contribute to earlier and more accurate diagnoses. With healthcare systems becoming more adept at identifying and treating IBS-D, the market sees an uptick in the prescription of effective drugs. The heightened focus on IBS-D and its management encourages both physicians and patients to actively seek therapeutic options, further promoting market expansion.
Key Trends & Opportunities
Personalised Medicine and Biomarkers
prominent trend in the IBS-D drug market is the move towards personalised medicine. The use of biomarkers and individual patient profiles to tailor treatments is gaining momentum. This approach promises higher treatment efficacy, fewer side effects, and better overall patient outcomes. By developing therapies that are customized to an individual's specific condition, pharmaceutical companies can distinguish their products in a crowded market, creating significant opportunities for growth and innovation.
- For instance, Alosetron, a 5-HT3 antagonist approved for severe IBS-D in the US, shows higher efficacy in women with specific symptom profiles, demonstrating targeted therapy based on patient characteristics.
Expansion in Emerging Markets
Emerging markets present a significant growth opportunity for the IBS-D drug market. With increasing healthcare access and awareness in regions like Asia-Pacific, pharmaceutical companies are finding new avenues for growth. As these markets develop and patient awareness rises, the demand for effective IBS-D treatments is expected to soar. Expanding into these regions with targeted therapies and affordable options allows companies to tap into a previously underserved population, further boosting global market expansion.
- For instance, Takeda Pharmaceutical Company has also been investing heavily in personalized medicine in the region, developing innovative gastrointestinal drugs tailored to local patient needs.
Key Challenges
Limited Number of Approved Therapies
The IBS-D drug market faces challenges due to the limited number of approved therapies. Despite growing demand, relatively few treatments have been formally approved by regulatory authorities, which restricts available options. Many drugs are used off-label, causing hesitation among healthcare providers. This limited approval landscape creates barriers for both patients seeking optimal treatment and pharmaceutical companies looking to expand their product portfolios in the IBS-D segment.
High Treatment Costs and Access Barriers
The high costs of IBS-D treatments pose a significant challenge to market growth. For many patients, especially in developing regions, these costs present a substantial barrier to access. Insurance coverage and reimbursement policies also vary widely, which can limit the affordability and availability of these treatments. These economic challenges hinder widespread adoption, particularly in lower-income markets, where the cost of new therapies can impede broader market penetration and patient access.
Regional Analysis
North America
The North America region holds a dominant position in the global IBS‑D drugs market, accounting for a market share of 37.5% in 2024. This strong share is driven by advanced healthcare infrastructure, high level of disease awareness, and early adoption of novel therapeutics. The presence of major pharmaceutical players and significant investment in gastroenterology research further reinforce regional leadership. Patients in North America benefit from better access to diagnostic services and specialist care, which supports higher uptake of targeted treatment options for IBS‑D and contributes to sustained market momentum.
Europe
Europe comprises a significant portion of the IBS‑D drugs market, contributing a substantial share (though slightly below North America’s lead). The region’s growth is supported by widespread health awareness campaigns, strong regulatory frameworks and increasing healthcare spending in countries like Germany, the UK, and France. Diet and lifestyle changes among European populations are elevating the prevalence of IBS‑D, stimulating demand. Moreover, reimbursement policies in many European markets encourage treatment uptake. These combined factors enable Europe to maintain a stable and growing segment of the global IBS‑D drugs market.
Asia Pacific
The Asia Pacific region is emerging rapidly in the IBS‑D drugs market, with growth driven by increasing healthcare access, urbanisation and awareness of gastrointestinal disorders. Although its current market share is smaller than that of North America and Europe, Asia Pacific’s growth rate exceeds many mature regions. Countries such as China, Japan and India are seeing rising incidence of IBS‑D, expanding pharmaceutical infrastructure and a greater focus on novel therapies. These developments position Asia Pacific as a key growth frontier for IBS‑D drug manufacturers seeking expansion beyond established markets.
Latin America
Latin America holds a moderate share of the global IBS‑D drugs market, supported by improving healthcare systems and rising patient awareness of bowel disorders. While its market size remains smaller compared with North America and Europe, the region demonstrates potential for expansion due to increasing diagnostic capabilities and pharmaceutical penetration in countries like Brazil and Argentina. Economic constraints and variable reimbursement remain hurdles, yet the growing demand for effective IBS‑D treatments and generics presents an attractive opportunity for manufacturers targeting this region.
Middle East & Africa
The Middle East & Africa region has the smallest share of the global IBS‑D drugs market, reflecting limited healthcare infrastructure, low awareness of IBS‑D and constrained access to advanced therapies. Nonetheless, gradual improvements in public health spending, rising urbanisation and expanding private healthcare services are laying the foundation for future growth. Manufacturers developing cost‑effective treatment options and engaging in education campaigns may unlock latent demand. With increased investment and better diagnostics, this region could achieve higher uptake of IBS‑D therapies in the coming years.
Market Segmentations:
By Drug Class
- Anti-diarrheal Agents
- Gut-Brain Targeted Therapies
- Antibiotics
- Antispasmodics
- Others
By Route of Administration
- Oral Formulations (Tablets, Capsules, Liquids)
- Rectal Formulations (Suppositories, Enemas)
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Others
By End-User
- Hospitals
- Clinics
- Ambulatory Surgical Centers
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape in the IBS‑D drugs market led by Bausch Health Companies (Salix Pharmaceuticals), Ironwood Pharmaceuticals, Allergan (AbbVie), Sebela Pharmaceuticals, RedHill Biopharma, Ardelyx, Alnylam Pharmaceuticals, Mylan Pharmaceuticals, Astellas Pharma and Takeda Pharmaceutical Company features both established pharma giants and agile biotech players. These companies differentiate through strategic product launches, patent protections, and licensing alliances focused on novel mechanisms such as gut‑microbiome modulation or opioid receptor targeting. Pricing strategy, clinical trial success, and formulary inclusion determine competitive positioning, with generics and off‑label alternatives adding pressure on margins. Collaboration with academic bodies and investment in pipelines help new entrants challenge incumbents, while regulatory hurdles and IP defense remain critical battlegrounds.
Key Player Analysis
- Bausch Health Companies (Salix Pharmaceuticals)
- Ironwood Pharmaceuticals
- Allergan (AbbVie)
- Sebela Pharmaceuticals
- RedHill Biopharma
- Ardelyx
- Alnylam Pharmaceuticals
- Mylan Pharmaceuticals
- Astellas Pharma
- Takeda Pharmaceutical Company
Recent Developments
- In February 2025, RedHill Biopharma Ltd. entered into an exclusive worldwide licensing agreement (excluding North America) with Hyloris Pharmaceuticals SA for the development and commercialization of RHB-102 (Bekinda®) for IBS-D.
- In March 2025, Zydus Lifesciences received final approval from the US Food and Drug Administration (USFDA) to manufacture generic tablets of Eluxadoline (75 mg and 100 mg) for adults with Irritable Bowel Syndrome with Diarrhea (IBS‑D).
- In February 2024, CinPhloro Pharma, a portfolio company of CinRx Pharma, dosed the first patient in the Phase 2 "enviva" study of CIN-103, a novel phloroglucinol formulation for Irritable Bowel Syndrome with Diarrhea (IBS-D) .
- In October 2023, Roche entered into a definitive agreement to acquire Telavant Holdings, Inc., a company specializing in gastrointestinal disorders. This acquisition, which includes a novel TL1A-directed antibody, strengthens Roche’s presence in the GI therapeutic space, indirectly impacting IBS-D treatment development .
Report Coverage
The research report offers an in-depth analysis based on Drug Class, Route of Administration, Distribution Channel, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continuous growth in the IBS‑D drugs market will result from rising diagnosis rates and increased treatment uptake.
- Innovation in therapies targeting the gut‑brain axis, microbiome modulation, and personalized medicine will reshape the competitive landscape.
- Emerging markets will see faster growth as healthcare access and awareness improve in Asia‑Pacific and Latin America.
- Healthcare providers will shift toward early intervention and preventive management strategies, boosting demand for effective treatments.
- Biotech and pharma firms will invest more heavily in clinical trials and drug pipeline development for novel IBS‑D drugs.
- Digital health tools and telemedicine will enhance patient engagement and adherence to IBS‑D treatment regimens.
- Generic entrants and biosimilars will increase market pressure on branded therapies, driving cost‑effective alternatives.
- Regulatory agencies will streamline approval pathways for new mechanisms of action, accelerating market entry of advanced therapies.
- Patient preference for oral formulations and convenient dosing will drive formulation innovation and market growth.
- Affordability and reimbursement dynamics will become critical, with companies needing strategies to ensure access in diverse economic environments.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Irritable Bowel Syndrome IBS With Diarrhea Drugs Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Irritable Bowel Syndrome IBS With Diarrhea Drugs Market projected to grow between 2025 and 2032?
Which Irritable Bowel Syndrome IBS With Diarrhea Drugs Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Irritable Bowel Syndrome IBS With Diarrhea Drugs Market?
Who are the leading companies in the Irritable Bowel Syndrome IBS With Diarrhea Drugs Market?
Which region commanded the largest share of the Irritable Bowel Syndrome IBS With Diarrhea Drugs Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,314.33 Million → 2032: USD 5,694.63 Million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Market Drivers
- 3.3 Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Market Restraints & Challenges
- 3.4 Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Irritable Bowel Syndrome with Diarrhea (IBS-D) Drugs Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
