
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Middle East and Africa Female Hygiene Products Market Size 2023 | USD 1654.2 Million |
| Middle East and Africa Female Hygiene Products Market, CAGR | 4.80% |
| Middle East and Africa Female Hygiene Products Market Size 2032 | USD 2522.54 Million |
Market Insights
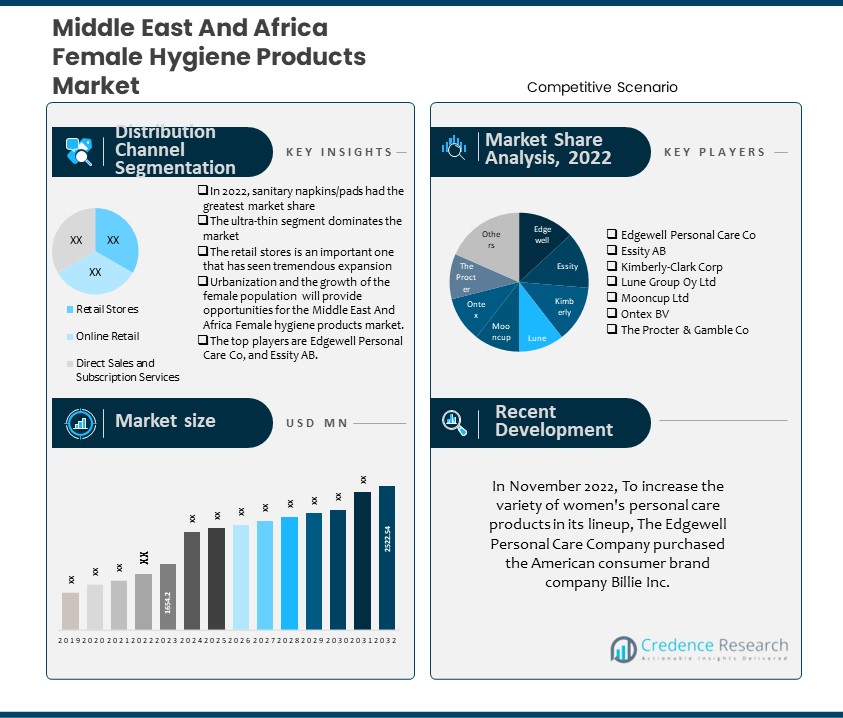
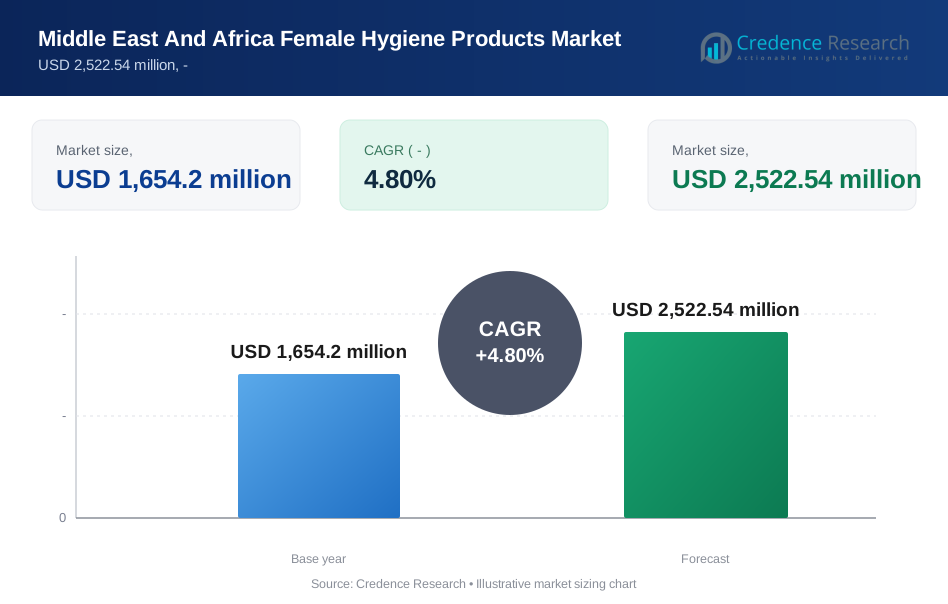
- Between 2024 and 2032, the Middle East And Africa female hygiene products market is expected to develop at a compound annual growth rate (CAGR) of 4.80%, from its estimated USD 1654.2 million in 2023 to USD 2522.54 million in 2032.
- Sanitary napkins/pads are the significant product type category. On the other hand, menstrual cups are expected to grow at a strong CAGR.
- The leading absorbency level segment is ultra-thin.
- The CAGR for retail stores is expected to be the highest during the projection period.
- GCC countries dominate the female hygiene products market in the Middle East and Africa.
- The market for female hygiene products in the Middle East and Africa is expected to develop at the quickest rate in South Africa.
- The demand for feminine hygiene products rises in urban areas because of increasing population density and easier access to retail outlets. Growing populations also lead to a wider consumer base for these products.
- Consumers with more disposable money may purchase hygiene products and choose higher-quality options, and changes in consumer preferences are driving growth in the Middle East And Africa female hygiene products market.
Executive Summary
Market Definition
The manufacturing, distribution, and retailing of a range of hygiene products tailored to women's menstrual hygiene requirements and personal care needs in the Middle East and Africa are collectively referred to as the Middle East and Africa Female Hygiene Products Market. These items are made for general feminine hygiene needs as well as comfort, protection, and cleanliness throughout the menstrual cycle.
Market Overview
The Middle East And Africa female hygiene products sector is estimated to develop at a 4.80% compound annual growth rate (CAGR) between 2024 and 2032, maintaining its current upward trend. The market will continue to develop, rising from its estimated value of USD 1654.2 million in 2023 to USD 2522.54 million in 2032.
Modern technology and access to high-quality education have made it possible for women to have a greater understanding of critical components of their biology, such as the menstrual cycle. Infertility and other serious disorders can result from improper genital hygiene, as well as transient infections. In order to stop these diseases from happening, medical practitioners constantly advise menstrual care items. This will contribute to the market expansion for feminine hygiene products across the Middle East and Africa in the future. In the first half of 2023, Procter & Gamble Company's infant, feminine, and family care business division saw a 9% rise, reaching USD 20,217 million. The rising demand for feminine care products from consumers throughout that period is what's responsible for the segment's revenue growth.
Segmentation by Product Type
- Sanitary napkins/pads are the market leader by product type. Sanitary pad consumption rises as a result of increased access to education and hygiene products brought about by urbanization. Sanitary pads are easily accessible at pharmacies and retail stores, which are more developed in urban areas.
- The menstrual cups category will exhibit a sizable CAGR during the projected period. Compared to throwaway goods like pads and tampons, menstrual cups are a more environmentally friendly choice because they are reusable and can last for several years with proper care. There is a growing demand for menstrual cups as people look for eco-friendly options as their concerns about the environment rise.
- Other product types, including tampons, panty liners, feminine wipes, feminine wash, and others, also influence the Middle Eastern and African female hygiene products market.
Segmentation by Absorbency Level
- The significant absorbency level category is ultra-thin. Absorbency levels for ultra-thin feminine hygiene products can vary from light to heavy. While heavy absorbency products are intended for usage overnight or on days with heavier flow, light absorbency products are appropriate for lighter menstrual cycles or persons with lighter flow.
- The regular/standard category will likely register a significant CAGR during forecasting. The "regular" or "standard" absorbency level describes a popular class of menstrual hygiene items with moderate absorbency, including tampons or pads. These products are appropriate for people who have a regular menstrual flow; they are neither excessively light nor heavy.
- Other absorbency levels, including heavy/maxi and super/extra, also influence the need for the Middle East and African female hygiene products market.
Segmentation by Distribution Channel
- The retail stores category is projected to grow fastest over the projection period. Brand loyalty and familiarity are two of the key elements driving demand for feminine hygiene products in retailers. Consumers usually choose well-known brands because they think they are more dependable and superior.
- Other distribution channels, including online retail, direct sales, and subscription services, also influence the need for the Middle Eastern and African female hygiene products market.
Segmentation by Country
- GCC countries dominate the female hygiene products market in the Middle East and Africa. Cultural perspectives on menstruation and feminine hygiene are gradually changing in the GCC nations. The demand for feminine hygiene products is growing more favorably as a result of initiatives to lessen stigma and support menstrual health.
- The female hygiene products market in the Middle East and Africa is predicted to flourish rapidly in South Africa. Through the adoption of corporate social responsibility initiatives, businesses in South Africa have the chance to both positively impact society and drive company success. Programs that manage menstrual hygiene in schools and workplaces, provide disadvantaged populations with access to hygiene products, and educate people about menstruation health might be sponsored by businesses.
An inorganic sanitary pad, which is composed of cotton, gel, and plastic, has negative impacts that many companies are attempting to communicate. It is synthetic because some of the goods are even scented. Researchers believe that the chlorine chemicals used in the production of these synthetic items can lead to endometriosis, urinary tract infections, decreased fertility, and potentially cancer. Because of plastic, it's thought that inorganic sanitary pads take 500–700 years to degrade. Organic sanitary pads composed of organic cotton, corn starch, and bamboo have been made available under the Nailen Private Limited brand, Noraa. Due to consumers' growing tendency to consider environmental causes when making purchases, this practice is probably going to catch on quickly.
Based on projections, the Middle East And Africa female hygiene products market is dominated by GCC countries for several reasons. The GCC countries' population has grown significantly, including the number of women. The requirement for feminine hygiene products is spurred by the growing number of women in these nations, creating a larger consumer base.
It is projected that during the forecast period, the Middle East and Africa market for female hygiene products in South Africa will grow at the quickest rate. In South Africa, there are opportunities to increase the distribution networks for feminine hygiene products. Organizations should look at forming alliances with pharmacies, supermarkets, merchants, and internet platforms in order to expand their consumer base and improve accessibility, especially for people living in underserved and rural areas.
Key Highlights of the Report
The Middle East And Africa Female Hygiene Products Market is segmented by product type, absorbency level, distribution channel, and country. Regarding the product type, sanitary napkins/pads are the market spearhead. Ultra-thin is the top absorbency level category. The retail stores category is anticipated to increase at the highest CAGR throughout the projection period. The female hygiene products market in the Middle East and Africa is expanding mostly in GCC countries.
The MEA region's manufacturers are always coming up with new ideas to satisfy the changing demands of its customers. The market is expanding due to new product innovations like biodegradable goods, eco-friendly materials, and cutting-edge features. Furthermore, the demand for feminine hygiene products is expanding due to successful marketing tactics that focus on the health and wellness of women.
The most significant market for female hygiene products in the Middle East and Africa is anticipated to be in the GCC countries. The GCC nations are renowned for having affluent consumer bases and high per capita incomes. Women in these nations have more money to spend on personal care items, such as feminine hygiene products, thanks to increases in their disposable income. South Africa is also assumed to have the market's sharpest growth. The government of South Africa has expressed its support for programs that advance the cleanliness and health of women. Companies can work with NGOs and government agencies on advocacy campaigns, public health campaigns, and legislative initiatives to tackle menstrual health issues and increase access to feminine hygiene products.
Which Key Factors Are Driving The Middle East And Africa Female Hygiene Products Market?
The primary drivers of the Middle East and African female hygiene products market are ongoing innovation in product design and features, rising public awareness of health issues, particularly menstrual health, and educational campaigns and initiatives that encourage menstrual health and hygiene.
What Are The Main Challenges Confronting The Middle East And Africa Female Hygiene Products Market?
The main barriers to the expansion of the female hygiene products market in the Middle East and Africa are the substantial cost of hygiene products, the lack of adequate distribution channels, the lack of adequate instruction and understanding regarding menstruation health and cleanliness, and financial challenges.
What Are The Market Opportunities For Female Hygiene Products In The Middle East And Africa?
Changes in cultural perceptions of menstruation and hygiene, legislation ensuring product safeguarding and quality standards, and economic expansion and development driving up demand for hygiene products are the major market opportunities for the female hygiene products sector in the Middle East and Africa.
Market Drivers
Multiple factors propel the Middle East And Africa female hygiene products market. The primary factors propelling the Middle East And Africa female hygiene products market are as follows:
Urbanization and the Growth of the Female Population
The Middle East and Africa (MEA) region's market for female hygiene products is expanding as a result of increased urbanization and the growing number of women in the population. The population of the MEA region has been growing, with a considerable rise in the proportion of females. The demand for feminine hygiene products in the region is rising in tandem with the number of women living there. An increased market for products like tampons, menstrual cups, panty liners, sanitary pads, and intimate wash is a direct result of this demographic change. Another important factor influencing industry expansion is urbanization. The lifestyle and consumption patterns of individuals in the MEA region are changing as more move from rural to urban areas. Greater knowledge of personal cleanliness, better access to healthcare and hygiene goods, and higher disposable earnings are all common in urban settings. As a result, metropolitan women are more inclined to buy a range of feminine hygiene products, which helps the industry grow.
Market Restraints
There are several obstacles that the Middle East And Africa female hygiene products market must overcome to continue growing. Among them are the following:
Menstruation and Feminine Hygiene Products are Socially Stigmatized
The social stigma associated with menstruation frequently results from inadequate knowledge and instruction regarding menstrual cleanliness and health. Menstruation is taboo in many cultures in the MEA region, and conversations concerning it are frequently veiled in silence. Women may find it difficult to comprehend the value of good menstrual hygiene and the accessibility of appropriate hygiene products due to a lack of knowledge and education. The stigma attached to menstrual health and cleanliness is exacerbated by cultural taboos and beliefs around menstruation. Some taboos include the idea that women who menstruate are impure or unclean, which breeds prejudice and social isolation. These cultural norms have the potential to hinder women's access to and desire for menstrual hygiene products, which could hinder the growth of the market.
Opportunities
There are many potential prospects in the Middle East And Africa female hygiene products industry. Among these are the following:
Develop Environmentally Friendly Products for Feminine Hygiene
Sustainability and environmental awareness are popular globally, and this is also the case in the MEA region. People are looking for more environmentally friendly options in everything from feminine hygiene products to other areas of their lives as their awareness of environmental challenges such as plastic pollution and waste management rises. The MEA region's consumers are becoming increasingly aware of how the things they use affect the environment. Biodegradable, compostable, and composed of sustainable materials like organic cotton, bamboo, or plant-based fibers are in high demand when it comes to feminine hygiene products. By creating environmentally friendly solutions, firms may stand out in the marketplace and satisfy consumer demand. The MEA region's governments and regulatory agencies are launching programs and regulations to encourage environmental sustainability and cut down on plastic waste. Manufacturers of feminine hygiene products can take advantage of this legislation to innovate and provide environmentally friendly substitutes that satisfy both consumer preferences and legal criteria.
Competitive Landscape
Key Players
Several major competitors exist in the fiercely competitive Middle Eastern and African female hygiene products market. The following are a few of the leading market participants and their market shares:
- Edgewell Personal Care Co
- Essity AB
- Kimberly-Clark Corp
- Lune Group Oy Ltd
- Mooncup Ltd
- Ontex BV
- The Procter & Gamble Co
- Others
To remain competitive, these companies prioritize product innovation, distribution channel expansion, mergers, and acquisitions.
The largest suppliers in the Middle East And Africa female hygiene products market continuously work to keep one step ahead of the competition by developing innovative concepts and products.
In January 2022, In order to increase its footprint in the global market for intimate apparel items, Essity AB purchased the Australian company Modibodi and the Canadian company Knix Wear, Inc.
In January 2021, Essity AB introduced a selection of washable and absorbent undergarments under their incontinence product line. These products work incredibly well to control menstruation and bladder leaks.
Summary of Key Findings
- Recognizable brands with solid reputations attract customers and boost market demand, which is why the Middle East and Africa markets are expanding.
- The market is segmented by product type, absorbency level, distribution channel, and country.
- The most popular product type in the market is sanitary napkins/pads.
- Ultra-thin is the foremost absorbency level category.
- Retail stores are expected to grow the fastest in terms of CAGR during the forecast period.
- GCC countries are leading market development; the market is highly competitive with key players including Edgewell Personal Care Co, Essity AB, Kimberly-Clark Corp, Lune Group Oy Ltd, Mooncup Ltd, Ontex BV, The Procter & Gamble Co, and Others.
Future Outlook
- The female hygiene products industry in the Middle East and Africa is expected to increase significantly in GCC countries and has a positive outlook.
- The Middle East and African female hygiene products market is experiencing growth due to the rising female workforce.
- The use of hygiene products might be hampered by ingrained cultural taboos and ideas about menstruation and feminine hygiene, which can result in inadequate knowledge and usage rates.
- To stay ahead of the competition, key enterprises must develop new products, expand their market reach, and keep their prices competitive.
How CXOs Can Benefit from the Credence Research Middle East And Africa Female Hygiene Products Market Report
CXOs may get a detailed picture of the market in the Credence Research Middle East And Africa Female Hygiene Products Market Report, which includes:
- Market size and growth forecast: The report provides detailed estimates of the market size of female hygiene products in the Middle East and Africa, segmented by product type, absorbency level, distribution channel, and country. It also includes forecasts for the market through 2032 based on key trends and drivers.
- Market segmentation: The research report breaks down the market for Middle Eastern and African female hygiene products into segments based on product type, absorbency level, distribution channel, and country. This segmentation provides CXOs with a granular understanding of the market and the opportunities in each segment.
- Competitive landscape: The research report offers a detailed analysis of the major companies in the Middle East and Africa's female hygiene products industry, including information on their business plans, product lines, and earnings. CXOs can use this information to evaluate and identify their competitors.
- Key trends and drivers: The research report identifies and evaluates the main trends and factors influencing the market for Middle Eastern and African female hygiene products. CXOs can use this information to make well-informed choices regarding their plans and investments.
CXOs can use the insights from the Credence Research Middle East And Africa Female Hygiene Products Market Report to:
- Identify growth opportunities: This analysis may help CXOs identify new growth opportunities in the Middle East and African female hygiene products sector. For example, the report identifies the growing demand for female hygiene products from retail consumers as a key opportunity.
- Make informed investment decisions: This study may help CXOs make informed decisions about Middle Eastern and African female hygiene products. For example, it provides information on the critical factors to consider while selecting female hygiene product solutions and evaluating suppliers.
- Develop competitive strategies: The research report can be used by CXOs to develop competitive strategies for their Middle Eastern and African female hygiene products businesses. For example, the research paper outlines the main strategies suppliers of Middle Eastern and African female hygiene products utilize to differentiate themselves from competitors.
- Track market developments: This research report may help CXOs stay ahead of the curve by tracking market developments. For instance, it offers insights into the most recent developments and trends in the Middle East and African female hygiene products market.
In general, CXOs seeking to expand their industry knowledge and spot growth prospects will find the Credence Research Middle East And Africa Female Hygiene Products Market Report useful.
Segmentation
- By Product Type
- Sanitary Napkins/Pads
- Tampons
- Menstrual Cups
- Panty Liners
- Feminine Wipes
- Feminine Wash
- Others
- By Absorbency Level
- Ultra-Thin
- Regular/Standard
- Heavy/Maxi
- Super/Extra
- By Distribution Channel
- Retail Stores
- Online Retail
- Direct Sales and Subscription Services
- By Country
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Middle East and Africa female hygiene products market?
What is the projected growth rate of female hygiene products in the Middle East and Africa between 2024 and 2032?
In terms of product type, which market category is leading?
Regarding absorbency level, which market category is in the lead?
Who are the main players in the female hygiene products industry in the Middle East and Africa?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Middle East And Africa Female Hygiene Products Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Middle East And Africa Female Hygiene Products Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 1,654.2 million → forecast year: USD 2,522.54 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Middle East And Africa Female Hygiene Products Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Middle East And Africa Female Hygiene Products Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Middle East And Africa Female Hygiene Products Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Middle East And Africa Female Hygiene Products Market Drivers
- 3.3 Middle East And Africa Female Hygiene Products Market Restraints & Challenges
- 3.4 Middle East And Africa Female Hygiene Products Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Middle East And Africa Female Hygiene Products Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Middle East And Africa Female Hygiene Products Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Middle East And Africa Female Hygiene Products category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Middle East And Africa Female Hygiene Products Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Middle East And Africa Female Hygiene Products Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Middle East And Africa Female Hygiene Products market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Middle East And Africa Female Hygiene Products Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Middle East And Africa Female Hygiene Products Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Middle East And Africa Female Hygiene Products Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Middle East And Africa Female Hygiene Products (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Middle East And Africa Female Hygiene Products Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Middle East And Africa Female Hygiene Products Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Middle East And Africa Female Hygiene Products Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Middle East And Africa Female Hygiene Products Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Middle East And Africa Female Hygiene Products Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Middle East And Africa Female Hygiene Products Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Middle East And Africa Female Hygiene Products Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Middle East And Africa Female Hygiene Products Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Middle East And Africa Female Hygiene Products Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
