
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
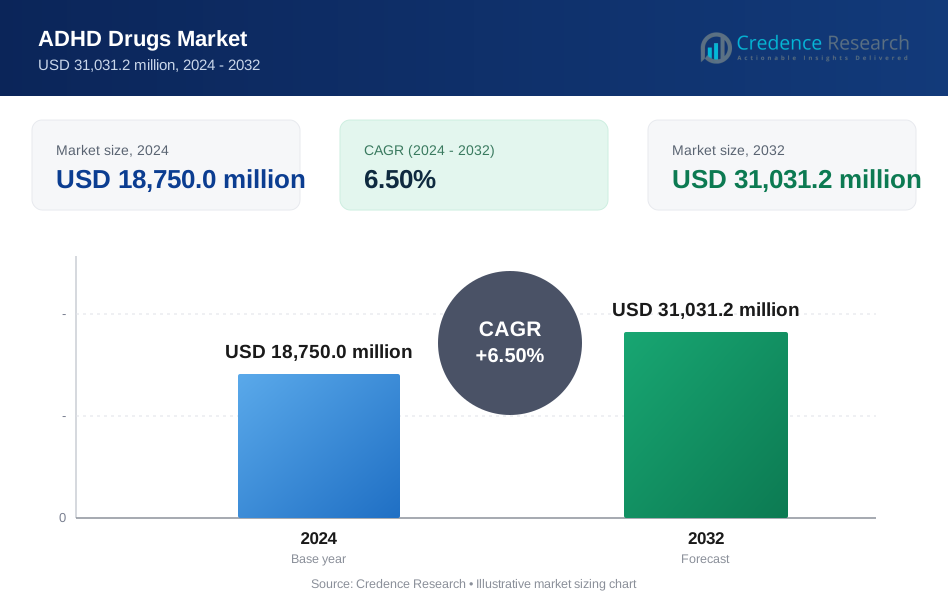
| ADHD Drugs MarketSize 2024 | USD 18,750.0 million |
| ADHD Drugs Market, CAGR | 6.50% |
| ADHD Drugs Market Size 2032 | USD 31,031.2 million |
Market Overview
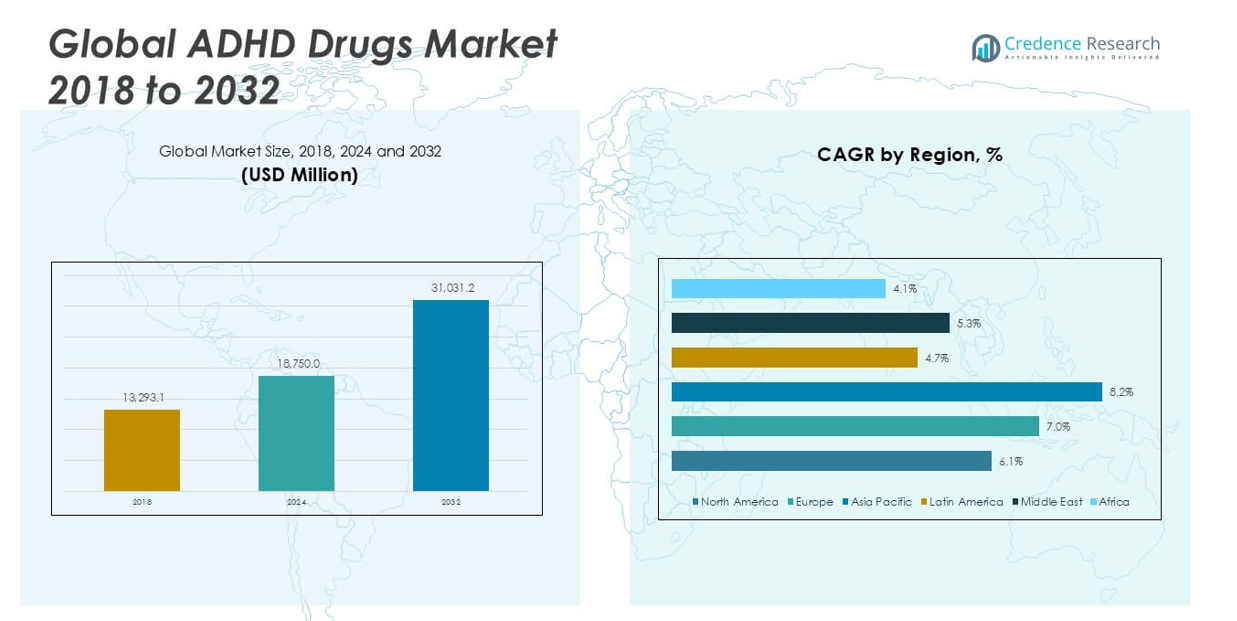
The ADHD Drugs market size was valued at USD 13,293.1 million in 2018, reached USD 18,750.0 million in 2024, and is anticipated to reach USD 31,031.2 million by 2032, at a CAGR of 6.50% during the forecast period.
The ADHD Drugs market is led by prominent players such as Takeda Pharmaceutical Company Limited, Novartis AG, Pfizer Inc., Eli Lilly and Company, Johnson & Johnson (Janssen Pharmaceuticals), and Teva Pharmaceutical Industries Ltd., each holding significant shares through robust product portfolios and innovative drug formulations. North America stands as the dominant region, accounting for approximately 43% of the global market share in 2024, driven by advanced healthcare infrastructure, high diagnosis rates, and early adoption of novel therapies. Europe and Asia Pacific also contribute substantially, supported by rising awareness and expanding treatment accessibility, further intensifying competition among these top pharmaceutical companies.
Market Insights
- The ADHD Drugs market reached USD 18,750.0 million in 2024 and is projected to hit USD 31,031.2 million by 2032, registering a CAGR of 6.50% during the forecast period.
- Growth is primarily driven by increasing ADHD diagnoses, improved awareness, and expanding treatment options across both pediatric and adult populations.
- Extended-release stimulant medications hold over 65% of the segment share, reflecting strong prescriber and patient preference for convenience and consistent symptom control.
- Market leaders such as Takeda Pharmaceutical Company Limited, Novartis AG, Pfizer Inc., and Teva Pharmaceutical Industries Ltd. drive innovation, while intense competition and patent expiries foster generic drug growth and pricing pressures.
- North America leads with a 43% market share in 2024, followed by Europe at 25% and Asia Pacific at 18%, while Latin America, Middle East, and Africa collectively hold smaller but steadily growing shares.
Market Segmentation Analysis:
By Product Type
Stimulant medications represent the dominant sub-segment in the ADHD drugs market, accounting for over 65% of the total market share. These medications, including methylphenidate and amphetamine derivatives, remain the primary choice due to their proven efficacy in managing core ADHD symptoms. The widespread clinical acceptance, rapid onset of action, and robust safety profile continue to drive their adoption. Non-stimulant medications are gaining traction, particularly among patients who do not respond well to stimulants or have contraindications, but their market presence remains secondary.
- For instance, Takeda Pharmaceutical’s Vyvanse received over 9,200,000 prescriptions in the United States in 2023, reflecting its widespread use in stimulant-based therapy.
By Technology
Extended-release formulations hold the leading position within the technology segment, contributing nearly 60% of the revenue share in the ADHD drugs market. Their popularity stems from the convenience of once-daily dosing, improved adherence, and consistent therapeutic effects throughout the day. The preference for these formulations is especially high among school-aged children and working adults seeking sustained symptom control. Other technologies, such as digital health platforms and drug delivery systems, are emerging, but they collectively account for a smaller market portion.
- For instance, Johnson & Johnson’s Concerta, an extended-release methylphenidate product, reported more than 5,000,000 prescriptions filled in 2023, underlining the dominance of extended-release technology.
By End User
Children form the largest end user segment, commanding around 55% of the ADHD drugs market share. The early diagnosis of ADHD in pediatric populations and high treatment rates among school-going children drive segment dominance. Increasing awareness among parents and educators, along with established pediatric dosing guidelines, supports the widespread use of ADHD medications in this group. While adolescent and adult segments are expanding-driven by better recognition of ADHD across age groups-children remain the primary recipients of pharmacological intervention.
Market Overview
Rising Prevalence and Awareness of ADHD
The increasing prevalence of ADHD diagnoses globally, coupled with greater public and professional awareness, serves as a major growth driver for the ADHD drugs market. Improved screening initiatives in schools and healthcare settings have led to earlier identification and intervention, especially among children and adolescents. This expanded patient pool directly fuels demand for pharmacological treatments, positioning the market for sustained expansion over the forecast period.
- For instance, Novartis AG supported over 1,500 educational workshops across North America and Europe in 2023, contributing to increased ADHD screening rates and early diagnosis initiatives.
Advancements in Drug Formulations
Ongoing innovations in drug formulations, such as extended-release and combination therapies, have significantly improved treatment outcomes and patient compliance. These advancements enable more consistent symptom control, minimize dosing frequency, and reduce the risk of side effects. As a result, prescribers increasingly favor novel drug delivery methods, which in turn stimulate market growth and create opportunities for product differentiation among manufacturers.
- For instance, Supernus Pharmaceuticals introduced Qelbree, a novel non-stimulant ADHD medication, and recorded 1,900,000 prescriptions in its first full year on the market.
Expanding Treatment Across Age Groups
The recognition of ADHD as a condition affecting not only children but also adolescents and adults has broadened the treatment landscape. Increased awareness and reduced stigma surrounding adult ADHD, along with evolving clinical guidelines, have encouraged more adults to seek diagnosis and treatment. This demographic shift is expanding the potential market size and driving pharmaceutical companies to develop and market therapies suitable for a wider age range.
Key Trends & Opportunities
Integration of Digital Health Solutions
The adoption of digital health platforms, including telemedicine and mobile applications, is transforming ADHD management. These solutions enable remote patient monitoring, improve medication adherence, and support personalized treatment plans. The integration of digital tools with pharmacological therapies represents a key trend, offering both market growth opportunities and improved patient engagement for healthcare providers and pharmaceutical companies.
- For instance, Akili Interactive’s EndeavorRx, an FDA-cleared digital therapeutic for pediatric ADHD, had more than 40,000 users enrolled in digital treatment programs in 2023.
Personalized and Precision Medicine Approaches
A growing trend toward personalized medicine is shaping the ADHD drugs market, with increased focus on tailoring treatments to individual patient profiles. Genetic testing, biomarkers, and advanced diagnostic techniques are being explored to optimize therapy selection and minimize adverse effects. These developments create opportunities for companies to introduce targeted therapies and companion diagnostics, differentiating their offerings and enhancing patient outcomes.
- For instance, Genomind provided over 100,000 genetic test panels in 2023, enabling clinicians to personalize ADHD medication regimens based on patients’ unique genetic profiles.
Key Challenges
Concerns Over Safety and Misuse
Safety concerns related to stimulant medications, including the risk of dependence, misuse, and cardiovascular side effects, present a significant challenge for market growth. Regulatory scrutiny and the need for risk mitigation strategies may limit prescribing rates and drive demand for alternative therapies. Addressing these concerns through patient education and improved monitoring remains a key focus for industry stakeholders.
Stringent Regulatory Environment
The ADHD drugs market faces rigorous regulatory requirements for drug approval and ongoing compliance, particularly regarding pediatric use and long-term safety. Lengthy approval processes, post-marketing surveillance, and evolving guidelines can delay product launches and increase development costs. Manufacturers must navigate these complexities to ensure sustained access to new and existing therapies.
Stigma and Underdiagnosis in Adults
Despite progress, persistent stigma and underdiagnosis of ADHD in adults continue to limit market growth. Many adults remain untreated due to lack of awareness or misattribution of symptoms, reducing overall treatment penetration. Overcoming these barriers will require ongoing educational initiatives and collaboration among healthcare professionals, patient advocacy groups, and industry players.
Regional Analysis
North America North America commands the largest share of the global ADHD drugs market, accounting for approximately 43% in 2024. The market expanded from USD 6,021.8 million in 2018 to USD 8,212.5 million in 2024, and is projected to reach USD 12,257.3 million by 2032, registering a CAGR of 6.1%. This region’s dominance is driven by high diagnosis rates, broad access to advanced therapeutics, and robust healthcare infrastructure. Favorable reimbursement policies and significant awareness among healthcare professionals and patients further support strong market growth.
Europe
Europe holds a substantial share of the ADHD drugs market, representing about 25% in 2024. The regional market increased from USD 3,403.0 million in 2018 to USD 4,631.3 million in 2024, with an expected rise to USD 7,106.1 million by 2032, at a CAGR of 7.0%. Growth is underpinned by increasing recognition of ADHD across age groups, progressive healthcare policies, and expansion of treatment guidelines. Efforts to reduce stigma and expand access to behavioral and pharmacological therapies are also contributing to sustained regional growth.
Asia Pacific
Asia Pacific is the fastest-growing region in the ADHD drugs market, with a CAGR of 8.2% and a market share of 18% in 2024. The market value rose from USD 2,033.8 million in 2018 to USD 3,431.3 million in 2024, projected to reach USD 6,702.7 million by 2032. Growth is driven by rising awareness, improving diagnostic capabilities, and growing healthcare expenditure in countries such as China, India, and Japan. The increasing focus on pediatric mental health and expanding access to therapies are accelerating market expansion.
Latin America
Latin America holds a modest but growing share of the ADHD drugs market, accounting for 4% in 2024. The market increased from USD 598.2 million in 2018 to USD 768.8 million in 2024, and is forecasted to reach USD 1,613.6 million by 2032, registering a CAGR of 4.7%. Expanding healthcare coverage, improved access to psychiatric care, and growing awareness are supporting gradual market development. However, varying regulatory standards and limited specialist availability present ongoing challenges for sustained regional growth.
Middle East
The Middle East represents 6% of the global ADHD drugs market in 2024, with market size rising from USD 850.8 million in 2018 to USD 1,256.3 million in 2024 and an anticipated value of USD 2,420.4 million by 2032. The region’s market growth, at a CAGR of 5.3%, is supported by rising mental health awareness, increasing investment in healthcare infrastructure, and the adoption of modern diagnostic and treatment practices. Societal shifts and policy efforts to address neurodevelopmental disorders continue to stimulate demand.
Africa
Africa accounts for around 2% of the global ADHD drugs market in 2024, growing from USD 385.5 million in 2018 to USD 450.0 million in 2024, and projected to reach USD 930.9 million by 2032 at a CAGR of 4.1%. Market expansion is fueled by gradually increasing awareness, improved healthcare outreach, and rising efforts to integrate mental health into public health agendas. However, access to diagnostic and therapeutic services remains limited, which continues to constrain broader market development in the region.
Market Segmentations:
By Product Type
- Stimulant Medications
- Non-Stimulant Medications
By Technology
- Extended-Release Formulations
- Non-Extended-Release Formulations
- Digital Health Platforms
- Drug Delivery Systems
By End User
- Children
- Adolescents
- Adults
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the ADHD drugs market is characterized by the presence of several major pharmaceutical companies, each leveraging strong R&D capabilities and extensive product portfolios to maintain their market positions. Leading players such as Takeda Pharmaceutical Company Limited, Novartis AG, Pfizer Inc., Eli Lilly and Company, Johnson & Johnson (Janssen Pharmaceuticals), and Teva Pharmaceutical Industries Ltd. dominate the market with a range of branded and generic ADHD medications. These companies continue to invest in the development of new formulations, including extended-release and combination therapies, to differentiate their offerings and enhance patient compliance. Emerging firms like Supernus Pharmaceuticals, Amneal Pharmaceuticals, Tris Pharma, and Neos Therapeutics are also expanding their footprints by targeting niche segments and introducing innovative drug delivery systems. Strategic collaborations, mergers, and acquisitions are prevalent, as companies seek to expand their global reach and strengthen their therapeutic pipelines, creating a dynamic and competitive market environment.
Key Player Analysis
- Takeda Pharmaceutical Company Limited
- Novartis AG
- Pfizer Inc
- Eli Lilly and Company
- Johnson & Johnson (Janssen Pharmaceuticals)
- Teva Pharmaceutical Industries Ltd.
- Supernus Pharmaceuticals, Inc.
- Amneal Pharmaceuticals, Inc.
- Tris Pharma, Inc.
- Purdue Pharma L.P.
- Ironshore Pharmaceuticals Inc.
- Neos Therapeutics, Inc.
- Aytu BioPharma, Inc.
- Rhodes Pharmaceuticals L.P.
Recent Developments
- In February 2025, Aytu BioPharma reported on its financial performance, highlighting the role of its ADHD portfolio (Adzenys XR-ODT and Cotempla XR-ODT) in its revenue. The company continues to focus on the marketing and distribution of these alternative formulation ADHD treatments.
- In September 2024, Ironshore Pharmaceuticals was acquired by Collegium Pharmaceutical. This acquisition includes Jornay PM (methylphenidate hydrochloride), an extended-release capsule taken in the evening to provide early morning symptom control for ADHD. Collegium is now responsible for the marketing and further development of this unique treatment option.
- In May 2024, Takeda reported that most of its ADHD medications, including methylphenidate, lisdexamfetamine, and guanfacine, were back in stock in the UK after a period of significant shortages.
- In September 2023, Amneal Pharmaceuticals received FDA approval for its generic versions of Vyvanse (lisdexamfetamine dimesylate) capsules. This approval made Amneal one of the first companies to offer a generic alternative to Vyvanse, a widely used ADHD medication, thereby increasing access and potentially lowering costs for patients. The approval included several dosage strengths (20 mg, 30 mg, 40 mg, 50 mg, 60 mg, and 70 mg).
- In August 2023, the U.S. FDA approved the first generic versions of Vyvanse (lisdexamfetamine dimesylate), marking a significant shift in the ADHD medication market by introducing affordable alternatives to Takeda's branded drug. This approval, granted to multiple generic manufacturers, signified increased competition and potential cost savings for patients.
Market Concentration & Characteristics
The ADHD Drugs Market exhibits a moderately high level of concentration, with a few multinational pharmaceutical companies capturing the majority of global revenue. It features a mix of branded and generic products, but brand loyalty and physician preference for established molecules continue to influence prescribing patterns. The market is characterized by strong research and development activities, ongoing product innovation, and a steady introduction of extended-release formulations designed to improve patient adherence. Regulatory scrutiny remains significant due to concerns about misuse and long-term safety, which shapes both product development and market access. Intellectual property protection for leading products helps sustain competitive advantages for key players, though patent expirations periodically open opportunities for generic manufacturers. Market entry barriers include stringent approval processes and the need for significant investment in clinical trials, manufacturing capabilities, and marketing networks. The sector’s growth is further influenced by evolving clinical guidelines, increasing diagnosis rates, and the expanding acceptance of pharmacological interventions across diverse age groups.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Technology, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Market adoption will broaden to include more adult ADHD diagnoses and treatment protocols.
- Pharmaceutical firms will increase investment in developing non-stimulant and combination therapies.
- Extended-release formulations will become more prevalent due to convenient dosing and improved adherence.
- Digital health platforms will integrate with drug regimens to support remote monitoring and patient engagement.
- Personalized medicine will guide therapy selection through genetic and biomarker-driven approaches.
- Emerging economies will gain traction as awareness and healthcare infrastructure expand.
- Generic manufacturers will erode branded drug dominance post-patent expiry.
- Regulatory frameworks will evolve to address safety concerns and mitigate misuse risks.
- Strategic collaborations and licensing deals will accelerate pipeline development and market reach.
- Telemedicine and e-prescription trends will enhance access, especially in underserved regions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the ADHD drugs market from 2024 to 2032?
What are the key drivers of the ADHD drugs market?
How is the development of new medications influencing the ADHD drugs market?
Which regions are leading the ADHD drugs market?
How are emerging markets impacting the ADHD drugs market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 ADHD Drugs Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global ADHD Drugs Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 18,750.0 million → 2032: USD 31,031.2 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 ADHD Drugs Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. ADHD Drugs Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 ADHD Drugs Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 ADHD Drugs Market Drivers
- 3.3 ADHD Drugs Market Restraints & Challenges
- 3.4 ADHD Drugs Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 ADHD Drugs Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 ADHD Drugs Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, ADHD Drugs category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 ADHD Drugs Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. ADHD Drugs Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to ADHD Drugs. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 ADHD Drugs Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 ADHD Drugs Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 ADHD Drugs Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in ADHD Drugs (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in ADHD Drugs
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global ADHD Drugs Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America ADHD Drugs Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe ADHD Drugs Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific ADHD Drugs Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America ADHD Drugs Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East ADHD Drugs Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa ADHD Drugs Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. ADHD Drugs Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
