
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| AI In Mental Health Market Size 2024 | USD 967.67 Million |
| AI In Mental Health Market, CAGR | 34.96% |
| AI In Mental Health Market Size 2032 | USD 10,650.44 Million |
Market Overview:
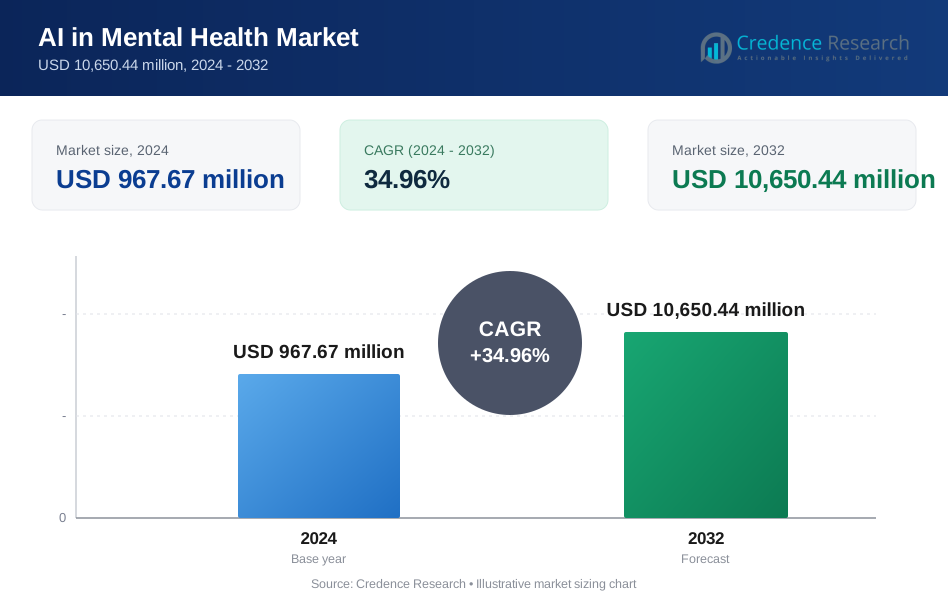
The AI In Mental Health Market is projected to grow from USD 967.67 million in 2024 to an estimated USD 10,650.44 million by 2032, with a compound annual growth rate (CAGR) of 34.96% from 2024 to 2032.
The key drivers of the AI in mental health market include the increasing global prevalence of mental health disorders and the urgent need for more efficient, accessible, and scalable mental health solutions. AI technologies are transforming mental health care by enhancing diagnostic accuracy, enabling real-time monitoring, personalizing treatment plans, and improving patient outcomes. AI-driven tools such as virtual therapists, chatbots, and predictive analytics are making mental health support more readily available, providing early detection and continuous care. This is particularly important in addressing the mental health care gap in underserved or remote areas. Furthermore, AI applications such as sentiment analysis and voice-based diagnostics are improving the precision of mental health assessments, enabling clinicians to identify and treat conditions more effectively Telemedicine’s growth and the increasing acceptance of digital health technologies are further accelerating the demand for AI in mental health.
Regionally, North America and Europe are leading the AI in mental health market. Both regions benefit from strong healthcare infrastructure, government support, and high levels of digital health adoption. In North America, particularly the United States, there has been significant investment in AI-driven mental health solutions, including in telehealth platforms and virtual care technologies. In the Asia Pacific region, countries like China, India, and Japan are showing promising growth due to rising mental health awareness, an expanding digital health landscape, and increased investment in AI research. Emerging markets in Latin America and the Middle East & Africa are gradually integrating AI to enhance mental health services and address growing mental health needs.
Market insights:
- The AI in Mental Health Market is expected to grow from USD 967.67 million in 2024 to USD 10,650.44 million by 2032, with a CAGR of 34.96% from 2024 to 2032.
- Key market drivers include the increasing prevalence of mental health disorders and the demand for efficient, scalable, and accessible mental health solutions through AI-powered technologies.
- AI-driven tools, such as virtual therapists, chatbots, and predictive analytics, are helping improve diagnostic accuracy, personalize treatments, and enable continuous care for patients.
- The growing acceptance of digital health technologies, including telemedicine, is accelerating the adoption of AI in mental health, offering more affordable and accessible care.
- Market restraints include concerns over data privacy, regulatory challenges, and the need for extensive validation of AI models in clinical settings to ensure safety and efficacy.
- North America and Europe lead the market due to strong healthcare infrastructure, government support, and advanced digital health adoption, particularly in the U.S. and key European countries.
- The Asia Pacific region is witnessing rapid growth driven by increasing mental health awareness, digital health adoption, and investments in AI research, with emerging markets in Latin America and the Middle East & Africa also contributing to market expansion.
Market Drivers:
Increasing Global Prevalence of Mental Health Disorders:
Mental health disorders are a growing global concern, with significant social and economic impacts. According to the World Health Organization (WHO), mental health conditions account for around 13% of the global burden of disease, and depression is expected to become the leading cause of disability by 2030. The World Bank has identified mental health issues as a critical factor affecting global productivity, emphasizing the need for innovative solutions. As the global population ages and mental health awareness increases, the demand for accessible and effective mental health care has surged, driving the adoption of AI-based solutions to address these challenges. For instance, the WHO's Mental Health Atlas 2020 reported that 1 in 4 people worldwide will experience a mental health condition at some point in their lives, further highlighting the critical need for innovative approaches such as AI to provide timely support and treatment.
Technological Advancements in AI and Machine Learning:
The rapid advancements in AI and machine learning are enabling new, efficient solutions for mental health care. AI-powered tools such as chatbots, virtual therapists, and predictive analytics are transforming the way mental health is diagnosed and treated. These technologies are designed to analyze vast amounts of data and provide real-time insights, helping clinicians make better decisions and improving the overall patient experience. For example, the International Monetary Fund (IMF) has highlighted the importance of leveraging emerging technologies like AI to reduce inefficiencies in various sectors, including healthcare. AI in mental health care helps automate routine tasks, allowing professionals to focus on more complex cases, thus improving the efficiency and accessibility of services globally.
Increasing Adoption of Digital Health Solutions:
The adoption of digital health solutions, including telemedicine and AI-driven applications, has been accelerating, especially post-pandemic. The global health crisis has highlighted the need for remote mental health care solutions, making digital platforms and AI-driven tools crucial in meeting the growing demand for mental health services. According to the U.S. Department of Health and Human Services, the adoption of telehealth services in the U.S. increased by over 150% in 2020 during the COVID-19 pandemic, underscoring the need for scalable and easily accessible mental health services. For example, the National Institutes of Health (NIH) has funded numerous projects aimed at advancing the integration of AI in mental health care, supporting research into the development of virtual mental health tools, such as AI-based counseling and diagnostic platforms.
Government Initiatives and Support:
Governments around the world are increasingly recognizing the importance of mental health care and are actively supporting the development of AI-driven solutions. For instance, the U.S. government has committed to increasing funding for mental health services, with a focus on incorporating AI and digital tools to enhance care delivery. The U.S. Department of Veterans Affairs (VA) has been utilizing AI-based tools to improve mental health outcomes for veterans, providing tailored care through virtual therapy and diagnostic assistance. The European Union has also launched several initiatives aimed at integrating AI in healthcare, including the Horizon Europe program, which provides funding for AI research in mental health and healthcare technologies.
Market Trends:
Growth in AI-Powered Mental Health Apps:
AI-powered mental health apps are increasingly popular as they offer scalable and accessible solutions for managing mental health. These apps utilize AI algorithms to provide personalized care, real-time emotional support, and early diagnosis of mental health issues. This has led to a surge in usage, particularly in regions where traditional mental health services are limited. For instance, the U.S. Department of Health and Human Services reported that telehealth adoption grew by 25 million users in 2020, showing a marked shift toward digital health solutions, including AI-powered mental health apps. These apps are breaking down barriers like cost, stigma, and geographical limitations, offering more people the opportunity to access mental health care and support.
Emergence of Virtual Therapy and Telehealth Solutions:
Virtual therapy and telehealth platforms have become mainstream, especially after the global COVID-19 pandemic. AI is increasingly integrated into these platforms to improve the quality of mental health care by offering more personalized treatment and real-time support. For example, the U.S. Department of Veterans Affairs (VA) has been utilizing AI-driven virtual therapy tools to provide mental health care to over 200,000 veterans across the country. This trend is not limited to the U.S., with countries like Canada, Australia, and the UK expanding their telehealth infrastructure to include AI-driven mental health solutions. AI applications in virtual therapy are enhancing the overall experience by providing more tailored treatments and allowing continuous monitoring of patients’ conditions.
AI for Early Detection and Prevention:
AI is playing a crucial role in early detection and prevention of mental health disorders. Through the analysis of speech patterns, facial expressions, and even social media activity, AI systems can detect signs of mental health conditions, such as depression or anxiety, before they become severe. For instance, the European Union’s Horizon 2020 program has funded various projects focusing on the use of AI to predict mental health conditions at an early stage. Research has shown that AI tools can detect depression in patients up to three months earlier than traditional diagnostic methods. Early intervention through AI-powered systems can significantly reduce the burden on healthcare systems and improve patient outcomes.
Collaboration Between Governments and AI Developers:
Governments are increasingly recognizing the potential of AI to improve mental health care and are collaborating with AI developers to create solutions that enhance accessibility, efficiency, and care quality. For example, in the U.S., the National Institutes of Health (NIH) has allocated more than $150 million in research funding for AI-based projects aimed at improving mental health care. Additionally, the World Health Organization (WHO) has emphasized the importance of AI in addressing the global mental health crisis, particularly in low- and middle-income countries. These government investments and partnerships are driving the development of AI tools that can enhance mental health service delivery, especially in underserved areas, thereby improving global access to mental health care.
Market Challenge Analysis:
Data Privacy and Security Concerns:
The integration of artificial intelligence (AI) in mental health care presents substantial data privacy and security challenges. AI systems handle sensitive patient information, such as medical histories, behavioral patterns, and even personal emotions. This makes the protection of such data critical to ensuring patient confidentiality and compliance with data protection regulations. The rise in cyber threats and data breaches in the healthcare sector highlights the vulnerabilities of AI-based mental health tools, especially when they involve cloud storage and remote communication. For instance, the European Union's General Data Protection Regulation (GDPR) enforces strict guidelines regarding the use of personal health data, and failure to comply can lead to severe penalties. Ensuring that AI systems adhere to data protection regulations like GDPR and Health Insurance Portability and Accountability Act (HIPAA) is crucial in mitigating risks and enhancing user trust.
Ethical and Clinical Effectiveness Challenges:
The deployment of AI in mental health care also faces ethical and clinical effectiveness challenges. First, AI tools must align with ethical standards, including transparency in decision-making and respect for patient autonomy. AI algorithms may inadvertently introduce biases, leading to unfair or inaccurate treatment recommendations. For example, the U.S. Department of Veterans Affairs uses AI to provide mental health care to veterans. While these tools offer significant benefits, their effectiveness must be continuously evaluated to avoid harmful outcomes. Clinical effectiveness also becomes a concern as AI systems may lack the nuanced understanding required for complex mental health conditions. For instance, AI-driven virtual therapy tools may provide less personalized care compared to human professionals. Ensuring that AI-based mental health solutions complement traditional care rather than replace it is crucial for their long-term success.
Market Opportunities:
The integration of AI into mental health care presents numerous opportunities for growth, particularly as demand for accessible and efficient mental health services continues to rise. With the growing prevalence of mental health disorders globally, AI technologies offer scalable solutions to bridge the gap in service delivery. AI-powered applications such as chatbots, virtual therapists, and diagnostic tools are transforming how patients access care, offering real-time support and early diagnosis. For example, the World Health Organization (WHO) has highlighted the growing need for innovative technologies to address mental health issues, particularly in low- and middle-income countries. AI can help overcome barriers like stigma, cost, and limited access to healthcare professionals, making mental health care more widely available.
Moreover, government investments and collaborations with private sector players further create opportunities for AI in mental health care. Initiatives like the European Union’s Horizon Europe program, which allocates significant funding to AI research in healthcare, underscore the potential for continued growth. As governments prioritize mental health and digital health solutions, AI-driven tools can be integrated into national healthcare systems. For instance, the U.S. National Institutes of Health (NIH) has invested heavily in AI technologies to enhance mental health care delivery. This ongoing support from public institutions, combined with private sector innovation, provides a robust foundation for AI to play a central role in improving mental health care outcomes and accessibility in the coming years.
Market Segmentation Analysis:
By Offering
The AI-powered mental health market can be segmented into two main offerings: software and services. The software segment includes AI-driven applications, platforms, and tools that provide users with mental health support, such as virtual therapy apps, chatbots, and diagnostic tools. These AI-powered software solutions enable personalized care, real-time monitoring, and mental health assessments, improving access and efficiency in care delivery. The services segment, on the other hand, refers to the professional services that support the deployment, integration, and maintenance of AI systems, including consultation, training, and support for healthcare providers using AI-based tools.
By Disorder
In terms of disorders, AI technologies are increasingly being used to diagnose and treat a range of mental health conditions. These include anxiety, depression, schizophrenia, post-traumatic stress disorder (PTSD), and insomnia, among others. AI systems can analyze speech patterns, facial expressions, and behavioral data to identify early signs of these disorders. For example, AI can detect signs of depression by analyzing changes in speech tone and patterns. Anxiety and PTSD detection tools also rely on AI to analyze user behavior and identify potential triggers.
Segmentation:
Based on Offering
- Software
- Services
Based on Technology
- Machine Learning
- Deep Learning
- Natural Language Processing
- Text Analytics
- Speech Analytics
- Smart Assistance
- Others
Based on Disorder
- Anxiety
- Depression
- Schizophrenia
- Post-Traumatic Stress Disorder (PTSD)
- Insomnia
- Others
Based on Regional
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the AI-powered mental health market, accounting for 40% of the global market share. The region's strong healthcare infrastructure, coupled with the growing adoption of digital health solutions, drives the demand for AI-based mental health tools. In the U.S., the rapid adoption of telehealth and AI-driven platforms, particularly during the COVID-19 pandemic, has solidified the market's dominance. The U.S. Department of Veterans Affairs, for instance, utilizes AI technologies to offer mental health support to over 200,000 veterans, showcasing the commitment to integrating AI into mental health care systems. Additionally, the presence of major tech companies like Google, Microsoft, and IBM further accelerates market growth, as they continue to innovate and invest in AI applications for mental health.
Europe
Europe holds a significant portion of the AI-powered mental health market, contributing to around 25% of the global market share. The region’s robust healthcare systems, along with the European Union’s funding programs such as Horizon 2020, foster the growth of AI-based mental health technologies. Countries like the UK, Germany, and France have seen significant investment in AI and digital health solutions, which have been essential in addressing mental health challenges exacerbated by the pandemic. The adoption of AI-based virtual therapy platforms and diagnostic tools is growing, as governments and healthcare providers increasingly recognize AI's potential to reduce healthcare costs and improve accessibility. For instance, the UK’s National Health Service (NHS) is exploring AI applications to enhance mental health services and reach a broader population.
Asia Pacific
Asia Pacific is expected to experience the highest growth rate in the AI-powered mental health market, with an anticipated market share increase of around 20% over the next few years. This rapid growth is driven by the region’s large population, increasing awareness of mental health issues, and rising adoption of digital health solutions. Countries like China, India, and Japan are at the forefront of implementing AI in mental health care to address the significant demand for services. In India, for instance, start-ups like Wysa Ltd are developing AI-powered mental health applications to make mental health care more accessible, particularly in rural areas with limited access to professionals. Additionally, Japan’s focus on technological innovation and its aging population provides further impetus for the adoption of AI-driven mental health solutions.
Key Player Analysis:
- Fortis Healthcare
- Microsoft
- NextGen Healthcare
- Wysa Ltd
- Woebot Health
- Spring Care, Inc.
- Lyra Health, Inc.
- Meru
- New Life Solution, Inc. (meQ)
Competitive Analysis:
The competitive landscape of the AI-powered mental health market is rapidly evolving, with key players leveraging innovative technologies to address the growing demand for mental health solutions. Companies like Fortis Healthcare, Google, and Microsoft are at the forefront, integrating AI into their platforms to enhance mental health care delivery through virtual therapy, diagnostics, and real-time support. Start-ups such as Wysa Ltd, Woebot Health, and Lyra Health are also making significant strides with AI-driven chatbots and personalized mental health tools aimed at improving accessibility and reducing barriers like stigma and cost. Additionally, companies like SilverCloud and HEADSPACE Health are offering comprehensive digital mental health platforms that combine AI with therapeutic content to support users. While established tech giants bring scalability and vast resources, emerging players focus on niche, user-centric solutions. This diverse market dynamic is pushing continuous advancements in AI technologies to improve patient outcomes and increase adoption across various regions.
Recent Developments:
- In April 2024, Fortis Healthcare launched Adayu Mindfulness, an AI-powered chatbot aimed at assisting individuals with mental health challenges. This app functions as a psychological support tool, providing help similar to a first aid kit, especially for those hesitant to seek professional help due to societal stigma.
- In March 2023, Aiberry secured USD 8 million in seed funding, backed by Confluence Capital Group, Inc. (CCG) and the VC fund Ascension AI. With this new investment, Aiberry’s total funding reaches USD 10 million. The funds will be used to accelerate the adoption of the Aiberry platform, which features an AI-powered therapeutic assistant that engages in conversations to detect mental health disorders by analyzing verbal content, subtle facial expressions, and speech patterns.
Market Concentration & Characteristics:
The AI in mental health market exhibits moderate concentration, with a mix of established tech giants and emerging startups. Leading companies like Google, Microsoft, and IBM are leveraging their extensive resources and AI expertise to drive innovation and shape the future of mental health care. These players dominate the market through strategic partnerships, acquisitions, and the development of scalable solutions. However, numerous start-ups, such as Wysa Ltd, Woebot Health, and Lyra Health, are making notable contributions by focusing on personalized, AI-driven mental health applications and tools. These smaller companies are gaining traction by targeting niche areas, such as mental health for specific populations or addressing gaps in underserved regions. The market's characteristics include rapid technological advancements, a focus on data security and privacy, and the increasing adoption of digital health solutions, driving competition and fostering innovation across the entire AI in mental health ecosystem.
Report Coverage:
The research report offers an in-depth analysis based on By Offering, By Technology, By disorder, By Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- AI-powered mental health solutions will continue to evolve, offering more personalized and accessible care to users worldwide.
- The integration of AI in mental health care will streamline diagnosis, treatment, and continuous monitoring, improving patient outcomes.
- Increased adoption of virtual therapy and telehealth platforms will expand mental health care access, particularly in underserved regions.
- Advancements in natural language processing and machine learning will enhance the accuracy of AI-driven mental health assessments.
- The growing demand for mental health services due to societal stigma reduction will fuel the development of AI-powered tools.
- Governments and healthcare organizations will continue investing in AI research to improve mental health service delivery and reduce healthcare costs.
- AI technologies will be key in the early detection of mental health conditions, enabling timely intervention and better prevention strategies.
- The expansion of AI in mental health care will drive collaborations between private sector companies and government bodies to create innovative solutions.
- Data privacy and security will remain a critical focus, prompting improvements in AI systems to ensure compliance with global regulations.
- The future will see increased market penetration of AI-based solutions in mental health care, benefiting both patients and healthcare providers globally.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the AI in mental health market?
What factors are driving the AI in mental health market?
What are the key segments within the AI in mental health market?
What are some challenges faced by the AI in mental health market?
Who are the major players in the AI in mental health market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 AI in Mental Health Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global AI in Mental Health Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 967.67 million → 2032: USD 10,650.44 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 AI in Mental Health Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. AI in Mental Health Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 AI in Mental Health Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 AI in Mental Health Market Drivers
- 3.3 AI in Mental Health Market Restraints & Challenges
- 3.4 AI in Mental Health Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 AI in Mental Health Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 AI in Mental Health Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, AI in Mental Health category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 AI in Mental Health Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. AI in Mental Health Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the AI in Mental Health market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 AI in Mental Health Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 AI in Mental Health Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 AI in Mental Health Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in AI in Mental Health (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New AI in Mental Health Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global AI in Mental Health Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America AI in Mental Health Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe AI in Mental Health Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific AI in Mental Health Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America AI in Mental Health Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East AI in Mental Health Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa AI in Mental Health Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. AI in Mental Health Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
